Showing posts sorted by relevance for query Shower Products Segment. Sort by date Show all posts

Wednesday, February 21, 2018

Bath and Shower Products Report on Global and United States Market Status & Forecast, by Players, Types and Applications 2017-2022

Read article : Bath and Shower Products Report on Global and United States Market Status & Forecast, by Players, Types and Applications 2017-2022

Qyresearchreports include new market research report “2017-2022 Bath and Shower Products Report on Global and United States Market, Status and Forecast, by Players, Types and Applications” to its huge collection of research reports.

The report on Global and United States Bath and Shower Products market is an in-depth study of the industry, including its present, past, and future performance. The various factors driving the Global and United States Bath and Shower Products market towards growth has been analyzed and so are the challenging factors hampering the growth of the market. The impact analysis of both the growth drivers and restraining factors has been included in the report. Also included is the information pertaining to degree of competition, bargaining power of suppliers, threat of substitutes, bargaining power of buyers, and threat of new entrants. The information thus given is extremely resourceful and comes in handy to all those wishing to invest in the Global and United States Bath and Shower Products market. The report enables investors and market players both new and established, to make profitable decisions regarding investments in the Global and United States Bath and Shower Products market.

The report segments the Global and United States Bath and Shower Products market on the basis of key criteria and studies each of the segment and sub-segment in a comprehensive, detailed manner. Factors leading to the growth or decline of the segment and the reasons behind them are also given. The report lists out the fastest growing segment, the leading segment, and the declining segment, which helps investors to get a clear idea on which segment to invest on, that will reap benefits in the long run. The report also studies key players operating in the Global and United States Bath and Shower Products market. The business and financial overview of each of those companies along with their recent contribution to the growth of the market have been included. The expansion strategies and business planning adopted by these players are given in the report, thus helping new players to formulate strategies and incur profits in the market.

For more information on this report, fill the form @ http://www.qyresearchreports.com/sample/sample.php?rep_id=1121739&type=E

Table of Contents

1 Methodology and Data Source
1.1 Methodology/Research Approach
1.1.1 Research Programs/Design
1.1.2 Market Size Estimation
1.1.3 Market Breakdown and Data Triangulation
1.2 Data Source
2.1.1 Secondary Sources
2.1.2 Primary Sources
1.3 Disclaimer

2 Bath and Shower Products Market Overview
2.1 Bath and Shower Products Product Overview
2.2 Bath and Shower Products Market Segment by Type
2.2.1 Soap and Shower Gel
2.2.2 Body Scrub
2.2.3 Shower Brush
2.2.4 Shower Sponge
2.3 Global Bath and Shower Products Product Segment by Type
2.3.1 Global Bath and Shower Products Sales (K Units) and Growth (%) by Types (2012, 2016 and 2022)
2.3.2 Global Bath and Shower Products Sales (K Units) and Market Share (%) by Types (2012-2017)
2.3.3 Global Bath and Shower Products Revenue (Million USD) and Market Share (%) by Types (2012-2017)
2.3.4 Global Bath and Shower Products Price (USD/Unit) by Type (2012-2017)
2.4 United States Bath and Shower Products Product Segment by Type
2.4.1 United States Bath and Shower Products Sales (K Units) and Growth by Types (2012, 2016 and 2022)
2.4.2 United States Bath and Shower Products Sales (K Units) and Market Share by Types (2012-2017)
2.4.3 United States Bath and Shower Products Revenue (Million USD) and Market Share by Types (2012-2017)
2.4.4 United States Bath and Shower Products Price (USD/Unit) by Type (2012-2017)

Browse Market Research Report @ http://www.qyresearchreports.com/report/2017-2022-bath-and-shower-products-report-on-global-and-united-states-market-status-and-forecast-by-players-types-and-applications.htm

3 Bath and Shower Products Application/End Users
3.1 Bath and Shower Products Segment by Application/End Users
3.1.1 Household
3.1.2 Commercial Use
3.2 Global Bath and Shower Products Product Segment by Application
3.2.1 Global Bath and Shower Products Sales (K Units) and CGAR (%) by Applications (2012, 2016 and 2022)
3.2.2 Global Bath and Shower Products Sales (K Units) and Market Share (%) by Applications (2012-2017)
3.3 United States Bath and Shower Products Product Segment by Application
3.3.1 United States Bath and Shower Products Sales (K Units) and CGAR (%) by Applications (2012, 2016 and 2022)
3.3.2 United States Bath and Shower Products Sales (K Units) and Market Share (%) by Applications (2012-2017)

4 Bath and Shower Products Market Status and Outlook by Regions
4.1 Global Market Status and Outlook by Regions
4.1.1 Global Bath and Shower Products Market Size and CAGR by Regions (2012, 2016 and 2022)
4.1.2 North America
4.1.3 Asia-Pacific
4.1.4 Europe
4.1.5 South America
4.1.6 Middle East and Africa
4.1.7 United States
4.2 Global Bath and Shower Products Sales and Revenue by Regions
4.2.1 Global Bath and Shower Products Sales (K Units) and Market Share (%) by Regions (2012-2017)
4.2.2 Global Bath and Shower Products Revenue (Million USD) and Market Share (%) by Regions (2012-2017)
4.2.3 Global Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
4.2.4 North America Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
4.2.5 Europe Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
4.2.6 Asia-Pacific Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
4.2.7 South America Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (2012-2017)
4.2.8 Middle East and Africa Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
4.2.9 United States Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (2012-2017)

5 Global Bath and Shower Products Market Competition by Players/Manufacturers
5.1 Global Bath and Shower Products Sales (K Units) and Market Share by Players (2012-2017)
5.2 Global Bath and Shower Products Revenue (Million USD) and Share by Players (2012-2017)
5.3 Global Bath and Shower Products Average Price (USD/Unit) by Players (2012-2017)
5.4 Players Bath and Shower Products Manufacturing Base Distribution, Sales Area, Product Types
5.5 Bath and Shower Products Market Competitive Situation and Trends
5.5.1 Bath and Shower Products Market Concentration Rate
5.5.2 Global Bath and Shower Products Market Share (%) of Top 3 and Top 5 Players
5.5.3 Mergers & Acquisitions, Expansion

6 United States Bath and Shower Products Market Competition by Players/Manufacturers
6.1 United States Bath and Shower Products Sales (K Units) and Market Share by Players (2012-2017)
6.2 United States Bath and Shower Products Revenue (Million USD) and Share by Players (2012-2017)
6.3 United States Bath and Shower Products Average Price (USD/Unit) by Players (2012-2017)
6.4 United States Bath and Shower Products Market Share (%) of Top 3 and Top 5 Players

7 Bath and Shower Products Players/Manufacturers Profiles and Sales Data
7.1 Lush
7.1.1 Company Basic Information, Manufacturing Base and Competitors
7.1.2 Bath and Shower Products Product Category, Application and Specification
7.1.2.1 Product A
7.1.2.2 Product B
7.1.3 Lush Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
7.1.4 Main Business/Business Overview
7.2 Nivea
7.2.1 Company Basic Information, Manufacturing Base and Competitors
7.2.2 Bath and Shower Products Product Category, Application and Specification
7.2.2.1 Product A
7.2.2.2 Product B
7.2.3 Nivea Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
7.2.4 Main Business/Business Overview
7.3 Fresh
7.3.1 Company Basic Information, Manufacturing Base and Competitors
7.3.2 Bath and Shower Products Product Category, Application and Specification
7.3.2.1 Product A
7.3.2.2 Product B
7.3.3 Fresh Bath and Shower Products Sales (K Units), Revenue (Million USD), Price (USD/Unit) and Gross Margin (%) (2012-2017)
7.3.4 Main Business/Business Overview

About Us

QYReseachReports.com delivers the latest strategic market intelligence to build a successful business footprint in China. Our syndicated and customized research reports provide companies with vital background information of the market and in-depth analysis on the Chinese trade and investment framework, which directly affects their business operations. Reports from QYReseachReports.com feature valuable recommendations on how to navigate in the extremely unpredictable yet highly attractive Chinese market.

Contact Us

1820 Avenue
M Suite #1047
Brooklyn, NY 11230
United States
Toll Free: 866-997-4948 (USA-CANADA)
Tel: +1-518-621-2074
Email: sales@qyresearchreports.com
Blog – qyresearch-group.blogspot.in

Saturday, April 1, 2017

Global Bath and Shower Products Market Report 2015-2019 - Research and Markets

Read article : Global Bath and Shower Products Market Report 2015-2019 - Research and Markets

DUBLIN--(BUSINESS WIRE)--Research and Markets (http://www.researchandmarkets.com/research/qgfnzv/global_bath_and) has announced the addition of the "Global Bath and Shower Products Market 2015-2019" report to their offering.

The global bath and shower products market to reach a market value of around USD 15 billion by the end of 2019.

Shower products dominated the market during 2014 with a market share of around 70%. The report predicts this segment to retain its leadership until the end of 2019 growing at a rate of around 4%. This segment includes products such as shower gels, shower creams, exfoliates, body shampoo, mousses, loofah, bath brush, body polishers, and foot scrubs.
The increasing awareness about health and hygiene is the primary driver for the growth of this market. Consumers are being exposed to reliable information about the various bath products through the internet, television, and other sources of information. The rise in living standards and income are also leading consumers to opt for more expensive and aesthetically appealing bath and shower products with different fragrances and effective ingredients.
The increased demand for organic products is also anticipated to contribute to the market growth during the forecast period. Organic shampoo manufacturers are focusing on developing new products by adding value to the basic cleansing action of shampoos. For instance, dry shampoos are available either in spray or powder formats and are used to absorb dirt and oil on the hair and scalp. They save time and effort, and also help in retaining the natural hair oils that are washed out by standard shampoos.

Europe accounted for the largest market share of around 48% during 2014. The evolving buying patterns of consumers is the primary growth driver of the market in this region. The growing affinity of the consumers towards organic and natural bath and shower products with specific ingredients has helped to boost sales of these products.

Product segmentation and analysis of the bath and shower products market

Segmentation by retail format and analysis of the bath and shower products market

The supermarkets and hypermarkets segment accounted for 53% of the market share during 2014. Supermarkets store numerous bath and shower products providing consumers with a variety of choices for purchasing.

The top five vendors in the market are

  • Johnson & Johnson
  • L'Oreal
  • P&G
  • Unilever
  • Colgate-Palmolive

Other vendors in the market include

  • Avon
  • Bath and Body Works
  • Beiersdorf
  • Coty
  • Estee Lauder
  • Henkel
  • Kao
  • L'Occitane
  • Lush
  • Revlon
  • Soap and Glory

Key Topics Covered:

Part 01: Executive summary

Part 02: Scope of the report

Part 03: Market research methodology

Part 04: Introduction

Part 05: Market landscape

Part 06: Market segmentation by product

Part 07: Market segmentation by retail formats

Part 08: Geographical segmentation

Part 09: Key leading countries

Part 10: Market drivers

Part 11: Impact of drivers

Part 12: Market challenges

Part 13: Impact of drivers and challenges

Part 14: Market trends

Part 15: Vendor landscape

Part 16: Key vendor analysis

Part 17: Appendix

For more information visit http://www.researchandmarkets.com/research/qgfnzv/global_bath_and

Saturday, April 29, 2017

Parryware Unveils "Crestia" The Premium Segment Bathroom Solutions for Mumbai

Read article : Parryware Unveils "Crestia" The Premium Segment Bathroom Solutions for Mumbai

Parryware Unveils "Crestia" The Premium Segment Bathroom Solutions for Mumbai

Parryware Roca Private Limited, No 1 bathroom solutions provider in India today launched the premium international "Crestia Collection" in Mumbai. The Crestia collection constitutes 22 completely new products with international styling and attractive features.

Tweet

Chennai, Tamil Nadu, September 30, 2008 /India PRwire/ -- Parryware Roca Private Limited, No 1 bathroom solutions provider in India today launched the premium international “Crestia Collection” in Mumbai. The Crestia collection constitutes 22 completely new products with international styling and attractive features.

The Crestia collection includes a wide range of international sanitaryware and shower solutions that cater to the discerning Indian customer who is looking for “affordable luxury”. In addition to the new products, the existing products ensure that the slew of products from the Crestia Collection aggressively dominate the top end sanitaryware market in India.

At the launch, Mr. Emilio Salazar, Managing Director, Parryware Roca Private Limited said, “Crestia symbolizes Parryware’s effort to constantly make its offerings contemporary and in line with the needs of the changing Indian customer. From the trusted Parryware stable, the all new Crestia Collection promises to deliver ‘WOW’ bathrooms with high quality products and assured back up service.”

Mr. Salazar, added, “The premium market for sanitary ware in India is today estimated at Rs 130 crores per annum, Parryware commands a 10% share of the Premium segment. With the launch of Crestia Collection, we are confident of further improving our share in this segment in the coming months.”

The current market size for bathroom solution products is Rs 900 crore, in which the organized sector accounts for Rs 500 crore while the rest is from the unorganized sector. Parryware is witnessing a growth rate of 22 per cent. In the premium segment alone, which is growing at 25 per cent, it has a market share of 20 per cent.

Notes to Editor

About Parryware Roca Private Limited

Parryware Roca Private Limited is owned by ROCA Sanitario – a world leader in sanitary ware based in Barcelona, Spain. Parryware Roca in India has the entire range of products that include vitreous sanitaryware, seat covers, plastic cisterns, bath tubs, kitchen sinks, and electronic flushing systems. Parryware is the first and only sanitaryware Brand in India to be conferred ‘Superbrand of India’ status. From being a sanitaryware brand, Parryware is transforming itself into a total bathroom solutions provider with the successful launch of its Faucets range.

ROCA a World leader in the bathroom solutions market has presence in more than 120 countries with a Group turnover amounting to approximately Euro 1.7 billion (Rs 8500 crores). ROCA is ranked World No.1 in the sanitaryware market.

Roca has been ranked world No 1 and Parryware Roca ranked No. 9 in the world in the sanitaryware industry by Ceramics World in 2008.

Saturday, September 30, 2017

Media News – Parryware Unveils Crestia range of Bathroom Solutions

Read article : Media News – Parryware Unveils Crestia range of Bathroom Solutions

Parryware Roca Private Limited has launched the premium international “Crestia Collection” in Mumbai. The Crestia collection constitutes 22 completely new products with international styling and attractive features.

The Crestia collection includes a wide range of international sanitaryware and shower solutions that cater to the discerning Indian customer who is looking for “affordable luxury”. In addition to the new products, the existing products ensure that the slew of products from the Crestia Collection aggressively dominate the top end sanitaryware market in India.

At the launch, Emilio Salazar, Managing Director, Parryware Roca Private Limited said, “Crestia symbolizes Parryware’s effort to constantly make its offerings contemporary and in line with the needs of the changing Indian customer. From the trusted Parryware stable, the all new Crestia Collection promises to deliver ‘WOW’ bathrooms with high quality products and assured back up service.”

Salazar, added, “The premium market for sanitary ware in India is today estimated at Rs 130 crores per annum, Parryware commands a 10% share of the Premium segment. With the launch of Crestia Collection, we are confident of further improving our share in this segment in the coming months.”

The current market size for bathroom solution products is Rs 900 crore, in which the organized sector accounts for Rs 500 crore while the rest is from the unorganized sector. Parryware is witnessing a growth rate of 22 per cent. In the premium segment alone, which is growing at 25 per cent, it has a market share of 20 per cent.

Parryware Roca Private Limited is owned by ROCA Sanitario – a world leader in sanitary ware based in Barcelona, Spain. Parryware Roca in India has the entire range of products that include vitreous sanitaryware, seat covers, plastic cisterns, bath tubs, kitchen sinks, and electronic flushing systems. Parryware is the first and only sanitaryware Brand in India to be conferred ‘Superbrand of India’ status. From being a sanitaryware brand, Parryware is transforming itself into a total bathroom solutions provider with the successful launch of its Faucets range.

ROCA a World leader in the bathroom solutions market has presence in more than 120 countries with a Group turnover amounting to approximately Euro 1.7 billion (Rs 8500 crores). ROCA is ranked World No.1 in the sanitaryware market. Roca has been ranked world No 1 and Parryware Roca ranked No. 9 in the world in the sanitaryware industry by Ceramics World in 2008.

Tuesday, January 9, 2018

Are Bathrooms Really that Sensual?

Read article : Are Bathrooms Really that Sensual?

We explore what makes sexuality such an oft-visited subject in the sanitary-ware segment.

Your hands are the most beautiful part of your body - one that helps you to share food, express love and show joy. Then, why do we use it for the, uhm, nasty business - asks Kohler in a new campaign - Hands are made for Love. Designed by Ogilvy & Mather, it questions the Indian habit of using hands for cleaning in the washroom.

Kohler's old Demolish ad played on the aspirational featureHindware's Designs to Desire campaignRoca's international campaign which is now in IndiaThe H&R Johnson TVCKohler's 'Hands are made for Love' campaign
Ajay Gahlaut
Salil Sadanandan
Sushil Matey
Ramesh Kaushik
Vijay Asrani
Sushil Luniya
"It was a tricky brief. Usually people do not wish to talk about it. So, the challenge was not just to talk, but talk nicely about something people do not wish to acknowledge. We needed a higher order emotional appeal to tell people not to use their hands for things which do not reflect your feelings," says Ajay Gahlaut, ECD, Ogilvy North India.

Kohler plays in an area of hygiene that is not pleasant. Add to that the fact that television is usually watched around dinner time when the family is together. Keeping all this in mind, Kohler had to come up with something that talks about the functionality and yet not make it gross.

"In India, water is not just a rational thing. It is meant for purification. Therefore, saying that using water and hands is wrong would not work. We needed a positive angle to the story and decided to show what the same hands can express and do," reflects Salil Sadanandan, managing director, Kohler India.

But sensual?

Kohler's ad stands in stark contrast to other recent examples, which show bathrooms as stylish, and even sensual, places. The common notion is that it is important to play up sensuality to give the space a premium imagery. The segment in which Kohler, or brands like Roca, Artize (from the house of Jaquar) play are in the premium segment. Of the total market size of 28-30 million pieces, 55 per cent is unorganised. Of the organised market, only 18 per cent is the life-style (or premium) market. Though this pie is small, it is growing at twice the speed of standard segments.

A regular Indian will remodel his house maybe once in 10 years. Therefore, the brand must speak to the consumer in the moment he is about to make the decision and stimulate the experience in a way that other shorter term products cannot do (such as paints which are changed every two to five years).

According to Sushil Matey, chief operating officer, H&R Johnson, bathrooms are also the most intimate of spaces. "We clear our minds in this space. Many strategic and mundane issues are solved by us in the bathroom."

But most importantly, the middle class is expanding at a very rapid pace. With higher disposable incomes it is possible to afford luxuries which could not be thought of before. Increasing exposure to foreign lifestyles, rising disposable incomes and pride in their house has made the bathroom segment grow as much as the living room or kitchen has.

"The people we target are usually the well-travelled Indians. They are used to a certain level of class and luxury when they travel, and they are now slowly trying to demand the same in their own homes. Every bathroom in this case is a new statement," explains Ramesh Kaushik, marketing head, Grohe India.

Kaushik feels that bathrooms have evolved from one of the most neglected to the most aspired category in India. Grohe has taken this opportunity to speak to the upper middle class (and upwards). But understanding the joint family system in India is imperative for the brand and, therefore, they make their campaigns around the whole family. However many of the campaigns around the bath fittings segment show only a nuclear couple - maybe to add to the sensual factor.

But are these stylish bath fittings affordable? The entry level products from Parryware comes at Rs 100 while the premium segment by sister brand, Roca is priced at Rs 180. The core target for Parryware is the family, but for Roca is the nuclear couple.

The other target

Whether it is the family or the nuclear couple living by themselves, customers are most likely to invest in bath fittings that their developer or interior decorator suggests. So while a consumer will love an ad that she sees on TV, the developer's choice will be final.

In some cases, like Roca, brands invest more in the retail market. "We bring out campaigns that appeal to both the developer and consumer. This is especially helpful because a chunk of our client is from the hospitality industry, where the brand's name is of high value to the clients," explains Vijay Asrani, marketing head, Roca. The company's revenue is split 70-30 in favour of retail sellers as against institutional sellers.

On the other hand, Kohler's advertising is divided equally between the retail consumers and institutional buyers. A separate team looks after the 'decision-making' markets - consisting of developers, architects and designers.

Taking it a step further is HSIL, which makes sanitary-ware under the brand name Hindware. The company has developed a DVD app - Bathroom Planner - which makes the Hindware product range available to any user. The user can manage up to five projects at a time, can create five bathroom drawings for each project and compare a maximum of four designs for each bathroom product required.

"Today micro-targeting and content marketing is gradually setting the trend in the marketing sphere. This calls for customisation and personalisation of strategies to reach a niche set of consumers. In this case, we are talking of interior designers and architects," explains Sushil Luniya, president (marketing & sales), building products division, HSIL.

Much water under the bridge

With already a handful of players in the market, will the bathroom category show any new surprises? According to Kohler's Sadanandan, only 42 per cent Indian citizens have access to water-based sanitation. He sees the bottom end growing quickly adding more volume to the industry, while the top end will grow as more and more people move into a luxurious urban lifestyle.

Saji Abraham
Jagdeep Kapoor
According to Saji Abraham, executive vice president, planning, Lowe Lintas, India is emerging from the functional middle class existence it has had all this while. More and more people are seeking luxury and masstige has become a popular segment. That is a reason why there will always be a case for luxury even in bathrooms.

"You may not end up owning Jaguar's top of the line bathroom fittings, but imagine your joy, next time you have to change a tap there is a nifty Jag tap available albeit a bit more expensive. You would want a piece of that utopian bathroom wouldn't you?" asks Abraham.

Jagdeep Kapoor, chairman and managing director, Samsika Marketing Consultants however feels there should be a balance in functionality and aesthetics. While showing a shower working takes the functionality part, sensuality looks at the aesthetics. "Moreover, these advertisements have two purposes - to excite the end user and to excite the influencer. If the consumer brings in the pull factor, the influencer works as the push factor," he says.

  • 49/>

Saturday, February 17, 2018

Beauty Spree at Taipei Ximending 4-Storey Watsons

Read article : Beauty Spree at Taipei Ximending 4-Storey Watsons

ximending watsons

Image credits: euphonicsins

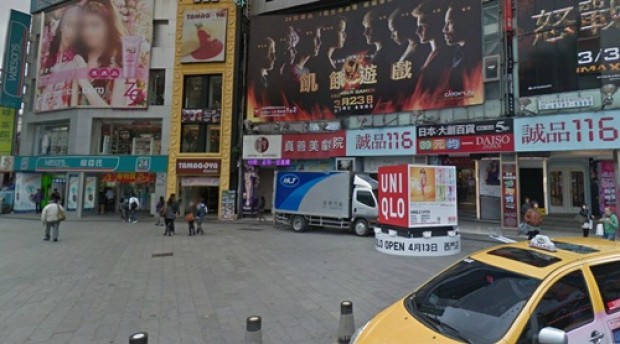
屈臣氏 (西門店) Watsons Ximending
台北市萬華區成都路15號
No. 15, Chengdu Rd, Wanhua District Taipei City, Taiwan 108

Nearest station: Ximen Station, Exit 6

You will be able to spot Watsons opposite Ximen Station Exit 6 when you exit Ximen Station from Exit 6. Watsons Ximending is just beside Eslite 116.

The Watsons in Ximending is not one, two, but four storeys! What’s more, it’s 24 hours! Woohoo! And that means I need not worry about having to rush back to Ximending area at night if I were to head off to further places in the day because normally when I step into Watsons, Watsons in Taiwan to be specific, I don’t just come out empty-handed. I wouldn’t want to lug my buys from Watsons out in the day when I go out so I normally shop at Watsons back at Ximending near my hotel at night. And because it’s 24 hours, I can even head back to my hotel to leave my shopping bags from the day, freshen up myself a little before heading down to Watsons Ximending to stock up on beauty and skincare products.

Also read: Top 10 Cult Korean Beauty Brands for Your Shopping Haul

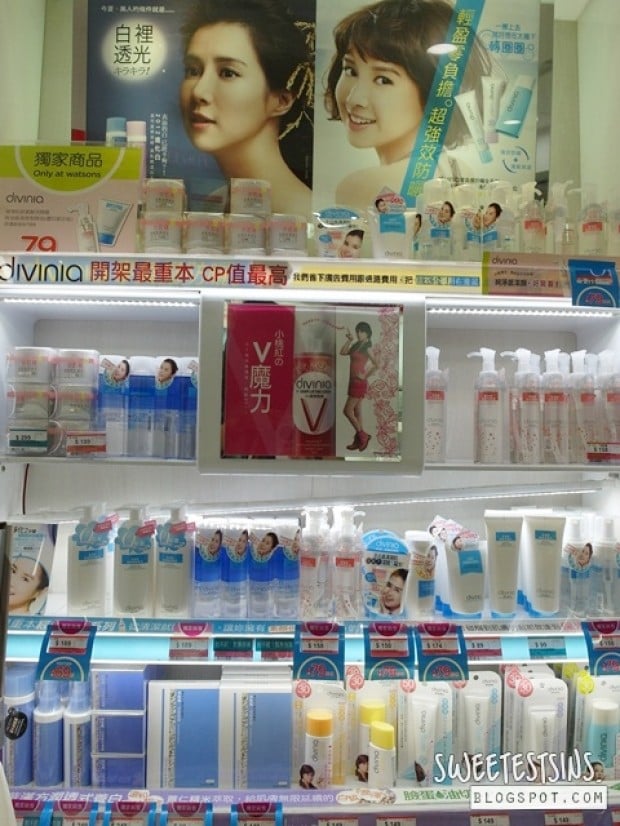
The first brand that caught my attention was Divinia 蒂芬妮亞. It’s exclusively available at Watsons in Taiwan. I like how Watsons always have brands that are exclusive to them be in Singapore, Taiwan or other countries.

Divinia 蒂芬妮亞

https://zh-tw.facebook.com/diviniaTW
http://www.watsons.com.tw/divinia

Divinia 蒂芬妮亞 highest rated product on UrCosme is 輕快眼唇卸妝液 (literally translated as Quick Eye & Lip Makeup removal liquid), NTD199(approx. SGD8.7). It was UrCosme’s No. 2 Eye and Lip Makeup removal in 2011.

Here are what I found interesting from Divinia 蒂芬妮亞.

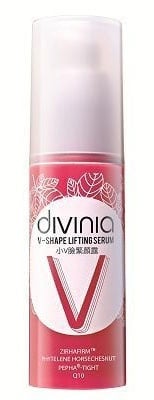
1. V-Shape lifting serum 小V臉緊顏露 NTD450 (SGD19.6)

Doesn’t this remind you of Clarins Shaping Facial Lift Lip-drain serum? Only that it’s retailing at less than 1/5 of the price. While I haven’t tried either of the products from Clarins or Divinia, my Uni friend whom worked at Clarins is a fan of Clarins Shaping Facial Lift Lip-drain serum. She says that it does help to lift the face and make it more V-shaped looking. Have any of you girls tried Clarins Shaping Facial Lift Lip-drain serum? Does it work for you girls? Let me know by leaving a comment at the end of this post.

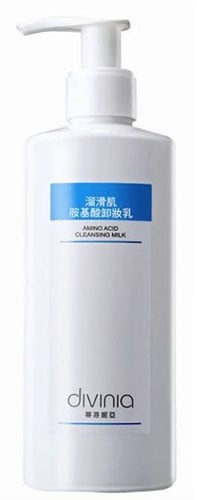
2. Amino acid cleansing milk 溜滑肌胺基酸卸妝乳 NTD189 (SGD8.2)

I have tried Amino Acid products for my hair and I liked it. I went for a facial recently and my facialist was asking me what kind of makeup removal do I use. When I told her that I use cleansing water, she was quite shocked and she recommended that I use cleansing milk instead as cleansing milk contains a bit of oil and it helps to remove makeup and impurities better compared to cleansing water. Although I don’t know how true that is, I think I’m still going to stick with my Biorderma Micelle Solution aka cleansing water at least until I finish using it.

I don’t know about you guys but for me, I like different makeup removal during different stages or period in my life. I started off with using Fancl Mild Cleansing Oil and I swear by it until I had very bad breakouts when I was in Poly and I switched to Cleansing Milk. My favourite was Eucerin Gentle Cleansing Milk. When I discovered cleansing water, my first bottle was Uriage L’eau Demaquillante cleansing water micellar solution, I knew there was no turning back. So far, I have tried cleansing water from brands such as Dr Wu, Caudalie, Avene and Uriage just to name a few.

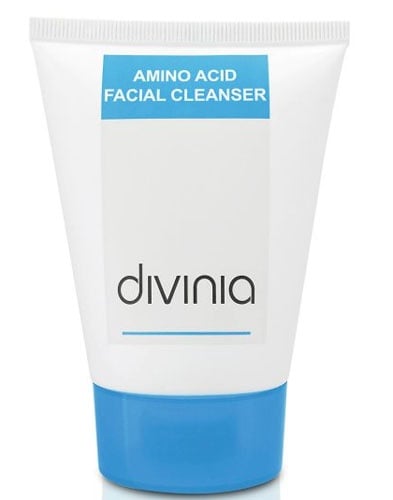
3. Amino acid facial cleanser 溜滑肌胺基酸洗顏霜 NTD189 (SGD8.2)

As much as I love buying cleansers when I’m overseas, I have no idea why I didn’t pick this up when I was in Taiwan earlier this May. You know, it’s really tough on me writing this post without blaming myself, “Ah, why didn’t I get this product back then when I was in Taiwan?” But then again, I wanted to share with you guys the products available in Taiwan Watsons so that you guys have an idea of what to buy and expect on your next trip there and maybe prepare / budget how much you are going to spend on beauty and skincare products (this never ever happens to me haha).

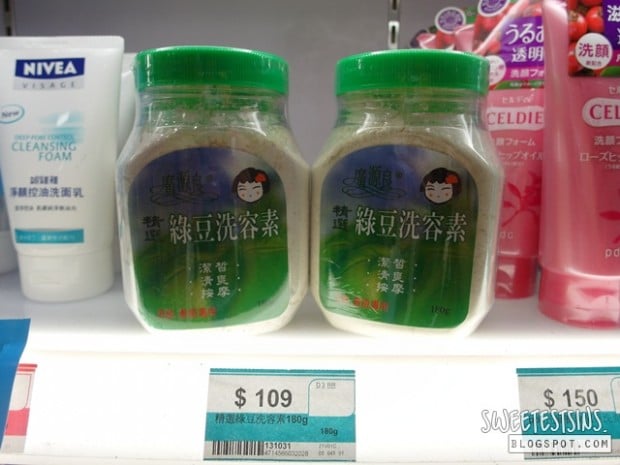
廣源良綠豆洗容素 Mung Bean (Green Bean) Cleansing Powder

I first came to know about the benefits of Mung Bean (Green Bean) Cleansing Powder through a Taiwan drama, 犀利人妻/ Xi Li Ren Qi (The Fierce Wife). Xie An Zhen 謝安真 played by Sonia Sui was a happily married housewife with a kid. She was the typical easily contended housewife and in one of the episodes, she was out shopping with a friend or family member who asked her to get herself some skincare products to maintain her youth and Xie An Zhen went like, “I have my Mung Bean (Green Bean) Cleansing Powder – it’s super affordable and it does the trick.” I remember asking my Mom where I can get Mung Bean Cleansing Powder right after watching the drama and we came across it in one of the Organic store in our neighbourhood while we were there stocking up on our organic supplies.

Also read: Eccentric Beauty Treatments Around the World: Semen, Poop and Snakes

The main ingredients are Job’s tears / coix seeds and it contains no preservatives. It’s a multifunction product. You can use it to cleanse your face, as a face mask, as a mask or even add it to your cold mask.

I was super super super excited when I saw the following –

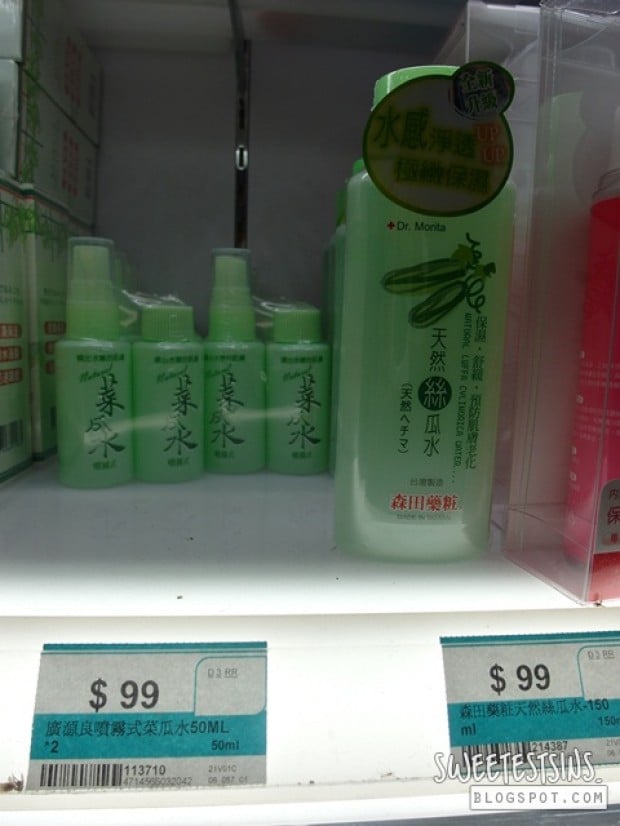
森田藥粧 天然絲瓜水 Dr Morita Natural Luffa Cylindrica Water

Why am I so excited upon seeing 森田藥粧 天然絲瓜水 Dr Morita Natural Luffa Cylindrica Water? Well, it is because I read from Taiwan Beauty Blogs that 絲瓜水 Luffa Cylindrica Water is good in combating redness on the face and also helps to clean and shrink pore size. Since it’s only NTD99 (approx SGD4.20), I grabbed one to try.

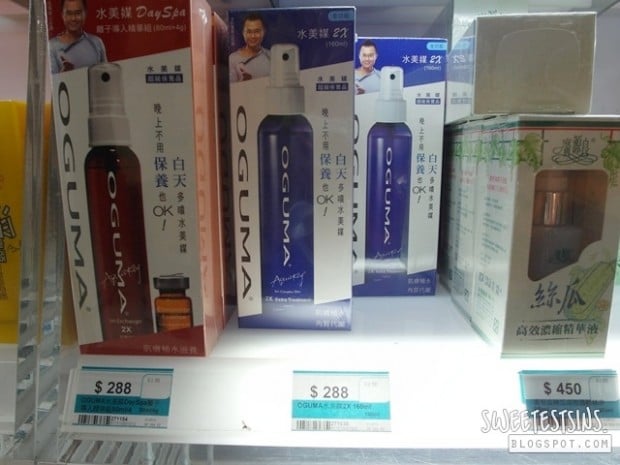
Oguma 水美媒聰明購

http://www.oguma.com.tw

Oguma is a brand that I frequently see in 女人我最大 Nu Ren Wo Zui Da magazine.

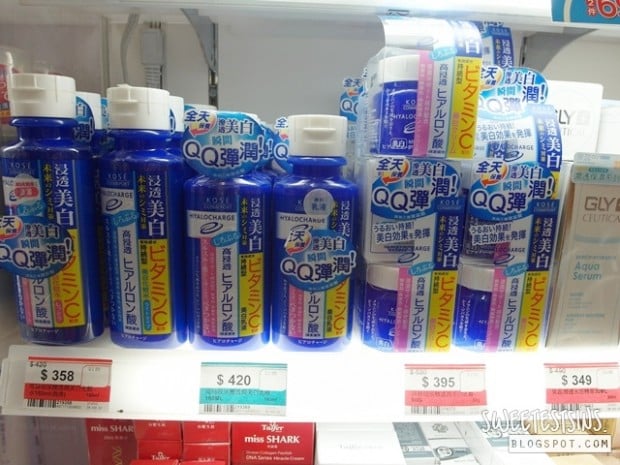
Kose Hyalocharge series 高絲玻尿酸淨白

I would have gotten a product from Kose Hyalocharge series to try if it’s not for whitening as my skin can’t really take whitening products now apart from a few brands.

Kose Cosmeport 高絲蔻絲魅寶

I bought Kose Cosmeport Softymo Hyaluronic Acid Facial Washing Foam when I was in Hong Kong and both Mommy and I love it. You can read my review here, http://sweetestsins.blogspot.sg/2012/06/back-to-basics.html.

Next, I checked out the haircare section. When it comes to grooming, the most important would be 1) face, followed by 2) hair.

I get a lot of questions on how to maintain long hair. Actually, maintaining long hair isn’t as difficult as you think it is. In terms of shampoo, choose a shampoo that is suitable for your scalp. You can have oily hair but dry scalp or oily scalp but dry hair so make sure you choose your shampoo correctly. You wouldn’t want to end up with an itchy scalp, trust me. After shampooing, you would want to condition the ends of your hair. For conditioning, you can use either a conditioner or hair treatment/hair mask. Personally, I skip conditioner and I use hair treatment/hair mask after shampooing. If you recall, in some of my blog posts, I mentioned before how fast I run out of cleansers and toner/lotion. Another product that I use up very quickly and need replenishing is – hair treatment/hair mask. I think I use up a tube or a tub every other month! My friends were like, “Are you serious?”

I love hair masks and hair treatments. And I love trying out brands that ain’t available in Singapore so imagine how hard I had to control myself when I was in Watsons Ximending and try not to pick up every other product.

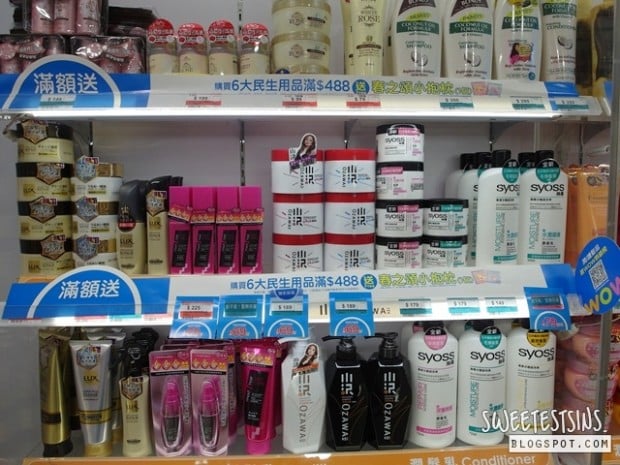
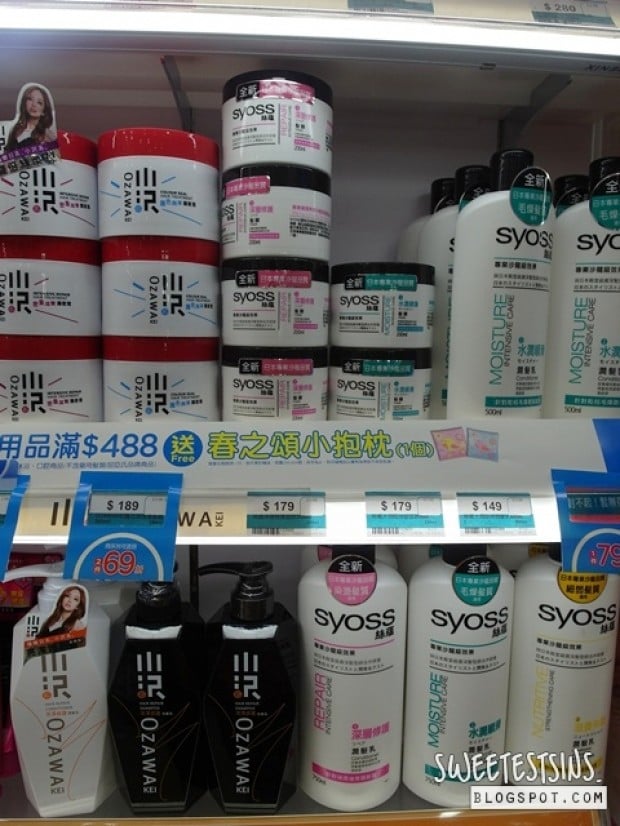
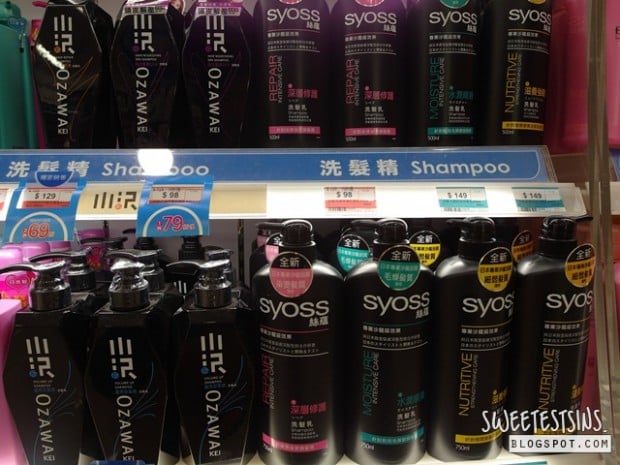
LUX, Ozawa, Mod hair, Syoss and Living Type

Ozawa and Syoss shampoo and hair treatment

more Ozawa and Syoss shampoo

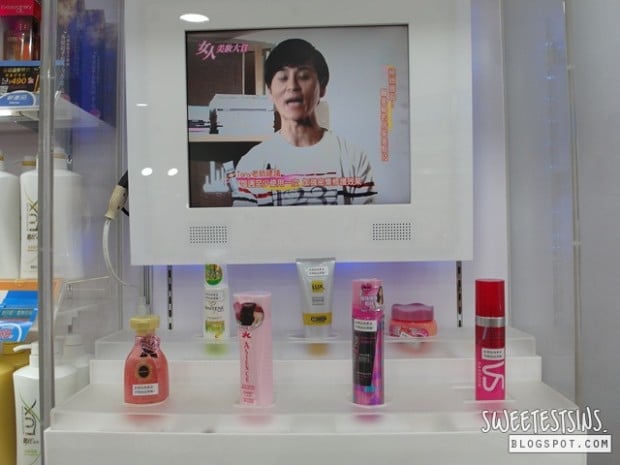
While checking out the hair products available, I came across this LCD screen that featured Tony 老师 / Tony Lao Shi ‘s recommendations from one of 女人我最大 Nu Ren Wo Zui Da ‘s segment.

1. Pantene Pro-V Natural Care Lift Up Mist Leave On Treatment2. LUX Japan Black Diamond Super Rich Shine Hair Treatment
3. KAO Essential Damage Honey Shea Butter Hair Treatment Mask Nuance Airy
4. Ma Cherie Air Feel Shampoo
5. Asience Shine Therapy Shampoo
6. Mods Hair Glamourous Make
7. VS Moisture Shine Water

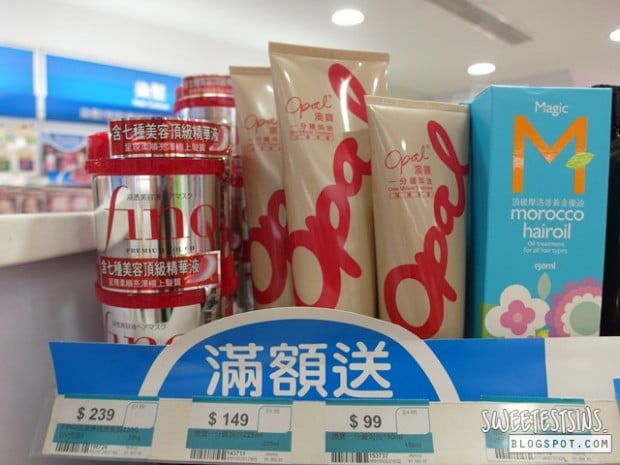
Fino, Opal and Magic

I was really interested in getting Fino premium touch hair essence mask as I was attracted to the fact that it contains 7 different types of beauty essence and it’s by Shiseido. Kinda regretted why I didn’t pick this up now.

I haven’t tried Opal personally but I have tried Magicboo whose formula is provided by Opal. You can read my review on Magicboo here, http://sweetestsins.blogspot.sg/2011/08/korean-beauty-haul-recent-hauls.html

Here’s a little background on Opal. It is Supermodel, Qiqi’s favourite and was recommended on 女人我最大 Nu Ren Wo Zui Da. It is Hong Kong’s no. 1 best-selling product for 6 consecutive years.

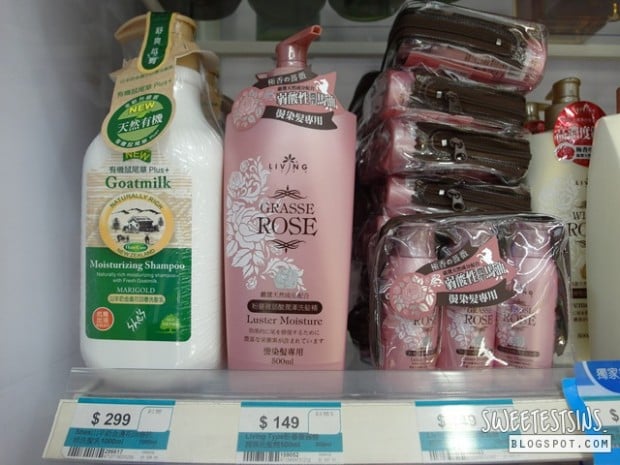
She’s Goat milk shampoo, Living Type Grasse Rose

Wow, I have seen and tried goatmilk shower gel and cream but certainly not goatmilk shampoo! I can imagine how pampering that would be!

Living Type Grass Rose hair products reminds me very much of Kose Happy Bath Day Precious Rose series.

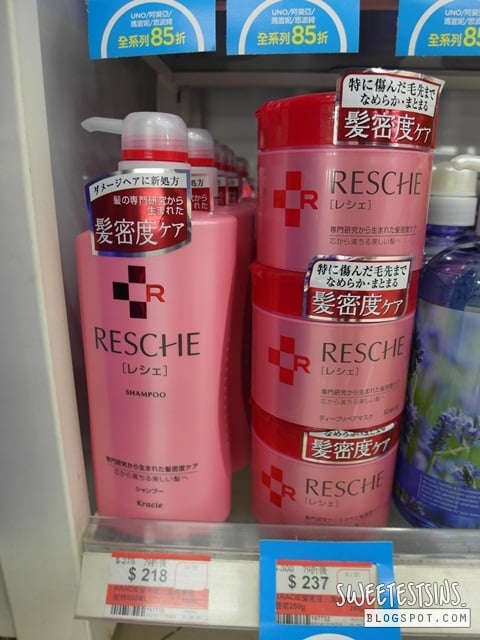
Kracie Resche shampoo and treatment

Kracie Resche hair treatment looks like it’s worth a try too. Ah, why don’t we have more brands in Singapore to choose from in terms of hair products?

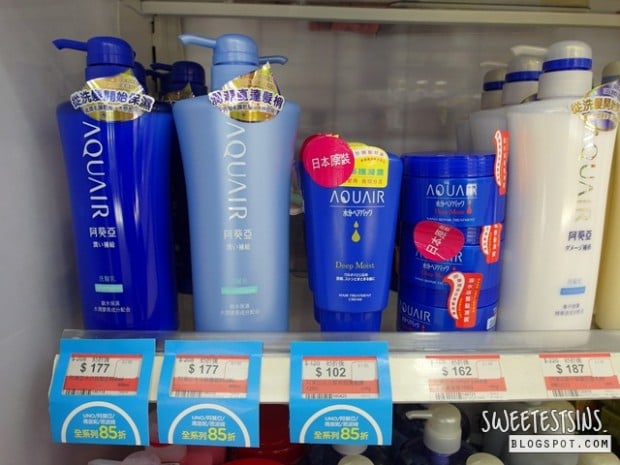
Aquair hair products

Sunflower shampoo

I thought that this sunflower shampoo was rather interesting, no?

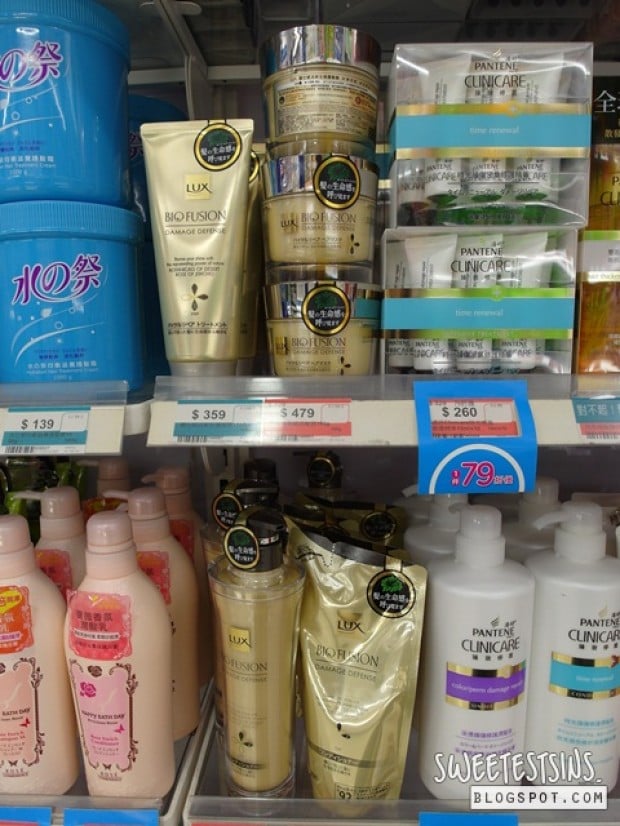
LUX Bio Fusion, Pantene Clinicare, Kose Happy Bath Day hair products

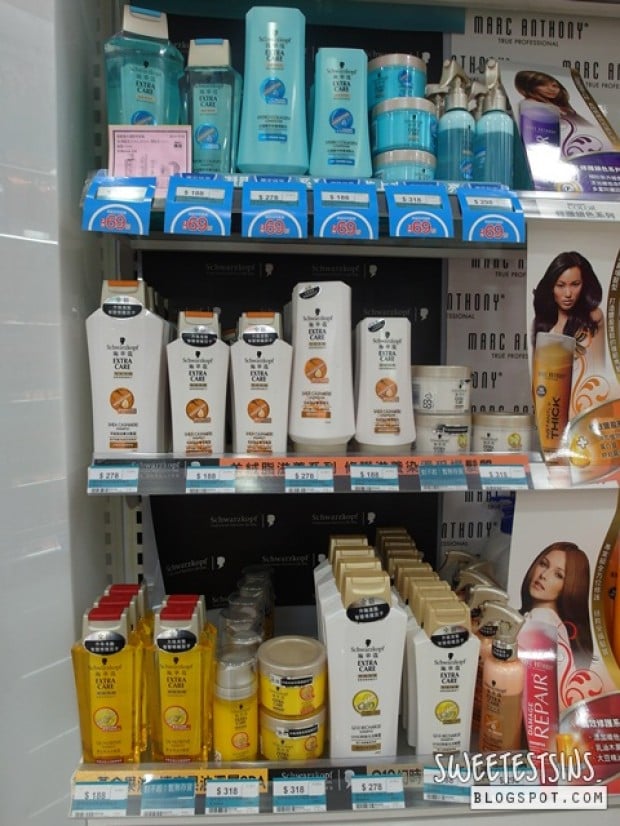
Schwarzkopf hair products

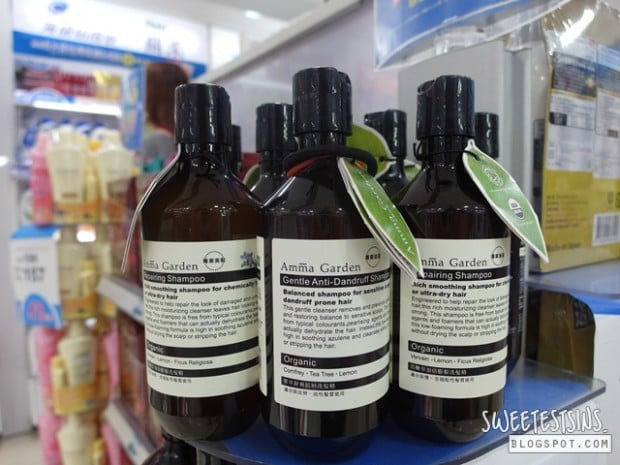
I also came across this organic brand, Amma Garden that has got repairing and anti-dandruff shampoo!

Amma Garden

The packaging of Amma Garden’s products reminds me so much of Sukin! Maybe it’s due to the fact that organic products packaging are all pretty similar?

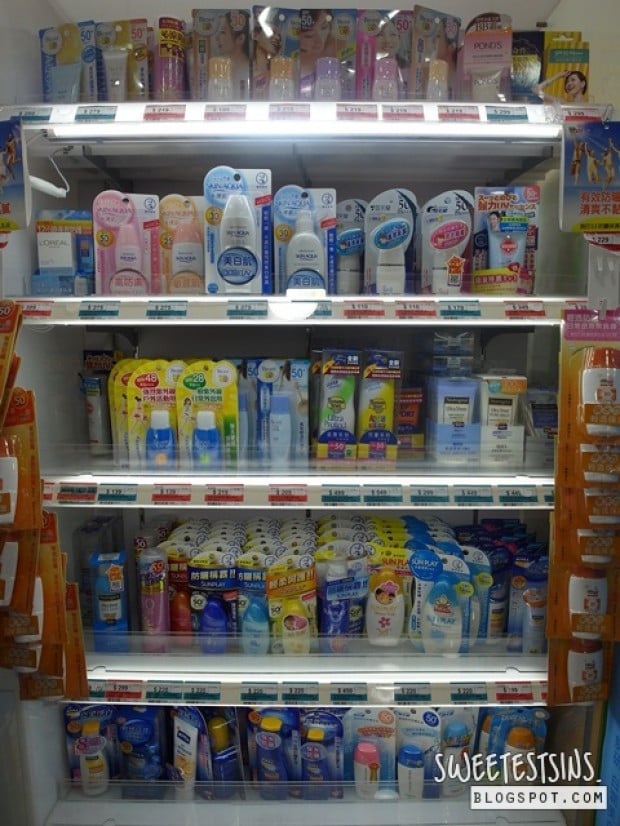
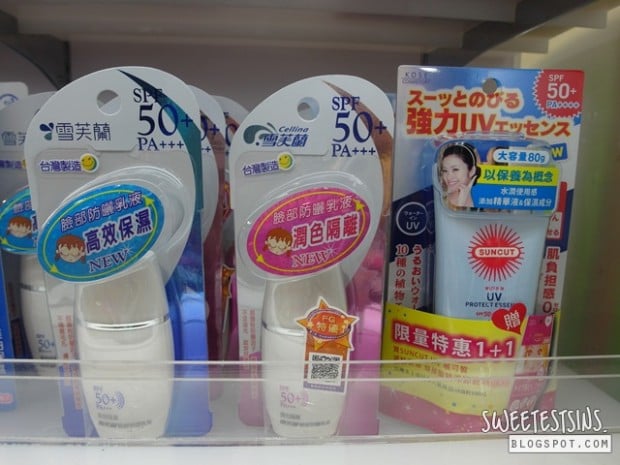
The last section that I checked out was – sunblock and sunscreens. A must-have in Taiwan especially during summer! We all applied and reapplied sunblock religiously every other hour because the sun was scorching hot. Even so, my cousin, Bing and I ended up with watch tan-lines. Eeks, hope it goes away soon because it looks so ugly. T_T

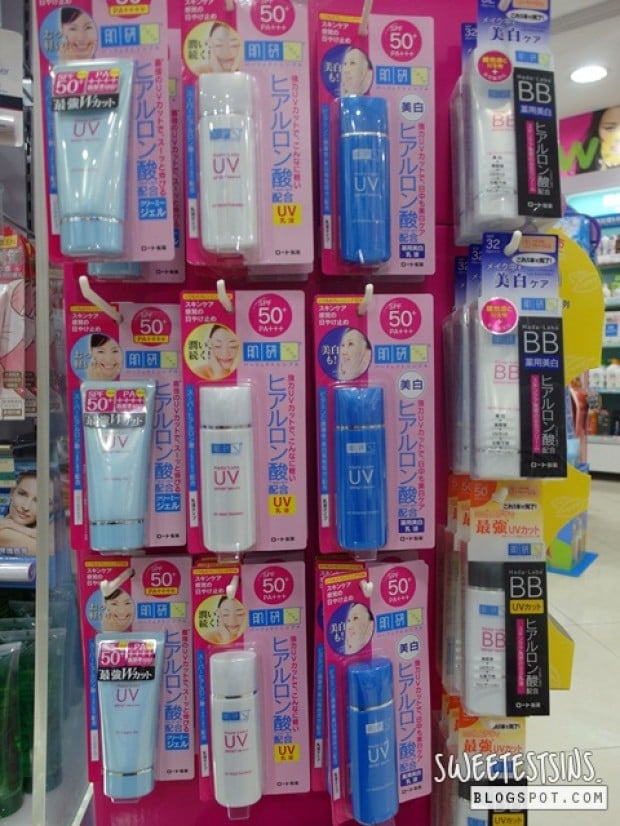
Hada Labo sunscreen

Of all the Hada Labo sunscreens above, I have only tried Hada Labo SHA Moisturizing UV Milk before. You can read my review here, http://sweetestsins.blogspot.sg/2012/05/hada-labo-sha-moisturizing-uv-milk.html.

I tested Hada Labo UV Creamy Gel out and I think the texture feels like Biore UV Aqua Rich Watery Essence.

Biore, Mentholatum Skin Aqua, Nivea and Sunplay sunscreen and sunblock

I spotted my holy grail Biore UV Moist Face milk (purple cap) that has been discontinued in Singapore. To read my reviews on Biore sunscreens, click here.

I also spotted Mentholatum Skin Aqua sunscreens that was recommended by Kevin 凯文老师 on 女人我最大 Nu Ren Wo Zui Da.

Cellina and Kose Cosmeport sunscreen

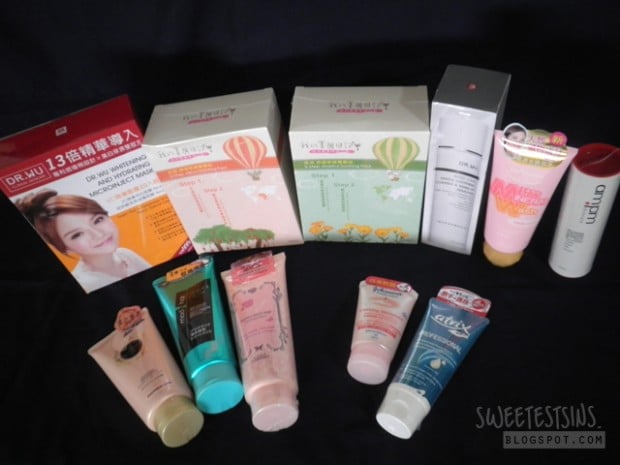
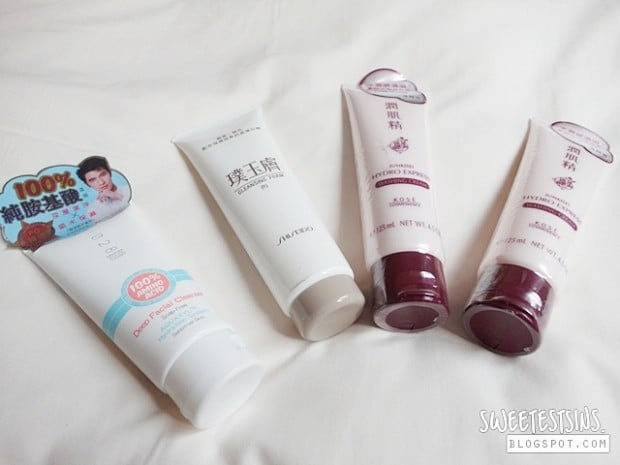
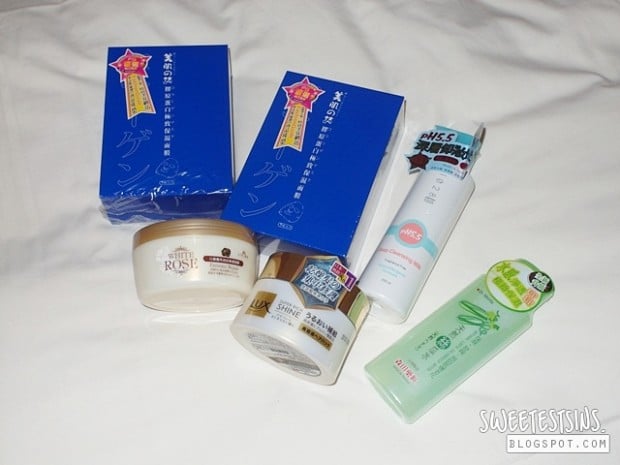
I just realised that I haven’t posted my Taiwan Trip 2012 ‘s Watsons haul. So here’s my Taiwan Taipei Ximending Watsons haul for both last year and this year, 2012 and 2013.

2012:

1. Dr Wu Whitening and Hydrating Microinject Mask
2. My Beauty Diary Africa Hydrating Pack
3. My Beauty Diary 2 step America Soothing Pack
4. Dr Wu Basic Care Gentle Soothing Cleanser & Make Up Remover
5. Kose Softymo Mineral Wash Cleansing Foam (Moisture Rich)
6. ampm Super Triple HA Serum
7. MA CHERIE Air Feel Treatment
8. Mod’s Hair Aqua Clear Treatment
9. Kose Happy Bath Day Precious Rose Rose Enrich Hair Pack
10. Johnson’s Body Care 24hour Moisture Hand Cream
11. Atrix Professional Repair Cream

2013:

1. 1028 Deep Facial Cleanser
2. Shiseido Cleansing Foam
3. Kose Cosmenience Junkisei Hydro Express

In case you are wondering why I got two Kose Cosmenience Junkisei Hydro Express, there was a promotion going on if I were to get two. So they went into my shopping basket anyway.

1. BeautyMate Beautymate Hydro Power Collagen Mask
2. Living Tree White Rose Extreme Repair Hair Mask
3. LUX Super Rich Shine Essence Hair Treatment Mask
4. 1028 Deep Cleansing Milk
5. Dr Morita Natural Luffa Cylindrica Water 森田藥粧 天然絲瓜水

If I’m not wrong, 1028 is 小凯老师 Xiao Kai Lao Shi ‘s brand. My cousin, Lixuan was trying out 1028 Deep Cleansing Milk at Watsons after being drawn to the LCD display that was showing products that 小凯老师 Xiao Kai Lao Shi recommended. She urged us to try. Being a fan of cleansing water, I was quite hesitant initially but upon trying, all of us – Bing, Siling, myself and Xuan included all grabbed a bottle. Although it says cleansing milk, the texture is somewhat in between cleansing water and cleansing serum.

I hope you will love this entry as much as I enjoyed re-visiting Watsons Ximending again, only that it’s virtually this time round. I already made plans as to what I want to purchase in the future if I were to go back to Taiwan again.

Love,
Patricia

Also read: Cult Beauty Brands You Must Buy While Travelling Asia

Contributed by SweetestSins.

Thursday, October 5, 2017

Rimless Toilet Market in the UK - Top Trends and Opportunity Analysis by Technavio

Read article : Rimless Toilet Market in the UK - Top Trends and Opportunity Analysis by Technavio

LONDON--(BUSINESS WIRE)--Technavio’s latest market research report on the rimless toilet market in the UKprovides an analysis of the most important trends expected to impact the market outlook from 2017-2021. Technaviodefines an emerging trend as a factor that has the potential to significantly impact the market and contribute to its growth or decline.

According to Anju Ajaykumara lead analyst at Technavio for construction research, “Rimless toilets are a relatively innovation in the sanitary ware market. These products are designed primarily to improve hygiene and save water, especially in places where the toilet-use frequency is higher, and water conservation is essential while maintaining hygiene within the acceptable standards. The market is likely to witness strong demand from the commercial or non-residential segment such as malls and offices.”

This report is available at a USD 1,000 discount for a limited time only: View market snapshot before purchasing

Buy 1 Technavio report and get the second for 50% off. Buy 2 Technavio reports and get the third for free.

The top three emerging market trends driving the rimless toilet market in the UK according to Technavio research analysts are:

Looking for more information on this market?Request a free sample report

Technavio’s sample reports are free of charge and contain multiple sections of the report including the market size and forecast, drivers, challenges, trends, and more.

High-tech toilets gaining popularity

High-tech toilets are technology-enabled toilets. These high-tech or smart toilets have a wide range of features and signal a paradigm shift in the way bathrooms are perceived. Smart toilets were pioneered in Japan, where the market penetration is high. The use of smart toilets is increasing in the US and Europe. These toilets are replete with self-indulgent features, such as built-in bidets, heated seats, and lids that are raised automatically. These toilets can be connected to the smartphones as well.

Smart toilets can be intimidating for first-time users, as they offer features such as motion sensors, bidets, along with dual-flushing systems and various temperature settings, which can dazzle even the most proficient user of modern technology. But, once an individual gets acquainted with them, using the features becomes easier.

Growth in water saving technologies

The rise in global population has substantially increased the demand for water, which is leading to the depletion of the critical water resources. The flushing systems of toilets account for one-third of a building's total water consumption. Various technologies have been introduced to tackle the problem of water wastage by reducing the water consumption, especially in toilets.

The two popular technologies that are available for use in residential and commercial buildings are gravity flow toilets and pressure-assisted toilets. Pressure-assisted toilets use pressurized air inside the tank to provide an additional force for rinsing. Gravity flow toilets have a vertical rim-free bowl design, which accelerates the water as it moves toward the bottom of the bowl. Pressure-assisted toilets, although more efficient, are noisier and more expensive than gravity flow toilets. Over time, various vendors in the global toilet market have produced innovative products that focus on saving water.

Growth of ultra-modern bathroom concepts

Rimless toilets, along with shower and other bathroom essentials, are increasingly used in ultra-modern bathroom concepts. The bathroom concept is an architectural design customized to suit individual preferences. For some, a bathroom is a place to take a momentary break from the commotion and stress of modern life. Although the basic purpose of a bathroom remains the same, its use has widened to adapt to ever-evolving modern lifestyles.

“One of the key requirements for the luxury bathroom concept is hygiene and cleanliness. Rimless toilets are the perfect WCs that are not only hygienic but also require less cleaning. Apart from this, the toilets provide an aesthetic look to the environment by complimenting the overall décor of the bathroom,”says Anju.

Browse Related Reports:

About Technavio

Technavio is a leading global technology research and advisory company. Their research and analysis focuses on emerging market trends and provides actionable insights to help businesses identify market opportunities and develop effective strategies to optimize their market positions.

With over 500 specialized analysts, Technavio’s report library consists of more than 10,000 reports and counting, covering 800 technologies, spanning across 50 countries. Their client base consists of enterprises of all sizes, including more than 100 Fortune 500 companies. This growing client base relies on Technavio’s comprehensive coverage, extensive research, and actionable market insights to identify opportunities in existing and potential markets and assess their competitive positions within changing market scenarios.

If you are interested in more information, please contact our media team at media@technavio.com.

Sunday, July 30, 2017

Norcros PLC Interim Results - ADVFN

Read article : Norcros PLC Interim Results - ADVFN
Norcros (LSE:NXR)
Historical Stock Chart 2 Years : From Oct 2015 to Oct 2017 Click Here for more Norcros Charts. TIDMNXR RNS Number : 4598F Norcros PLC 12 November 2015 12 November 2015 Norcros plc Results for the six months ended 30 September 2015 'Strong momentum within our businesses' Norcros, the market leading supplier of innovative branded showers, taps, bathroom accessories, tiles and adhesives, today announces its results for the six months ended 30 September 2015. Financial Summary 2015 2014 % change % change as reported at constant currency ----------------------- ---------- ---------- ------------- ------------- Revenue GBP118.7m GBP108.6m +9.3% +12.0% ----------------------- ---------- ---------- ------------- ------------- Underlying* operating profit GBP9.9m GBP7.4m +34% ----------------------- ---------- ---------- ------------- ------------- Underlying* profit before tax GBP9.4m GBP6.7m +40% ----------------------- ---------- ---------- ------------- ------------- Profit before tax GBP7.0m GBP6.3m +11% ----------------------- ---------- ---------- ------------- ------------- Underlying operating cash flow** GBP13.3m GBP11.6m +15% ----------------------- ---------- ---------- ------------- ------------- Diluted underlying EPS * 11.8p 8.1p +46% ----------------------- ---------- ---------- ------------- ------------- Net debt GBP29.2m GBP20.0m ----------------------- ---------- ---------- ------------- ------------- Interim dividend per share 2.2p 1.85p +19% ----------------------- ---------- ---------- ------------- ------------- * Underlying is before IAS 19R administrative expenses, acquisition related costs and exceptional operating items and, where relevant, before non-cash finance costs ** Underlying operating cash flow means cash generated from continuing operations before exceptional cash flows and pension fund deficit recovery contributions Restated for the 10:1 share consolidation completed on 29 September 2015 Highlights -- Strong first half performance -- Revenue increased by 12.0% on a constant currency basis -- Underlying operating profit increased by 34% to GBP9.9m -- Underlying profit before tax increased by 40% to GBP9.4m -- Profit before tax increased by 11% to GBP7.0m -- Continued strong underlying operating cash generation: 104% of underlying EBITDA -- Acquisition of Croydex completed on 25 June 2015 -- Diluted underlying earnings per share 46% higher at 11.8p -- Interim dividend increased by 19% to 2.2p per share Martin Towers, Chairman, commented: "I am pleased to announce a strong set of results for the six months ended 30 September 2015. Not only has the Group continued to make excellent progress in its existing businesses, but it has continued to advance towards its strategic targets with the acquisition of Croydex at the end of June 2015. With our strong brands, leading market positions and continued self-help initiatives focused on market share gain the Group is well positioned to make further progress. Given the strong first half performance and momentum within our businesses, the Board now expects the Group to achieve underlying operating profit marginally ahead of market expectations for the year to 31 March 2016." There will be a presentation today at 9.30 am for analysts at the offices of Hudson Sandler, 29 Cloth Fair, London, EC1A 7NN. The supporting slides will be available on the Norcros website at http://www.norcros.com later in the day. ENQUIRIES Norcros plc Tel: 01625 547700 Nick Kelsall, Group Chief Executive Martin Payne, Group Finance Director Hudson Sandler Tel: 0207 796 4133 Nick Lyon Charlie Jack Katie Matthews Notes to Editors -- Norcros is a leading supplier of high quality and innovative showers, taps, bathroom accessories, ceramic wall and floor tiles and adhesive products with operations primarily in the UK and South Africa. -- Based in the UK, Norcros operates under five brands: - Triton Showers - Market leader in the manufacture and marketing of showers in the UK - Vado - A leading manufacturer and supplier of taps, mixer showers, bathroom accessories and valves - Croydex - A market-leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories - Johnson Tiles - A leading manufacturer and supplier of ceramic tiles in the UK - Norcros Adhesives - Manufacturer of tile & stone adhesives, grouts and related products -- Based in South Africa, Norcros operates under three brands: - Tile Africa - Chain of retail stores focused on ceramic and porcelain tiles, and associated products such as sanitary ware, showers and adhesives - Johnson Tiles South Africa - Manufacturer of ceramic and porcelain tiles - TAL - The leading manufacturer of ceramic and building adhesives -- Norcros is headquartered in Wilmslow, Cheshire and employs around 1800 people. The Company is listed on the London Stock Exchange. For further information please visit the Company website: http://www.norcros.com/ Chairman's statement I am pleased to announce a strong set of results for the six months ended 30 September 2015. Not only has the Group continued to make excellent progress in its existing businesses, but it has continued to advance towards its strategic targets with the acquisition of Croydex at the end of June 2015. Market conditions in the UK continue to be mixed, with the trade sector continuing to perform well driven by new house build and commercial specifications, although RMI driven demand is muted and retail markets generally remain challenging. In South Africa, market conditions have been impacted by the recent slow-down in China affecting the commodity sector which is a significant part of the South African economy. However, the strong self-help culture evident in all our businesses has continued to offset these challenges and has been a key factor in delivering these strong results. Underlying operating profit rose by 34% to GBP9.9m (2014: GBP7.4m) representing an improved margin of 8.3% (2014: 6.8%). UK performance benefitted from the return to profitability of Johnson Tiles UK following its manufacturing inefficiencies in the prior year and the three month contribution from Croydex. South Africa nearly doubled its underlying operating profit despite a weaker Rand, driven by strong constant currency revenue growth and an improvement in underlying profit performance in all three businesses including a return to profitability at Johnson Tiles South Africa. Through a combination of strong underlying EBITDA and continued prudent management of working capital, underlying operating cash generation was GBP13.3m (2014: GBP11.6m), representing 104% of underlying EBITDA (2014: 112%). This performance and a cash outflow of GBP20.1m relating to the acquisition of Croydex left net debt at GBP29.2m compared to GBP14.2m at 31 March 2015 and represents leverage of 1.1 times underlying proforma EBITDA. Acquisition of Croydex As previously announced, the Group acquired 100% of the ordinary share capital of Croydex Group Limited ("Croydex"), a market leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories, on 25 June 2015. The acquisition of Croydex is an important next step in the Group's growth strategy to increase revenue to GBP420m by 2018 and follows on from the very successful integration of the Vado business which Norcros acquired in March 2013. The addition of the Croydex business to the Group's existing portfolio has increased the breadth of our product range in the bathroom segment and has enabled the Group to offer an even broader array of complementary bathroom products to our customers. Croydex will also benefit from the global distribution channels, sourcing skills and strong financial position of the enlarged Group. I am excited by the prospects for Croydex within the Norcros Group and have been impressed by the energy and enthusiasm of its management and employees. Results Revenue for the six month period to 30 September 2015 at GBP118.7m (2014: GBP108.6m) was 12.0% higher on a constant currency basis compared to the prior year, and 9.3% on a Sterling reported basis. Of this growth, 5.5% was attributable to a three month contribution from Croydex. On a like for like basis excluding Croydex, constant currency growth was 6.5% and 4.0% on a Sterling reported basis. Underlying operating profit rose by 34% to GBP9.9m (2014: GBP7.4m) reflecting improvements in both the UK and South Africa together with a three month contribution from Croydex. Underlying profit before taxation increased by 40% to GBP9.4m (2014: GBP6.7m) reflecting the higher underlying operating profit and lower interest costs driven by improved margins offset by increased borrowings due to the acquisition of Croydex in June 2015. Profit before taxation for the period was GBP7.0m (2014: GBP6.3m), reflecting increased underlying profit before taxation, higher exceptional operating income of GBP2.3m (2014: GBP0.3m) primarily as a result of settlement in the period of a contractual dispute with Morrisons relating to a previous agreement to sell them freehold land in Tunstall, Stoke on Trent, offset by higher non-underlying interest of GBP1.3m (2014: income of GBP0.6m) and higher acquisition related costs of GBP2.6m (2014: GBP0.5m) relating to the final year of the Vado earn out mechanism of GBP1.3m and the costs of acquiring Croydex of GBP0.8m. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Diluted underlying earnings per share were 46% higher at 11.8p (2014: 8.1p restated for the 10:1 share consolidation), reflecting improved underlying earnings. Financial We have continued to demonstrate strong cash conversion with underlying operating cash generated in the period at GBP13.3m (2014: GBP11.6m), representing 104% of underlying EBITDA for the period (2014: 112%). There was a working capital outflow of GBP0.2m in the period which compared to a GBP0.6m inflow in the prior period. A pension deficit recovery payment of GBP1.1m (2014: GBP1.0m) in the period (as part of the GBP2.0m plus CPI per annum contribution agreed with the Trustee in 2013) and cash inflows relating to exceptional items of GBP0.7m (2014: outflows of GBP0.7m) resulted in net cash generated from continuing operations at GBP12.9m (2014: GBP9.9m). Investment in capital expenditure in the period amounted to GBP3.2m (2014: GBP3.4m) and has remained consistent at 1.1 times depreciation. Net debt increased in the six months to 30 September 2015 by GBP15.0m to GBP29.2m principally as a result of the acquisition of Croydex, which, including costs related to the acquisition of GBP0.8m, resulted in a net cash outflow in the period of GBP20.1m. The gross deficit relating to our UK defined benefit pension scheme as calculated under IAS 19R has improved slightly from a deficit of GBP44.3m at 31 March 2015 to a deficit of GBP42.4m at 30 September 2015. The reduction in the deficit principally reflects an increase in the discount rate to 3.8% net of a lower return on scheme assets. During the previous year the plan undertook a number of liability management exercises which resulted in the recognition of a net settlement gain of GBP1.7m. A further gain of GBP0.4m has been recognised in the period as a result of these exercises which has been included within exceptional operating items. Property As highlighted in the Group's 2015 Annual Report, the contractual dispute arising from the conditional sale of part of the surplus land in Tunstall to a subsidiary of Wm Morrison Supermarkets plc was settled on 15 May 2015. The Company has recognised exceptional operating income of GBP1.9m in relation to this settlement. Dividend The Board is declaring an interim dividend of 2.20p per share reflecting the strong first half performance and its confidence in the Group's future prospects. Taking into account the 10:1 share consolidation which took place on 29 September 2015, this represents an increase of 19% over the restated interim dividend from the previous year of 1.85p per ordinary share. The dividend is payable on 7 January 2016 to shareholders on the register on 4 December 2015. The shares will be quoted as ex-dividend on 3 December 2015. Operating review UK For the six months ended 30 September 2015 total revenue in our UK businesses was 9.8% ahead of the prior period at GBP79.9m (2014: GBP72.8m). On a like for like basis excluding Croydex revenue of GBP5.8m, total revenue increased by 1.8%. Underlying operating profit at GBP8.0m was 25% higher than last year at GBP6.4m and represents an improved return on sales of 10.0% (2014: 8.8%). The trends in our UK markets seen in the prior year have continued into the first half of this year, with good growth in the trade sector, but a challenging retail sector. Triton Our market leading shower operation, Triton Showers, recorded revenue growth of 3.1% for the six month period to 30 September 2015 to GBP26.2m (2014: GBP25.4m). UK revenue for Triton was 1.9% higher than the prior year. Revenue from the UK trade sector increased by 3.3% compared to the prior year, with strong trading across major national merchants and electrical wholesale customers and a much improved performance in the specification sector, which has been a key area of focus for the business. The retail sector however remains challenging, principally due to weak consumer demand and the impact of product range changes at some of the major DIY accounts. Notwithstanding this, Triton still delivered marginally higher retail revenue compared to the previous year. Triton has continued to invest significantly in new product development and in product innovation with the recent launch of the T80ZFF thermostatic electric shower range which further strengthens our offer in the growing thermostatic shower market. Export markets account for 17% of Triton's overall revenue and have continued to grow, increasing by 10.0% compared to the prior year. The principal export market for Triton is Ireland, where a revitalised new build and RMI sector has helped drive revenue growth. Markets further afield, principally Latin America, continue to be developed. We have invested in both new product development and marketing including representation at a number of major trade fairs in the region. Triton has continued to generate strong cashflows and delivered underlying operating profits which were marginally ahead of last year. Vado Our leading manufacturer of taps, mixer showers, bathroom accessories and valves, Vado, recorded revenue of GBP15.9m for the period (2014: GBP14.8m), 7.4% higher than the prior year. UK revenue was 16.7% higher than the prior year, with growth in both the retail and trade segments. In the trade sector, we continue to make strong progress in both residential and commercial specifications, benefitting particularly from increased new private housing programmes. In retail, we are beginning to see the benefits of investing in the expansion of the sales team and were recently recognised as tap brand of the year by BKU magazine in its inaugural awards. Export revenue, which accounts for approximately 30% of Vado revenue, was 9.6% lower than the same period last year. This performance reflects a mixed picture with lower revenue outside of our major Middle East market held back by credit issues with a number of sub-Saharan customers and a number of larger projects last year not being repeated this year. However, in the Middle East we grew revenue strongly in the first half of this year reflecting more buoyant construction activity. We have recently increased our presence in this market and established a directly employed resource in the region to strengthen the Vado brand in the important specification sector. Underlying operating profits were ahead of the same period last year driven largely by revenue growth. Croydex Croydex, our market-leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories, which was acquired on 25 June 2015, recorded revenue of GBP5.8m for the three month period since acquisition to 30 September 2015, in line with our expectations. Whilst it was not under Group ownership for the full period, revenue for the six months ended 30 September 2015 was GBP10.9m, 3.7% higher than the prior year. UK sales at GBP10.3m were in line with the prior year with the challenging retail environment being offset by growth in the trade sector. Export sales of GBP0.6m were GBP0.4m higher than the prior period, reflecting the additional focus employed to target growth outside the UK, with particular success being achieved in Germany. Operationally, Croydex has been integrated into the Norcros group seamlessly, and the performance of the business since acquisition has been highly encouraging, with the business generating an underlying profit performance in line with the Board's expectations. Johnson Tiles Our UK market leading ceramic tile manufacturer and a market leader in the supply of both own manufactured and imported tiles, Johnson Tiles, recorded revenue 4.5% lower than the same period last year at GBP27.9m (2014: GBP29.2m). UK revenue was 2.7% lower than the comparative period last year. Excellent progress continues to be made in the trade segment with revenue 5.0% higher, notwithstanding that last year included the one-off benefit of the supply of ceramic poppies which formed the main part of the World War I commemorations at the Tower of London. Again, good progress has been made in the specification sector, with projects completed in the period for Holiday Inn and Total Fitness. In the retail sector, subdued demand in the DIY sector generally combined with the withdrawal from some unprofitable ranges resulted in revenues 9.6% lower than the prior year. Export revenue was also 16.7% lower than the prior year principally reflecting the combined impact of weak market conditions in France and credit issues in the Middle East. Operationally, the excellent progress made at the end of the last financial year has been sustained throughout this first half period. As a result of management actions manufacturing efficiencies have significantly improved compared to the prior period. This, together with the continued trade revenue growth, have been key factors in delivering a solid underlying operating profit performance for the period, a marked improvement over the small operating loss recorded in the prior period. Norcros Adhesives Norcros Adhesives, our manufacturer and supplier of tile and stone adhesives and ancillary products, once again demonstrated excellent growth with revenue 20.6% higher at GBP4.1m (2014: GBP3.4m). This performance principally reflects further development of our distribution channels in the trade segment, as well as some initial success in the retail DIY sector. The business continues to develop innovative new products to address the technical issues in fixing tiles to different types of substrate, for example the launch of the Ultima8 B+ range, which solves the problem of fixing tiles to bituminous surfaces. Additionally, the business has continued to invest in future growth, achieving the ISO 14001 accreditation for environmental management, commencing the construction of a new training centre and laboratory in the UK and establishing a local presence in the Middle East to better capitalise on the opportunities in the significant specification market in this region. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) This continued strong growth has delivered an underlying operating profit performance ahead of the same period last year. South Africa Once again our South African businesses reported another period of double digit constant currency growth resulting in revenue 16.9% higher than prior year on a constant currency basis. Reported Sterling revenue was 8.4% higher at GBP38.8m (2014: GBP35.8m), reflecting an 8% weaker Rand. Underlying operating profit at GBP1.9m was 90% higher than the previous period (2014: GBP1.0m) despite the weaker Rand adversely impacting reported profits by GBP0.1m. This represents a significantly improved return on sales of 4.9% (2014: 2.7%). All three businesses delivered an improvement in local currency underlying operating profit performance. Our South African operations have made further progress in the first half of the year with all three businesses growing ahead of the market as we continue to implement our strategy of growing our brands through geographic expansion and range diversification. Gross margins improved against the previous year, with the benefits in our supply chain and production efficiencies delivering tangible benefits over the period. Johnson Tiles South Africa Our tile manufacturing business, Johnson Tiles South Africa, achieved independent sector revenue of GBP5.4m (2014: GBP5.2m), 12.5% higher than prior year on a constant currency basis, and 3.8% higher on a reported Sterling basis. Following the investment in two inkjet printers over the last two years we have successfully enriched our product offer with the launch of a number of additional inkjet ranges and a new rectangular product format in response to market trends. An improved product offer and a consistent manufacturing performance have resulted in a marked improvement in performance. As reported in our last annual report, Johnson Tiles South Africa experienced some manufacturing disruption as a result of the national electricity load-shedding programme. Consequently a new standby diesel generator has been successfully installed in the period which will significantly reduce the impact of being unable to operate the manufacturing facility in the event of a power outage. Notwithstanding the disruption from load shedding prior to the generator being installed, the business delivered an underlying operating profit compared to a small underlying operating loss in the prior period. TAL Our market leading adhesive business, TAL, delivered constant currency independent sector revenue growth of 20.5% in the period, or an 11.9% increase on a Sterling reported basis to GBP9.4m (2014: GBP8.4m). This growth was achieved through market share gain in domestic markets and through continued focus on growing sub-Saharan export markets, as well as product range extensions, such as a new 2kg bag to its grout range and a new powdered bond range, both of which have received a favourable market reaction. In addition to the considerable growth in revenue, we have continued to drive profitability through further improvements in plant and procurement efficiencies. This has been reflected in a stronger underlying operating profit performance than the prior year. Tile Africa Revenue at our leading retailer of wall and floor tiles, adhesives, showers, sanitaryware and bathroom fittings, Tile Africa, increased by 16.5% on a constant currency basis compared to the prior year, and by 8.1% on a Sterling reported basis to GBP24.0m (2014: GBP22.2m). Tile Africa currently operates from 29 stores and four franchises, with a new store in Boksburg, Gauteng, expected to open by the end of this financial year. The new CX format stores that we developed to improve the overall retail customer experience, and were showcased in the last Annual Report, have continued to perform strongly, and consequently there are plans to retrofit this format into further stores. The store at Lenasia has recently been refitted as a factory outlet aimed at the emerging consumer segments following on from the positive results achieved at the existing store of this type in Silverton. The improved CX store layout, together with benefits from our increased focus on in-stock and on-display offering has been reflected in market share gain and revenue growth, and in an improved underlying operating profit compared to the prior year. Share consolidation On 29 September 2015 the Company undertook an exercise to consolidate its existing 1p ordinary shares into new 10p ordinary shares, and the new shares began to be traded on the London Stock Exchange on 30 September. The resolution permitting the Board to effect the consolidation had been passed at the Company's AGM on 22 July. The Board considered it was important to reduce the number of shares in issue to a level more appropriate for a company of Norcros's size, and to make the shares more attractive to investors, whilst having no effect on the relative holdings of individual shareholders. Full details of the share consolidation are provided on the Company's website www.norcros.com. Summary and outlook The Group has made a very pleasing start to the year, with each of our businesses delivering an improvement in underlying operating profit performance. As I have already highlighted, we took decisive management action in our tiles businesses in both the UK and South Africa to address the operational challenges of recent years and now have a much stronger base from which to develop our medium term growth plans. Whilst conditions in our UK retail and export markets remain testing, we continue to capitalise on the demand opportunities in the more positive trade sector where we continue to perform strongly. The acquisition of the Croydex business is a further step in realising our strategic target of generating revenues of GBP420m by 2018 and importantly the business has already been smoothly integrated into the Group. With our strong brands, leading market positions and continued self-help initiatives focused on market share gain the Group is well positioned to make further progress. Given the strong first half performance and momentum within our businesses, the Board now expects the Group to achieve underlying operating profit marginally ahead of market expectations for the year to 31 March 2016. M. G. Towers Chairman 12 November 2015 Condensed consolidated income statement Six months to 30 September 2015 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014* 2015* (unaudited) (unaudited) (audited) Notes GBPm GBPm GBPm ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Continuing operations Revenue 118.7 108.6 222.1 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Underlying operating profit 9.9 7.4 17.0 IAS 19R administrative expenses (0.8) (0.8) (1.7) Acquisition related costs 4 (2.6) (0.5) (2.2) Exceptional operating items 4 2.3 0.3 (2.5) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Operating profit 8.8 6.4 10.6 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Finance costs 7 (1.1) (0.8) (1.4) Exceptional finance costs 7 - (0.4) (0.4) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Total finance costs 7 (1.1) (1.2) (1.8) Finance income 7 - 1.6 3.3 IAS 19R finance cost (0.7) (0.5) (1.1) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit before taxation 7.0 6.3 11.0 Taxation 6 (1.6) (1.6) (2.9) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit for the period from continuing operations 5.4 4.7 8.1 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit for the period from discontinued operations - 0.1 0.1 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit for the period 5.4 4.8 8.2 (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Earnings per share attributable to the owners of the Company Basic earnings per share: From continuing operations 5 9.0p 8.0p 13.6p From discontinued operations 5 - 0.2p 0.2p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- From profit for the period 5 9.0p 8.2p 13.8p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Diluted earnings per share: From continuing operations 5 8.7p 7.7p 13.1p From discontinued operations 5 - 0.2p 0.2p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- From profit for the period 5 8.7p 7.9p 13.3p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Weighted average number of shares for basic earnings per share (millions) 5 60.1 59.0 59.2 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Non-GAAP measures Underlying profit before taxation (GBPm) 3 9.4 6.7 15.8 Underlying earnings (GBPm) 3 7.3 5.0 13.0 Basic underlying earnings per share 5 12.2p 8.4p 21.9p Diluted underlying earnings per share 5 11.8p 8.1p 21.1p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- * The results of previous periods have been restated where required to reflect the revised presentation of acquisition related costs and the 10:1 share consolidation completed on 29 September 2015. Condensed consolidated statement of comprehensive income Six months to 30 September 2015 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------------------------------------------- ------------ ------------ ---------- Profit for the period 5.4 4.8 8.2 -------------------------------------------------------------------------- ------------ ------------ ---------- Other comprehensive income and expense: Items that will not subsequently be reclassified to the income statement Actuarial gains/(losses) on retirement benefit obligations 1.6 (14.8) (18.8) Items that may be subsequently reclassified to the income statement Foreign currency translation adjustments (6.0) (1.2) (0.6) -------------------------------------------------------------------------- ------------ ------------ ---------- Other comprehensive expense for the period (4.4) (16.0) (19.4) -------------------------------------------------------------------------- ------------ ------------ ---------- Total comprehensive income/(expense) for the period 1.0 (11.2) (11.2) -------------------------------------------------------------------------- ------------ ------------ ---------- Attributable to equity shareholders arising from Continuing operations 1.0 (11.4) (11.4) Discontinued operations - 0.2 0.2 -------------------------------------------------------------------------- ------------ ------------ ---------- 1.0 (11.2) (11.2) ------------------------------------------------------------------------- ------------ ------------ ---------- Items in the statement are disclosed net of tax. Condensed consolidated balance sheet At 30 September 2015 At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) Notes GBPm GBPm GBPm -------------------------------------- ----- ------------ ------------ --------- Non-current assets Goodwill 29.5 22.0 22.2 Intangible assets 12.2 4.8 4.7 Property, plant and equipment 37.5 36.8 37.6 Investment properties - 4.3 - Derivative financial instruments 15 - 0.2 - Deferred tax assets 6 11.2 14.1 13.8 -------------------------------------- ----- ------------ ------------ --------- 90.4 82.2 78.3 -------------------------------------- ----- ------------ ------------ --------- Current assets Inventories 56.3 51.0 52.2 Trade and other receivables 43.6 42.1 40.5 Derivative financial instruments 15 1.0 - 2.1 Cash and cash equivalents 7.8 4.5 5.6 108.7 97.6 100.4 -------------------------------------- ----- ------------ ------------ --------- Current liabilities Trade and other liabilities (60.5) (54.1) (54.9) Derivative financial instruments 15 (0.3) (0.8) (1.0) Current tax liabilities (1.4) (1.7) (1.3) Financial liabilities - borrowings 8 (4.5) (4.1) (1.4) (66.7) (60.7) (58.6) -------------------------------------- ----- ------------ ------------ --------- Net current assets 42.0 36.9 41.8 -------------------------------------- ----- ------------ ------------ --------- Total assets less current liabilities 132.4 119.1 120.1 -------------------------------------- ----- ------------ ------------ --------- Non-current liabilities Financial liabilities - borrowings 8 (32.5) (20.4) (18.4) Pension scheme liability 12 (42.4) (40.6) (44.3) Other non-current liabilities (2.1) (1.5) (1.4) Provisions (3.2) (3.7) (3.3) -------------------------------------- ----- ------------ ------------ --------- (80.2) (66.2) (67.4) -------------------------------------- ----- ------------ ------------ --------- Net assets 52.2 52.9 52.7 -------------------------------------- ----- ------------ ------------ --------- Financed by: Ordinary share capital 9 6.1 5.9 6.0 Share premium 1.0 0.9 1.0 Retained earnings and other reserves 45.1 46.1 45.7 -------------------------------------- ----- ------------ ------------ --------- Total equity 52.2 52.9 52.7 -------------------------------------- ----- ------------ ------------ --------- Condensed consolidated statement of cash flow (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Six months to 30 September 2015 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) Notes GBPm GBPm GBPm ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash generated from operations 10 12.9 10.0 16.2 Income taxes paid (0.6) (0.2) (0.5) Interest paid (0.5) (0.7) (1.3) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net cash generated from operating activities 11.8 9.1 14.4 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash flows from investing activities Proceeds from sale of investment property - - 6.1 Proceeds from sale of property, plant and equipment - 0.4 0.4 Purchase of investment property - - (0.9) Purchase of property, plant and equipment (3.2) (3.4) (7.0) Acquisition of subsidiary undertakings net of cash acquired (20.5) (0.3) (0.5) Disposal of subsidiary undertakings net of cash divested - 3.8 3.8 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net cash (used in)/generated from investing activities (23.7) 0.5 1.9 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash flows from financing activities Net proceeds from issue of ordinary share capital - - 0.2 Drawdown/(repayment) of borrowings 14.0 (10.1) (12.1) Costs of raising debt finance - (0.7) (0.7) Dividends paid to equity shareholders (2.2) (2.0) (3.1) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net cash generated from/(used in) financing activities 11.8 (12.8) (15.7) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net (decrease)/increase in cash at bank and in hand and bank overdrafts (0.1) (3.2) 0.6 Cash at bank and in hand and bank overdrafts at beginning of the period 4.2 3.7 3.7 Exchange movements on cash and bank overdrafts (0.8) (0.1) (0.1) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash at bank and in hand and bank overdrafts at end of the period 3.3 0.4 4.2 ------------------------------------------------------------------------------ ------------ ------------ ---------- Non-GAAP measures Underlying operating cash flow 3 13.3 11.6 22.9 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Condensed consolidated statements of changes in equity Six months to 30 September 2015 (unaudited) Ordinary Retained share Share Treasury Translation earnings/ capital premium reserve reserve (losses) Total GBPm GBPm GBPm GBPm GBPm GBPm ------------------------------------------------- -------- ------- -------- ----------- --------- ----- At 31 March 2015 6.0 1.0 (0.1) (9.1) 54.9 52.7 Comprehensive income: Profit for the period - - - - 5.4 5.4 Actuarial gain on retirement benefit obligations - - - - 1.6 1.6 Other comprehensive expense: Foreign currency translation adjustments - - - (6.0) - (6.0) Total other comprehensive (expense)/ income - - - (6.0) 7.0 1.0 ------------------------------------------------- -------- ------- -------- ----------- --------- ----- Transactions with owners: Dividends paid - - - - (2.2) (2.2) Share option schemes and warrants 0.1 - (0.1) - 0.7 0.7 ------------------------------------------------- -------- ------- -------- ----------- --------- ----- At 30 September 2015 6.1 1.0 (0.2) (15.1) 60.4 52.2 ------------------------------------------------- -------- ------- -------- ----------- --------- ----- Six months to 30 September 2014 (unaudited) Ordinary Retained share Share Treasury Translation earnings/ capital premium reserve reserve (losses) Total GBPm GBPm GBPm GBPm GBPm GBPm ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 31 March 2014 5.8 0.9 - (8.5) 67.3 65.5 Comprehensive income: Profit for the period - - - - 4.8 4.8 Other comprehensive expense: Actuarial loss on retirement benefit obligations - - - - (14.8) (14.8) Foreign currency translation adjustments - - - (1.2) - (1.2) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Total other comprehensive expense - - - (1.2) (14.8) (16.0) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Transactions with owners: Dividends paid - - - - (2.0) (2.0) Share option schemes and warrants 0.1 - (0.1) - 0.6 0.6 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 30 September 2014 5.9 0.9 (0.1) (9.7) 55.9 52.9 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Year ended 31 March 2015 (audited) Ordinary Retained share Share Treasury Translation earnings/ capital premium reserve reserve (losses) Total GBPm GBPm GBPm GBPm GBPm GBPm ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 31 March 2014 5.8 0.9 - (8.5) 67.3 65.5 Comprehensive income: Profit for the year - - - - 8.2 8.2 Other comprehensive expense: Actuarial loss on retirement benefit obligations - - - - (18.8) (18.8) Foreign currency translation adjustments - - - (0.6) - (0.6) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Total other comprehensive expense - - - (0.6) (18.8) (19.4) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Transactions with owners: Shares issued 0.2 0.1 (0.1) - - 0.2 Dividends paid - - - - (3.1) (3.1) (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Share option schemes and warrants - - - - 1.3 1.3 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 31 March 2015 6.0 1.0 (0.1) (9.1) 54.9 52.7 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Notes to the accounts Six months to 30 September 2015 1. Accounting policies General information The Company is a public limited company which is listed on the London Stock Exchange and incorporated and domiciled in the UK. This condensed consolidated interim financial information was approved for issue on 12 November 2015. This condensed consolidated financial information does not comprise statutory accounts within the meaning of Section 434 of the Companies Act 2006. This condensed consolidated interim financial information has been neither audited nor reviewed. Basis of preparation This condensed consolidated interim financial information for the six months to 30 September 2015 has been prepared in accordance with the Disclosure and Transparency Rules of the Financial Conduct Authority and with IAS 34, 'Interim financial reporting', as adopted by the European Union. The Directors consider, after making appropriate enquiries at the time of approving the condensed consolidated interim financial information, that the Company and the Group have adequate resources to continue in operational existence and, accordingly, that it is appropriate to adopt the going concern basis in the preparation of the condensed consolidated interim financial information. The condensed consolidated interim financial information should be read in conjunction with the Annual Report and Accounts for the year ended 31 March 2015, which has been prepared in accordance with IFRS as adopted by the European Union. The Annual Report and Accounts was approved by the Board on 18 June 2015 and delivered to the Registrar of Companies. The report of the external auditor on the financial statements was unqualified. Accounting policies The principal accounting policies applied in the preparation of this condensed consolidated interim financial information are included in the financial report for the year ended 31 March 2015. These policies have been applied consistently to all periods presented. Taxes on income in the interim periods are accrued using the tax rate that would be applicable to the expected total annual profits or losses. New standards, amendments to standards and interpretations The following new standards, amendments to standards or interpretations are mandatory for the first time for the financial year beginning 1 April 2015. The Group has adopted the following new standards, amendments and interpretations now applicable. None of these standards and interpretations has had any material effect on the Group's results or net assets. Applicable for financial years Standard or interpretation Content beginning on or after -------------------------------------- ----------------- --------------------- Amendment to IAS 19 (revised) Employee benefits 1 April 2015 Annual improvements to IFRSs 2010-2012 Various 1 April 2015 Annual improvements to IFRSs 2011-2013 Various 1 April 2015 -------------------------------------- ----------------- --------------------- The following standards, amendments and interpretations are not yet effective and have not been adopted early by the Group: Applicable for financial years Standard or interpretation Content beginning on or after --------------------------------- ----------------------------------------------------- --------------------- Amendment to IFRS 10 Consolidated financial statements 1 April 2016 Amendment to IFRS 11 Joint arrangements 1 April 2016 Amendment to IFRS 12 Disclosure of interests in other entities 1 April 2016 IFRS 14 Regulatory deferral accounts 1 April 2016 Amendment to IAS 1 Presentation of financial statements 1 April 2016 Amendment to IAS 16 Property, plant and equipment 1 April 2016 Amendment to IAS 27 Separate financial statements 1 April 2016 Amendment to IAS 28 Investments in associates and joint ventures 1 April 2016 Amendment to IAS 38 Intangible assets 1 April 2016 Amendment to IAS 41 Agriculture 1 April 2016 Annual improvements to IFRSs 2014 Various 1 April 2016 IFRS 15 Revenue from contracts with customers 1 April 2018 IFRS 9 Financial instruments: classification and measurement 1 April 2018 --------------------------------- ----------------------------------------------------- --------------------- None of these standards or interpretations is expected to have a material impact on the Group. Risks and uncertainties The principal strategic level risks and uncertainties affecting the Group, together with the approach to their mitigation, remain as set out on pages 24 to 27 in the 2015 Annual Report, which is available on the Group's website (www.norcros.com). In summary the Group's principal risks and uncertainties are: -- key commercial relationships; -- accounting for customer rebates and other trade promotional spend; -- competition; -- reliance on production facilities; -- staff retention and recruitment; -- foreign currency exchange risk; -- interest rate risk; -- pension scheme management; -- energy price risk; -- additional capital requirements to fund ongoing operations; -- performance against banking covenants; -- changing consumer preferences; -- overseas operations; and -- acquisition risk. The Chairman's Statement in this condensed consolidated interim financial information includes comments on the outlook for the remaining six months of the financial year. Forward-looking statements This condensed consolidated interim financial information contains forward-looking statements. Although the Group believes that the expectations reflected in these forward-looking statements are reasonable, it can give no assurance that these expectations will prove to be correct. Due to the inherent uncertainties, including both economic and business risk factors underlying such forward-looking information, actual results may differ materially from those expressed or implied by these forward-looking statements. The Group undertakes no obligation to update any forward-looking statements, whether as a result of new information, future events or otherwise. Accounting estimates and judgments The preparation of condensed consolidated interim financial information requires management to make judgments, estimates and assumptions that affect the application of accounting policies and the reported amount of assets and liabilities, income and expense. Actual results may differ from these estimates. In preparing the condensed consolidated interim financial information, the significant judgments made by management in applying the Group's accounting policies and the key sources of estimation uncertainty were the same as those applied to the consolidated financial statements for the year ended 31 March 2015. 2. Segmental reporting The Group operates in two main geographical areas: the UK and South Africa. All inter-segment transactions are made on an arm's length basis. The chief operating decision maker, which is considered to be the Board, assesses performance and allocates resources based on geography as each segment has similar economic characteristics, complementary products, distribution channels and regulatory environments. Continuing operations - 6 months to 30 September 2015 (unaudited) --------------------------------------------- South UK Africa Group Notes GBPm GBPm GBPm ---------------------------------- ----- ------------- -------------- -------------- Revenue 79.9 38.8 118.7 ---------------------------------- ----- ------------- -------------- -------------- Underlying operating profit 8.0 1.9 9.9 IAS 19R administrative expenses (0.8) - (0.8) Acquisition related costs 4 (2.6) - (2.6) Exceptional operating items 4 2.3 - 2.3 ---------------------------------- ----- ------------- -------------- -------------- (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Operating profit 6.9 1.9 8.8 ---------------------------------- ----- ------------- -------------- -------------- Finance costs (net) (1.8) ---------------------------------- ----- ------------- -------------- -------------- Profit before taxation 7.0 Taxation 6 (1.6) ---------------------------------- ----- ------------- -------------- -------------- Profit from continuing operations 5.4 ---------------------------------- ----- ------------- -------------- -------------- Net debt 10 (29.2) ---------------------------------- ----- ------------- -------------- -------------- Continuing operations - 6 months to 30 September 2014 (unaudited)* ---------------------------------------------- South UK Africa Group Notes GBPm GBPm GBPm ---------------------------------- ----- ------------- --------------- -------------- Revenue 72.8 35.8 108.6 ---------------------------------- ----- ------------- --------------- -------------- Underlying operating profit 6.4 1.0 7.4 IAS 19R administrative expenses (0.8) - (0.8) Acquisition related costs 4 (0.5) - (0.5) Exceptional operating items 4 0.3 - 0.3 ---------------------------------- ----- ------------- --------------- -------------- Operating profit 5.4 1.0 6.4 ---------------------------------- ----- ------------- --------------- -------------- Finance costs (net) (0.1) ---------------------------------- ----- ------------- --------------- -------------- Profit before taxation 6.3 Taxation 6 (1.6) ---------------------------------- ----- ------------- --------------- -------------- Profit from continuing operations 4.7 ---------------------------------- ----- ------------- --------------- -------------- Net debt 10 (20.0) ---------------------------------- ----- ------------- --------------- -------------- * The results have been restated to reflect the revised presentation of acquisition related costs. Continuing operations - Year ended 31 March 2015 (audited) --------------------------------------- South UK Africa Group Notes GBPm GBPm GBPm ------------------------------------------------ ------ ----------- ------------ ------------ Revenue 149.1 73.0 222.1 ------------------------------------------------ ------ ----------- ------------ ------------ Underlying operating profit 13.8 3.2 17.0 IAS 19R administrative expenses (1.7) - (1.7) Acquisition related costs 4 (2.2) - (2.2) Exceptional operating items 4 (2.3) (0.2) (2.5) ------------------------------------------------ ------ ----------- ------------ ------------ Operating profit 7.6 3.0 10.6 ------------------------------------------------ ------ ----------- ------------ ------------ Finance income (net) 0.4 ------------------------------------------------ ------ ----------- ------------ ------------ Profit before taxation 11.0 Taxation 6 (2.9) ------------------------------------------------ ------ ----------- ------------ ------------ Profit for the year from continuing operations 8.1 ------------------------------------------------ ------ ----------- ------------ ------------ Net debt 10 (14.2) ------------------------------------------------ ------ ----------- ------------ ------------ There are no differences from the last Annual Report in the basis of segmentation or in the basis of measurement of segment profit or loss. 3. Non-GAAP measures Condensed Consolidated Income Statement 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------------------------------- ------------ ------------ ---------- Profit before taxation from continuing operations 7.0 6.3 11.0 Adjusted for: IAS 19R administrative expenses 0.8 0.8 1.7 Acquisition related costs 2.6 0.5 2.2 Exceptional operating items (2.3) (0.3) 2.5 Amortisation of costs of raising debt finance 0.1 0.1 0.1 Amortisation of costs of raising debt finance - exceptional - 0.4 0.4 Net movement on fair value of derivative financial instruments 0.5 (1.6) (3.3) Discount on property lease provisions - - 0.1 IAS 19R finance cost 0.7 0.5 1.1 --------------------------------------------------------------- ------------ ------------ ---------- Underlying profit before taxation 9.4 6.7 15.8 Taxation attributable to underlying profit before taxation (2.1) (1.7) (2.8) --------------------------------------------------------------- ------------ ------------ ---------- Underlying earnings 7.3 5.0 13.0 --------------------------------------------------------------- ------------ ------------ ---------- The Directors believe that underlying profit before taxation and underlying earnings provide shareholders with additional useful information on the underlying performance of the Group. Underlying profit before taxation is defined as profit before taxation, IAS 19R administrative expenses, acquisition related costs, exceptional operating items, exceptional finance costs, amortisation of costs of raising finance, net movement on fair value of derivative financial instruments, discounting of property lease provisions and finance costs relating to pension schemes. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------- ------------ ------------ ---------- Operating profit from continuing operations 8.8 6.4 10.6 Adjusted for: Depreciation 2.9 3.0 6.0 IAS 19R administrative expenses 0.8 0.8 1.7 Acquisition related costs 2.6 0.5 2.2 Exceptional operating items (2.3) (0.3) 2.5 -------------------------------------------- ------------ ------------ ---------- Underlying EBITDA 12.8 10.4 23.0 -------------------------------------------- ------------ ------------ ---------- (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) EBITDA is a measure commonly used by investors and financiers to assess business performance. Underlying EBITDA has been provided which reflects EBITDA as adjusted for IAS 19R administrative expenses, acquisition related costs and exceptional operating items. The Directors consider that these measures provide shareholders with additional useful information on the performance of the Group. Condensed Consolidated Statement of Cash Flow 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------------------------------------- ------------ ------------ ---------- Cash generated from continuing operations (note 10) 12.9 9.9 16.1 Adjusted for: Cash (inflows)/outflows from exceptional items and acquisition related costs (0.7) 0.7 4.7 Pension fund deficit recovery contributions 1.1 1.0 2.1 ----------------------------------------------------------------------------- ------------ ------------ ---------- Underlying operating cash flow 13.3 11.6 22.9 ----------------------------------------------------------------------------- ------------ ------------ ---------- Underlying operating cash flow is defined as cash generated from continuing operations before cash outflows from exceptional items and pension fund deficit recovery contributions. The Directors believe that underlying operating cash flow provides shareholders with additional useful information on the underlying cash generation of the Group. 4. Acquisition related costs and exceptional operating items An analysis of acquisition related costs and exceptional operating items is shown below. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------- ------------ ------------ ---------- Acquisition related costs Deferred remuneration(1) 1.2 0.3 1.1 Intangible asset amortisation(2) 0.3 0.2 0.3 Staff costs and advisory fees(3) 1.1 - 0.8 --------------------------------- ------------ ------------ ---------- 2.6 0.5 2.2 --------------------------------- ------------ ------------ ---------- 1 Consideration payable to the former shareholders of Vado and Croydex which is required to be treated as remuneration and, accordingly, is expensed to the income statement as incurred. 2 Non-cash amortisation charges in respect of intangible assets recognised following the acquisitions of Vado and Croydex. 3 Costs of maintaining an in-house acquisitions department and professional advisory fees incurred in connection with the Group's business combination activities. In the 6 months to 30 September 2015 this included GBP0.8m in connection with the acquisition of Croydex. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------------ ------------ ------------ ---------- Exceptional operating items Legal claim(1) (1.9) 0.1 0.3 Pension scheme settlement gain(2) (0.4) - (1.7) Profit on disposal of surplus property(3) - (0.4) (0.4) Sheffield lease surrender(4) - - 2.5 Loss on disposal of property portfolio(5) - - 1.5 Restructuring costs(6) - - 0.3 (2.3) (0.3) 2.5 ------------------------------------------ ------------ ------------ ---------- 1 The legal claim relating to the land at the Highgate site in Tunstall, UK was settled in the period. Under the terms of the settlement with Wm Morrison Supermarkets plc the Group received a payment of GBP2.0m. Costs in connection with the claim of GBP0.1m were incurred in the period (2014: GBP0.1m). 2 The Group implemented a liability management exercise in the previous year in connection with its principal UK defined benefit pension scheme. This resulted in a further settlement gain of GBP0.4m being recognised in the period in addition to the GBP1.7m gain in the previous year. 3 A profit of GBP0.4m was generated in the previous year following the sale of a small parcel of land in Braintree, UK. 4 In the previous year the Group exited its onerous lease in connection with the Orgreave Drive, Sheffield property at a cost of GBP2.5m. 5 The Group's remaining surplus freehold property portfolio was sold to Clowes Developments (UK) Ltd in March 2015 for net proceeds of GBP6.1m, leading to a loss on disposal of GBP1.5m. 6 Restructuring costs related to redundancies and asset write-downs as a result of restructuring initiatives throughout the Group's business units. 5. Earnings per share Basic and diluted earnings per share Basic earnings per share (EPS) is calculated by dividing the profit attributable to shareholders by the weighted average number of ordinary shares in issue during the year, excluding those held in the Norcros Employee Benefit Trust. For diluted EPS, the weighted average number of ordinary shares in issue is adjusted to assume conversion of all potential dilutive ordinary shares. As described in note 9, on 29 September 2015 the Company consolidated its existing ordinary shares of 1p each into new ordinary shares of 10p each. In order to effect fair comparison, the comparative figures for share numbers and earnings per share have been restated to reflect the impact of the share consolidation. The calculation of EPS is based on the following profits and numbers of shares: 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------------------- ------------ ------------ ---------- Profit for the period from continuing operations 5.4 4.7 8.1 Profit for the period from discontinued operations - 0.1 0.1 --------------------------------------------------- ------------ ------------ ---------- Profit for the period 5.4 4.8 8.2 --------------------------------------------------- ------------ ------------ ---------- 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) Number Number Number (restated) (restated) ----------------------------------------------------------------- ------------ ------------ ----------- Weighted average number of shares for basic earnings per share 60,126,284 58,959,370 59,223,135 Share options and warrants 1,902,048 2,159,547 2,303,299 Weighted average number of shares for diluted earnings per share 62,028,332 61,118,917 61,526,434 ----------------------------------------------------------------- ------------ ------------ ----------- 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (audited) (unaudited) (restated) (restated) ----------------------------- ------------ ------------ ----------- Basic earnings per share: From continuing operations 9.0p 8.0p 13.6p From discontinued operations - 0.2p 0.2p ----------------------------- ------------ ------------ ----------- From profit for the period 9.0p 8.2p 13.8p (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) ----------------------------- ------------ ------------ ----------- Diluted earnings per share: From continuing operations 8.7p 7.7p 13.1p From discontinued operations - 0.2p 0.2p ----------------------------- ------------ ------------ ----------- From profit for the period 8.7p 7.9p 13.3p ----------------------------- ------------ ------------ ----------- Basic and diluted underlying earnings per share Basic and diluted underlying earnings per share have also been provided which reflect underlying earnings from continuing operations divided by the weighted average number of shares set out above. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------- ------------ ------------ ---------- Underlying earnings for the period (note 3) 7.3 5.0 13.0 -------------------------------------------- ------------ ------------ ---------- 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) -------------------------------------- ------------ ------------ ---------- Basic underlying earnings per share 12.2p 8.4p 21.9p Diluted underlying earnings per share 11.8p 8.1p 21.1p -------------------------------------- ------------ ------------ ---------- 6. Taxation Taxation comprises: 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------------- ------------ ------------ ---------- Current UK taxation 0.5 0.5 0.4 Deferred Origination and reversal of temporary differences 1.1 1.1 2.5 -------------------------------------------------- ------------ ------------ ---------- Taxation 1.6 1.6 2.9 -------------------------------------------------- ------------ ------------ ---------- Current tax expense is recognised based on management's estimate of the weighted average annual income tax rate expected for the full financial year. Deferred tax assets and liabilities are offset when there is a legally enforceable right to offset current tax assets against current tax liabilities and when the deferred income taxes relate to the same fiscal authority. Deferred tax is calculated in full on temporary differences under the liability method. The movement on the deferred tax account is as shown below: 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------------------- ------------ ------------ ---------- Deferred tax asset at the beginning of the period 13.8 11.6 11.6 Charged to the income statement (1.1) (1.1) (2.5) (Charged)/credited to statement of comprehensive income (0.4) 3.7 4.7 Acquisitions (see note 13) (0.8) - - Exchange movement (0.3) (0.1) - -------------------------------------------------------- ------------ ------------ ---------- Deferred tax asset at the end of the period 11.2 14.1 13.8 -------------------------------------------------------- ------------ ------------ ---------- At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------- ------------ ------------ --------- Accelerated capital allowances 2.6 2.9 2.7 Tax losses 2.5 3.8 3.3 Other timing differences (2.4) (0.7) (1.1) Deferred tax asset relating to pension deficit 8.5 8.1 8.9 ----------------------------------------------- ------------ ------------ --------- 11.2 14.1 13.8 ----------------------------------------------- ------------ ------------ --------- 7. Finance income and costs 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------------------- ------------ ------------ ---------- Finance costs Interest payable on bank borrowings 0.5 0.7 1.2 Amortisation of costs of raising debt finance 0.1 0.1 0.1 Movement on fair value of derivative financial instruments 0.5 - - Unwind of discount on property lease provisions - - 0.1 ----------------------------------------------------------- ------------ ------------ ---------- Finance costs 1.1 0.8 1.4 ----------------------------------------------------------- ------------ ------------ ---------- Exceptional finance costs(1) - 0.4 0.4 ----------------------------------------------------------- ------------ ------------ ---------- Total finance costs 1.1 1.2 1.8 ----------------------------------------------------------- ------------ ------------ ---------- Finance income Movement on fair value of derivative financial instruments - (1.6) (3.3) ----------------------------------------------------------- ------------ ------------ ---------- Total finance income - (1.6) (3.3) ----------------------------------------------------------- ------------ ------------ ---------- 1 Following the refinancing of the Group's banking facilities in July 2014, the unamortised costs relating to the previous facility were written off in full. 8. Borrowings At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------- ------------ ------------ --------- Non-current Bank borrowings (unsecured): - bank loans 33.0 21.0 19.0 - less: costs of raising finance (0.5) (0.6) (0.6) --------------------------------- ------------ ------------ --------- Total non-current 32.5 20.4 18.4 --------------------------------- ------------ ------------ --------- Current Bank borrowings (unsecured): - bank overdrafts 4.5 4.1 1.4 --------------------------------- ------------ ------------ --------- Total borrowings 37.0 24.5 19.8 --------------------------------- ------------ ------------ --------- The fair value of bank loans equals their carrying amount as they bear interest at floating rates. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) The repayment terms of borrowings are as follows: At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------------- ------------ ------------ --------- Not later than one year 4.5 4.1 1.4 ----------------------------------------------------- ------------ ------------ --------- After more than one year: - between one and two years - - - - later than two years and not later than five years 33.0 21.0 19.0 - costs of raising finance (0.5) (0.6) (0.6) ----------------------------------------------------- ------------ ------------ --------- 32.5 20.4 18.4 ----------------------------------------------------- ------------ ------------ --------- Total borrowings 37.0 24.5 19.8 ----------------------------------------------------- ------------ ------------ --------- In July 2014 the Group agreed an unsecured GBP70m revolving credit facility with a GBP30m accordion facility with Lloyds Bank plc, Barclays Bank plc and HSBC Bank plc. The banking facility is in force for five years to July 2019. Net debt The Group's net debt is calculated as follows: At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------- ------------ ------------ --------- Cash and cash equivalents (7.8) (4.5) (5.6) Total borrowings 37.0 24.5 19.8 -------------------------- ------------ ------------ --------- Net debt 29.2 20.0 14.2 -------------------------- ------------ ------------ --------- 9. Called up share capital At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------- ------------ ------------ --------- Issued and fully paid 60,995,930 ordinary shares of 10p each 6.1 - - 594,917,377 ordinary shares of 1p each - 5.9 6.0 --------------------------------------- ------------ ------------ --------- Total 6.1 5.9 6.0 --------------------------------------- ------------ ------------ --------- Following the approval by shareholders of the consolidation of 1p ordinary shares into ordinary shares of 10p at the Annual General Meeting of the Company held on 22 July 2015, the Company duly completed the share capital consolidation with a record date of 29 September 2015. As a result of the consolidation, the ordinary shares of 1p each were amended to new ordinary shares of 10p each. The share consolidation had no impact on the value of the Company's issued and fully paid share capital. 10. Consolidated Cash Flow Statements (a) Cash generated from continuing operations 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------------------------------------------------ ------------ ------------ ---------- Profit before taxation 7.0 6.3 11.0 Adjustments for: - IAS 19R administrative expenses included in the above 0.8 0.8 1.7 - acquisition related costs included in the above 2.6 0.5 2.2 - exceptional operating items included in the above (2.3) (0.3) 2.5 - cash inflows/(outflows) from exceptional items and acquisition related costs 0.7 (0.7) (4.7) - depreciation 2.9 3.0 6.0 - pension fund deficit recovery plan contributions (1.1) (1.0) (2.1) - loss on disposal of property, plant and equipment - - 0.1 - total finance costs 1.1 1.2 1.8 - finance income - (1.6) (3.3) - IAS 19R finance cost 0.7 0.5 1.1 - share-based payments 0.7 0.6 1.3 ------------------------------------------------------------------------------ ------------ ------------ ---------- Operating cash flows before movements in working capital 13.1 9.3 17.6 Changes in working capital: - increase in inventories (4.4) (1.4) (2.0) - increase in trade and other receivables (1.0) (0.8) (1.4) - increase in payables 5.2 2.8 1.9 ------------------------------------------------------------------------------ ------------ ------------ ---------- Cash generated from continuing operations 12.9 9.9 16.1 ------------------------------------------------------------------------------ ------------ ------------ ---------- Cash flows from exceptional items includes expenditure charged to exceptional provisions relating to onerous lease costs, acquisition related costs (excluding deferred remuneration) and other business rationalisation and restructuring costs. (b) Cash generated from discontinued operations 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------------------------- ------------ ------------ ---------- Profit before taxation - - - Adjustments for: - depreciation - - - --------------------------------------------------------- ------------ ------------ ---------- Operating cash flows before movements in working capital - - - Changes in working capital: - decrease in inventories - 0.4 0.4 - increase in trade and other receivables - (0.1) (0.1) - decrease in payables - (0.2) (0.2) --------------------------------------------------------- ------------ ------------ ---------- Cash generated from discontinued operations - 0.1 0.1 --------------------------------------------------------- ------------ ------------ ---------- Cash generated from operations 12.9 10.0 16.2 --------------------------------------------------------- ------------ ------------ ---------- (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) (c) Analysis of net debt Cash included within Cash and assets held-for-sale overdrafts Debt Total GBPm GBPm GBPm GBPm ------------------------- -------------------- ---------- ------ ------ At 1 April 2014 0.5 3.2 (30.6) (26.9) Cash flow (0.5) 1.1 12.1 12.7 Other non-cash movements - - 0.1 0.1 Exchange movement - (0.1) - (0.1) ------------------------- -------------------- ---------- ------ ------ At 31 March 2015 - 4.2 (18.4) (14.2) ------------------------- -------------------- ---------- ------ ------ At 1 April 2014 0.5 3.2 (30.6) (26.9) Cash flow (0.5) (2.7) 10.1 6.9 Other non-cash movements - - 0.1 0.1 Exchange movement - (0.1) - (0.1) ------------------------- -------------------- ---------- ------ ------ At 30 September 2014 - 0.4 (20.4) (20.0) ------------------------- -------------------- ---------- ------ ------ At 1 April 2015 - 4.2 (18.4) (14.2) Cash flow - (0.1) (14.0) (14.1) Other non-cash movements - - (0.1) (0.1) Exchange movement - (0.8) - (0.8) ------------------------- -------------------- ---------- ------ ------ At 30 September 2015 - 3.3 (32.5) (29.2) ------------------------- -------------------- ---------- ------ ------ 11. Dividends A final dividend in respect of the year ended 31 March 2015 of GBP2.2m (0.375p per 1p ordinary share) was paid on 29 July 2015. On 12 November 2015 the Board declared an interim dividend in respect of the year ended 31 March 2016 of GBP1.3m (2.2p per 10p ordinary share). This dividend will be paid on 7 January 2016 and is not reflected in this condensed consolidated interim financial information. 12. Retirement benefit obligations (a) Pension costs Norcros Security Plan The Norcros Security Plan (the "Plan"), the principal UK pension scheme of Norcros plc subsidiaries, is funded by a separate trust fund which operates under UK trust law and is a separate legal entity from the Company. The Plan is governed by a Trustee board which is required by law to act in the best interests of the Plan members and is responsible for setting policies together with the Company. It is predominantly a defined benefit scheme with a modest element of defined contribution benefits. The valuation used for IAS 19R disclosures has been produced by KPMG, a firm of qualified actuaries, to take account of the requirements of IAS 19R in order to assess the liabilities of the scheme at 30 September 2015. Scheme assets are stated at their market value at 30 September 2015. (b) IAS 19R, 'Retirement benefit obligations' The principal assumptions used to calculate the scheme liabilities of the Norcros Security Plan under IAS 19R are: At At At 30 September 30 September 31 March 2015 2014 2015 --------------------- ------------ ------------ -------- Discount rate 3.80% 3.90% 3.30% Inflation rate (RPI) 3.00% 3.05% 2.90% Inflation (CPI) 2.00% 2.05% 1.90% Salary increases 2.25% 3.30% 2.15% --------------------- ------------ ------------ -------- The amounts recognised in the Condensed Consolidated Balance Sheet are determined as follows: At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------ ------------ ------------ --------- Total market value of scheme assets 367.8 385.0 397.0 Present value of scheme liabilities (410.2) (425.6) (441.3) ------------------------------------ ------------ ------------ --------- Pension deficit (42.4) (40.6) (44.3) ------------------------------------ ------------ ------------ --------- 13. Business combinations On 25 June 2015, the Group acquired 100% of the ordinary share capital of Croydex Group Limited ("Croydex"), a market leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories. The acquisition of Croydex is an important next step in the Group's growth strategy to increase revenue to GBP420m by 2018 and follows on from the very successful integration of the Vado business, which Norcros acquired in March 2013. Adding the Croydex business to the Group's existing portfolio will increase the breadth of our product range in the bathroom segment and enable the Group to offer an even broader range of complementary bathroom products to our customers. Croydex will also benefit from the global distribution channels, sourcing skills and strong financial position of the enlarged Group. Croydex is incorporated in England and is based in Andover, Hampshire. The following table summarises the consideration paid for Croydex and the provisional fair value of the assets acquired and the liabilities assumed: GBPm ------------------------- ----- Consideration Cash 20.8 Deferred consideration 1.1 ------------------------- ----- 21.9 ------------------------ ----- GBPm --------------------------------------------------- --------- Recognised amounts of identifiable assets and liabilities Intangible assets 7.9 Property, plant and equipment 1.6 Inventories 2.8 Trade and other receivables 5.0 Cash 3.5 Trade and other payables (5.7) Current tax liabilities (0.2) Deferred tax liability (0.8) Total identifiable net assets 14.1 --------------------------------------------------- --------- Goodwill 7.8 Total 21.9 --------------------------------------------------- --------- Due to the proximity of the acquisition date to the date of this interim statement it has not been possible for the Group to finalise the fair values of Croydex's assets and liabilities. The provisional fair value adjustments reflect the preliminary assessment of the value of acquired intangible assets of GBP7.9m, the revaluation of the leasehold property of GBP0.9m, and a deferred tax liability of GBP1.0m mainly arising from the recognition of acquired intangible assets. A full review of the fair values of the identifiable assets and liabilities will take place over the coming months with the expectation that a revised position will be presented in the Group's Annual Report for the year ended 31 March 2016. In most business combinations there is an element of cost which cannot be allocated against the individual assets and liabilities acquired. This residual amount is recognised as goodwill and is supported by a number of factors which do not meet the criteria required for them to be treated as intangible assets. In this case the most significant elements relate to Croydex's unique product portfolio and its knowledgeable workforce. It is not expected at this stage that any of the goodwill will be deductible for tax purposes. The fair value of trade and other receivables is GBP5.0m, which includes trade receivables with a fair value of GBP4.6m. The gross contractual amount for trade receivables due is GBP4.8m, of which GBP0.2m is expected to be uncollectible. Costs relating to the transaction of GBP0.8m have been expensed to the Consolidated Income Statement and included within acquisition related costs. The deferred consideration of GBP1.1m is unconditional and will be paid in the year ended 31 March 2019. As part of the transaction, a long-term incentive scheme has been put in place for the Croydex Managing Director which is dependent on the financial performance of Croydex over the next three years. The maximum amount and current expectation is that GBP0.9m will be payable under this scheme which will be treated as deferred remuneration and included within acquisition related costs in the Consolidated Income Statement. The revenue included in the Condensed Consolidated Statement of Comprehensive Income since 25 June 2015 contributed by Croydex was GBP5.8m. Over the same period, Croydex contributed profit after tax of GBP0.6m. Had Croydex been consolidated from the beginning of the period, the Condensed Consolidated Statement of Income would have shown pro-forma revenue of GBP123.7m and pro-forma profit after tax of GBP5.6m. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT)