Showing posts sorted by relevance for query residential housing market. Sort by date Show all posts

Sunday, December 10, 2017

Maax Hydro Swirl Mfr Bellingham, WA 98226

Read article : Maax Hydro Swirl Mfr Bellingham, WA 98226

Business DetailsCouponsGalleryReviews
Sponsored Links
General Info
MAAX Corporation is one of the leading manufacturers of bathroom products and spas for the residential housing market in the United States. It offers its products through plumbing wholesalers, bath and spa specialty boutiques and home improvement centers. The corporation employs more than 1,800 people and operates over 10 manufacturing facilities and independent distribution centers throughout the U.S. and Europe. Established in 1969, MAAX Corporation provides products, such as include bathtubs, whirlpools, airpools, shower doors, tub showers, wall surrounds, medicine cabinets and bathroom storage solutions. It also offers upscale bathware remodeling solutions and designs, as well as has a range of acrylic and gel coat products. The company s brands include SaniNova, Keystone and Advanta.
Hours
Do you know the hours for this business?
Neighborhood
Mount Baker
AKA

Maax Hydro Swirl Manufacturer

Categories
Plumbing Fixtures Parts & Supplies-Wholesale & Manufacturers,Heating Equipment & Systems-Wholesale
image

COUPONS & DEALS

No coupons available

Gallery

Be the first to add a photo!

Reviews

Hi there!
Be the first to review!

Click to Rate
Share Review

Like this review? Share it on your social network to get the word out!

Friday, June 2, 2017

Dispossessed in the Land of Dreams

Read article : Dispossessed in the Land of Dreams


Sometime in July 2012, Suzan Russaw and her husband, James, received a letter from their landlord asking them to vacate their $800-a-month one-bedroom apartment in Palo Alto, California. He gave them 60 days to leave. The “no-fault” eviction is a common way to clear out low-paying tenants without a legal hassle and bring in people willing to pay thousands more in rent. James was 83 at the time and suffering from the constellation of illnesses that affect the old: He had high blood pressure and was undergoing dialysis for kidney failure and experiencing the early stages of dementia.

Their rent was actually a couple of hundred dollars more than James’s monthly Social Security benefits, but he made up the rest by piecing together odd jobs. They looked for a new apartment for two months and didn’t find anything close to their price range. Their landlord gave them a six-week extension, but it yielded nothing. When mid-October came, Suzan and James had no choice but to leave. With hurried help from neighbors, they packed most of their belongings into two storage units and a ramshackle 1994 Ford Explorer which they called “the van.” They didn’t know where they were going.

A majority of the homeless population in Palo Alto—93 percent—ends up sleeping outside or in their cars. In part, that’s because Palo Alto, a technology boomtown that boasts a per capita income well over twice the average for California, has almost no shelter space: For the city’s homeless population, estimated to be at least 157, there are just 15 beds that rotate among city churches through a shelter program called Hotel de Zink; a charity organizes a loose network of 130 spare rooms, regular people motivated to offer up their homes only by neighborly goodwill. The lack of shelter space in Palo Alto—and more broadly in Santa Clara and San Mateo counties, which comprise the peninsula south of San Francisco and around San Jose—is unusual for an area of its size and population. A 2013 census showed Santa Clara County having more than 7,000 homeless people, the fifth-highest homeless population per capita in the country and among the highest populations sleeping outside or in unsuitable shelters like vehicles.

San Francisco and the rest of the Bay Area are gentrifying rapidly—especially with the most recent Silicon Valley surge in social media companies, though the trend stretches back decades—leading to a cascade of displacement of the region’s poor, working class, and ethnic and racial minorities. In San Francisco itself, currently the city with the most expensive housing market in the country, rents increased 13.5 percent in 2014 from the year before, leading more people to the middle-class suburbs. As real estate prices rise in places like Palo Alto, the middle class has begun to buy homes in the exurbs of the Central Valley, displacing farmworkers there.

Suzan, who is 70, is short and slight, with her bobbed hair dyed red. The first time I met her, she wore leggings, a T-shirt, a black cardigan wrapped around her shoulders, and fuzzy black boots I later learned were slippers she’d gotten from Goodwill and sewn up to look like outside shoes. (She wore basically the same outfit, with different T-shirts, nearly every time we met, and I realized she didn’t have many clothes.) Her voice is high and singsongy and she is always polite. You can tell she tries to smooth out tensions rather than confront them. She is a font of forced sunniness and likes to punctuate a sad sentence with phrases like “I’m so blessed!” or “I’m so lucky!” She wore a small necklace and said jewelry was important to her. “I feel, to dispel the image of homelessness, it’s important to have a little bling,” she said.

In the van, Suzan was in charge of taking care of everyone and everything, organizing a life that became filled with a unique brand of busy boredom. She and James spent most of their time figuring out where to go next, how to get there, and whether they could stay once they arrived. They found a short-term unit in a local family shelter in Menlo Park that lasted for five weeks. Afterward, they stayed in a few motels, but even fleabags in the area charge upwards of $100 a night. When they couldn’t afford a room they camped out in the van, reclining the backseats and making a pallet out of blankets piled on top of their clothes and other belongings. Slowly, there were fewer nights in hotels and more in the van, until the van was where they lived.

A life of homelessness is one of logistical challenges and exhaustion. Little things, like planning a wardrobe for the week, involved coordinated trips to storage units and laundromats, and could take hours. The biggest conundrum? Where to pull over and sleep. Suzan and James learned quickly not to pull over on a residential block, because the neighbors would call the police. They tried a church or two, 24-hour businesses where they thought they could hide amidst the other cars, and even an old naval field. The places with public toilets were best because, for reasons no one can quite explain, 3 a.m. is the witching hour for needing to pee. They kept their socks and shoes on, both for staying warm on chilly Bay Area nights and also for moving quickly if someone peered into their windows, or a cop flashed his light inside, ready to rouse. Wherever they were sleeping, they couldn’t sleep there. “Sometimes, I was so tired, I would be stopped at a red light and say, ‘Don’t go to sleep. Don’t go to sleep,’” Suzan said. “And then I would fall asleep.”

A few months in, a nice man in a 7-Eleven parking lot told them about a former high school turned community center on the eastern side of town called Cubberley. He’d walked up to their van after recognizing signs of life in the car, tired faces among the junk piling up in the back. Suzan and James were familiar with the community center because they’d taken their daughter to preschool there many years before, but they hadn’t thought about sleeping there. Cubberley had a quiet back parking lot, a flat grass amphitheater with a concrete paddock for a stage, and 24-hour public bathrooms with showers in an old gym. Rumor was that the cops wouldn’t bother anyone.

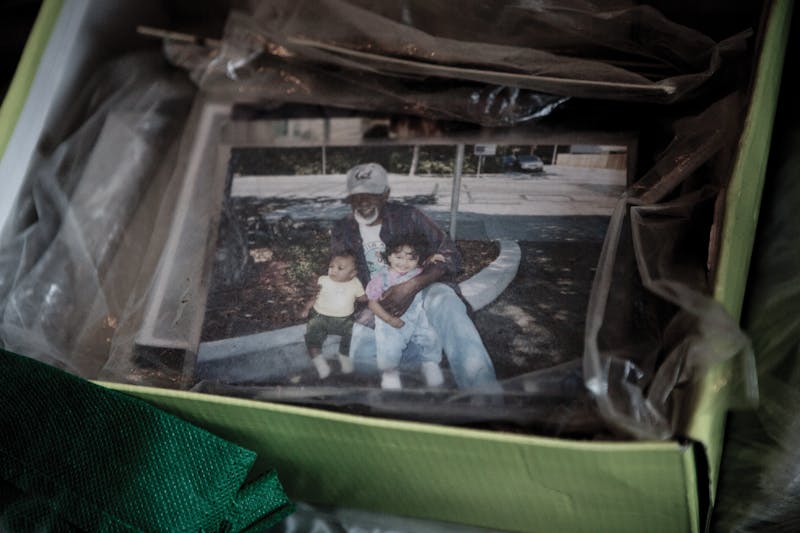
imageSuzan’s husband, James Russaw, pictured with two of their grandchildren.

Cubberley was a psychic relief because it solved so many basic needs: It had a place to bathe in the morning, a place to charge your phone. The parking lot had also formed its own etiquette and sense of community. People tended to park in the same places, a spot or two next to their neighbors, and they recognized one another and nodded at night. They weren’t exactly friends, but they were people who trusted each other, an impromptu neighborhood no one wanted to lose after losing so much. It was safe, a good place to spend the night. But it was next door to a segment of homeowners who were fighting hard to move the car dwellers out.

Normally, wealthy people who move into an area don’t see the results of their displacement because the people who lose their homes don’t stick around; they move to cheaper suburbs and work themselves into the fabric elsewhere. But the folks at Cubberley, 30 people on any given night, were the displacement made manifest. Most weren’t plagued with mental health or substance abuse problems; they simply could no longer afford rent and became homeless in the last place they lived. People will put up with a lot to stay in a place they know. “I’ve been analyzing why don’t I just get the heck on. Everybody says that, go to Wyoming, Montana, you can get a mansion,” Suzan said. “Move on, move on, always move on. And I say to myself, ‘Why should I have to move on?’”

It’s a new chapter in an old story. In his seminal 1893 lecture at the Chicago World’s Fair, Frederick Jackson Turner summarized the myth of the American frontier and the waves of settlers who created it as an early form of gentrification: First, farmers looking for land would find a remote spot of wilderness to tame; once they succeeded, more men and women would arrive to turn each new spot into a town; finally, outside investors would swoop in, pushing out the frontiersman and leaving him to pack up and start all over again. It has always been thus in America. Turner quoted from a guide published in 1837 for migrants headed for the Western frontiers of Ohio, Indiana, and Wisconsin: “Another wave rolls on. The men of capital and enterprise come. The ‘settler’ is ready to sell out and take the advantage of the rise of property, push farther into the interior, and become himself a man of capital and enterprise in turn.” This repeating cycle, Turner argued, of movement and resettlement was essential to the American character. But he foresaw a looming crisis. “The American energy will continually demand a wider field for its exercise,” he wrote. “But never again will such gifts of free land offer themselves.” In other words, we would run out of places for the displaced to go.


Suzan was born in 1945. Her father worked at what was then the Lockheed Corporation, and her mother had been raised by a wealthy family in Oak Park, Illinois. Her family called her Suzi. Though she grew up in nearby Saratoga—and spent some time in school in Switzerland—she distinctly remembers coming with her mother to visit Palo Alto, with its downtown theaters and streets named after poets. Palo Alto more than any other place formed the landscape of her childhood. “It was a little artsy-craftsy university town—you find charming towns are university towns.”

Like many women of her day, Suzan didn’t graduate from college. When she was 24, after her last stay in Switzerland, she moved to Mountain View, the town on Palo Alto’s eastern border that is now home to Google and LinkedIn. She was living off a small trust her family had set up for her when she met James at a barbecue their apartment manager threw to foster neighborliness among his tenants. James had grown up in a sharecropping family in Georgia, moved west during World War II, and was more than 17 years her senior, handsome and gentlemanly. Suzan thought: “I can learn something from him.” They were an interracial couple in the late 1960s, which was unusual, though she says her family didn’t mind. It was also an interclass marriage, and it moved Suzan down the income ladder.

For years, James and Suzan lived together, unmarried. They bought a house on University Avenue, just north of the county line and blocks from downtown Palo Alto, in 1979, and four years later had their only daughter, Nancy. It was the area’s ghetto, and the only source of affordable housing for many years. It was also the center of violence in the region, and, in 1992, was the murder capital of the country.

They never had much money. For most of their marriage, James ran a small recycling company and Suzan acted as his bookkeeper, secretary, and housewife. They refused to apply for most government assistance, even as homeless elders. “My husband and I had never been on welfare or food stamps,” she told me. “Even to this day.”

Suzan’s parents died in 2002 and 2003, and her older sister died in 2009. (“I thank God that they’re gone,” she told me. “They would die if they saw me now.”) It was a hard time for Suzan, who went to care for her dying parents and nearly left James. She felt he’d checked out of the difficulties. In retrospect, she thinks his dementia might already have been setting in; James was already in his seventies. He had taken out a second mortgage on their home, and they couldn’t pay it after he retired. They sold the house at a loss in 2005; it’s now a Century 21 office.

After they moved into the van, they settled into a routine. On the nights before James’s early-morning treatments, they slept in the dialysis center’s parking lot. Otherwise they generally stayed at Cubberley. They were still living off James’s retirement income, but most of it went to the $500 needed to rent the two storage units where their furniture remained, until they lost one for nonpayment. Finally, a few months in, Suzan was able to use a clause in a trust set up by her mother’s father to help her out in an emergency. It doubled their income—much of which was eaten up by the costs of gas, the remaining storage unit, parking tickets, and the other expenses of an unsettled life. It was a respectable income, one that technically kept them above poverty, but it still wasn’t enough for rent.

James was increasingly ill and van life was taking a toll. In addition to James’s other problems, both he and Suzan were starting to experience some of the health problems common among the homeless. The backseat of the van filled with bags of clothes, papers, fast-food detritus, pens, old parking tickets, and receipts. As the junk built up, the recline of their seats inched forever upward, until they were sitting up all the time, causing their legs to swell and nerves to become damaged, the medical consequences of not being able to raise your feet at night.


Gentrification used to be about poor neighborhoods, usually black and brown, underdeveloped and full of decrepit and neglected housing stock, run by the occasional slumlord—often described as “blighted,” though that designation has always been problematic—and how they become converted into wealthier ones, usually through the influx of richer white people and their demand for new services and new construction. It’s a negative process for the people who have to move, but there’s occasionally an element of good, because neglected neighborhoods revive. But what’s happening now in the Bay Area is that people who’ve done nothing wrong—not paid their rent late, violated their lease, or committed any other housing sin—are being forced out to make way. Displacement is reaching into unquestionably vibrant, historic, middle- and working-class neighborhoods, like The Mission in San Francisco, a former center of Chicano power. (The Mission alone has lost 8,000 Latino residents in the past ten years, according to a report from the local Council of Community Housing Organizations and the Mission Economic Development Agency.) And it’s happening to such an extent that the social workers who used to steer people to affordable apartments as far away as Santa Rosa or Sacramento, a two-hour drive, are now telling people to look even farther out. The vehicle dwellers I spoke with said they’d heard of friends living in places like Stockton, once a modest working-class city in the middle of the state, receiving notice-to-vacate letters like the one Suzan and James received.

For the most part, the traits that draw people to Palo Alto—good schools, a charming downtown, nice neighborhoods in which to raise a family, and a short commute to tech jobs—are the very same things that made the residents of Cubberley want to stay, even if it meant living in their car. The destabilizing pressure of a real estate market is also felt by the merely rich, the upper middle class, and the middle class, because the high-end demand of the global elite sets the market prices. “My block has the original owners, a retired schoolteacher and a retired postal worker,” said Hope Nakamura, a legal aid attorney who lives in Palo Alto. “They could never afford to buy anything there now.” Most people told me if they had to sell their homes today they wouldn’t be able to buy again anywhere in the area, which means many Palo Altans have all of their wealth tied up in expensive homes that they can’t access without upending their lives. It makes everyone anxious.

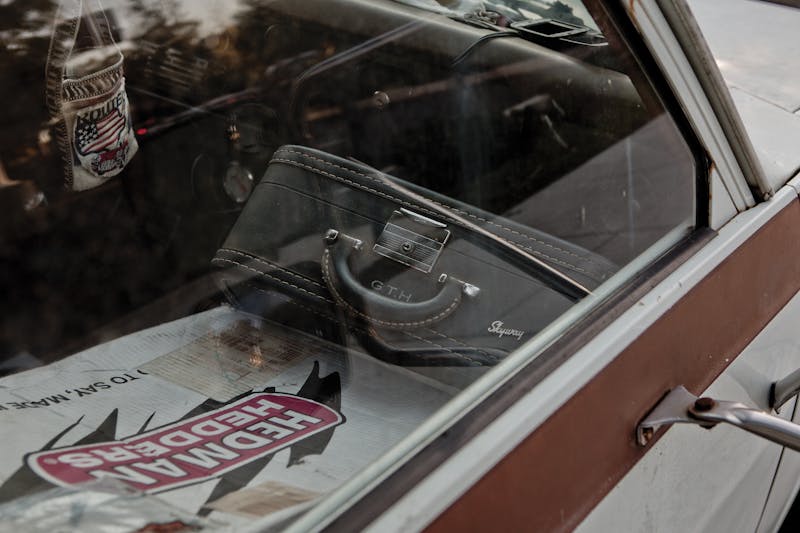
imageThe view inside a van parked outside a Palo Alto homeless organization.

The outcry from the neighbors over Cubberley was so fierce that it reshaped Palo Alto’s city government. The city council is nonpartisan, but a faction emerged that revived an old, slow-growth movement in town, known as the “residentialists.” Their concerns are varied (among them, the perennial suburban concerns of property values and traffic), but their influence has been to block any new development of affordable housing and shoo people like Suzan and James away from Palo Alto. An uproar scuttled an affordable-housing building for senior citizens near many public transit options that had been proposed by the city housing authority and unanimously approved by the city council. Opponents said they were worried about the effect the development would have on the surrounding community—they argued it wasn’t zoned for “density,” which is to say, small apartments—and that traffic congestion in the area would be made worse. Aparna Ananthasubramaniam, then a senior at Stanford, tried to start a women’s-only shelter in rotating churches, modeled after the Hotel de Zink. She said a woman came up to her after a community meeting where the same concerns had been raised by a real estate agent. “Her lips were quivering and she was physically shaking from how angry she was,” Ananthasubramaniam told me. “She was like, ‘You come back to me 20 years from now once you have sunk more than $1 million into an asset, like a house, and you tell me that you’re willing to take a risk like this.”

The trouble for Cubberley began when neighbors went to the police. There’d been at least one fight, and the neighbors complained about trash left around the center. At the time, Cubberley was home to a 64-year-old woman who’d found a $20-an-hour job after nine years of unemployment; a tall, lanky, panhandler from Louisiana who kept informal guard over her and other women at the center; a 63-year-old part-time school crossing guard who cared for his dying mother for 16 years, then lived off the proceeds from the sale of her house until the money ran out; two retired school teachers; a 23-year-old Palo Alto native who stayed with his mother in a rental car after his old car spontaneously combusted; and, for about six months, Suzan and James. “They didn’t fit this image that the powers that be are trying to create about homeless people. They did not fit that image at all,” Suzan told me. “We made sure the premises were respected, because it was an honor to be able to stay there.” She and others told me they cleaned up their areas at the center every morning.

“I said, ‘We have no place to go, and we’re staying right here.’ They were going to know about it.”

Pressured to find a way to move the residents out, the police department went to the city council claiming they needed a law banning vehicle habitation to address the neighbors’ concerns. Advocates for the homeless said that any problems could be solved if police would just enforce existing laws. Local attorneys warned the city council that such laws could soon be considered unconstitutional, because the Ninth Circuit Court of Appeals was hearing a challenge to a similar law in Los Angeles. Carrie LeRoy, an attorney who advocated on behalf of the unhoused, and other attorneys threatened to file a class-action lawsuit if the vehicle-habitation ban ever went into effect. The city council passed the ban anyway, in a 7-2 vote in August 2013, and the police department and other groups in the city started an outreach program to tell people about the law. “All of them had received these notices from the city,” LeRoy said, “And it was basically like, ‘Get out of our town.’”

A few weeks later, the city council also voted to close the showers at Cubberley and give it a 10:30 p.m. curfew, which made it illegal to sleep there. On their last night there, in October 2013, Suzan and James left around 8 p.m. so they wouldn’t get caught past the new curfew. They tried some old haunts and got kicked out. The stress of living in the van was hard on James. Around this time, James decided to end his dialysis. “Of course, we knew what that meant,” Suzan said.

One night, about a month after leaving Cubberley, the police pulled Suzan and James over. Their registration was expired. “This officer, he got a wild hair, and he said, ‘I’m going to impound your car,’ and called the tow truck.” Suzan told me. They got out of the car. Without pushing and demanding, she realized, she was never going to get out of the situation. She told me she said to the officer, “This is our home, and if you impound it we will not have a home.” He insisted. “I said ‘That’s fine. You do that. We will stay right here. I will put the beds out, I will put what we need here, right here on the sidewalk.” Other officers arrived and talked to them. They asked Suzan whether, surely, there was some other place they could go. “I said, ‘We have no place to go, and we’re staying right here.’ I was going to make a stink. They were going to know about it.” Suzan told me people were poking their heads out of their homes, and she realized the bigger fuss she made, the more likely officers might decide just to leave them alone.

Because James’s health had continued to worsen, he and Suzan finally qualified for motel vouchers during the cold weather. They got a room in a rundown hotel. “It had a microwave and a hot bath,” Suzan said. In his last few days, James was given a spot in a hospice in San Jose, and Suzan went with him. “It was so cut-and-dry. They said, ‘This is an end-of-life bed, period,’ ” Suzan said. “And I never said that to James.” He died on February 17, 2014, and a few weeks later a friend of theirs held a memorial service for James at her house. Suzan wore an old silk jacket of her mother’s, one that would later be ruined by moisture in the van, and a necklace Nancy had made. They ate James’s favorite foods—cornbread, shrimp, and pound cake. Suzan had a few motel vouchers left, and afterward stayed with friends and volunteers for a few weeks each, but she felt she was imposing.

That summer, she returned to her van. It was different without James; she realized she’d gotten to know him better during their van life than she ever had before. Maybe it was his dementia, but as they drove around or sat together, squished amidst their stuff, he’d started to tell her long stories, over and over, of his youth in Georgia. She’d never heard the tales before, but she’d started to be able to picture it all. On her own, without his imposing figure beside her, Suzan was scared, and more than a little lonely. Most nights, she stayed tucked away in a church parking lot, without permission from the pastor, hidden between bushes and vans. The law wasn’t being enforced, but sleeping in the lot made her a kind of a criminal. “The neighbors never gave me up,” she said.


Suzan told me she was in a fog of denial after James’s death, but it’s probably what protected her because homelessness is exhausting. “You start to lose it after a while,” she said. “You feel disenfranchised from your own society.” The Downtown Streets Team, a local homeless organization, had been helping her look for a long-term, stable housing solution. Indeed, Suzan told me that at various times, she and James had 27 applications in for affordable housing in Palo Alto. (When he died, she had to start over, submitting new applications for herself.) Her social worker at the local senior citizens center, Emily Farber, decided to also look for a temporary situation that would get Suzan under a roof for a few months, or even a few weeks. “We were dealing with very practical limitations: having a computer, having a stable phone number,” Farber said. Craigslist was only something Suzan had heard of. She’d finally gotten a cell phone through a federal program, but hadn’t quite mastered it.

For many months, Farber struck out. She didn’t think Suzan would want to live with three 25-year-old Google employees, or that they’d want her, either. She even tried Airbnb. Because Suzan didn’t have a profile, Farber used her own, and wrote to people who had rooms listed to say her 69-year-old friend needed a place to stay in the area for a couple of weeks. “We got three rejections in a row,” she said. Finally, in November, they found a room available for rent for $1,100—about 80 percent of her income from the trust and her widow’s benefits from Social Security. Suzan would have her own bedroom and bathroom in the two-bedroom apartment of a single mother. The mother crowded into the other bedroom with her 16-year-old son and seven-year-old daughter. The only downside for Suzan was that it was in Santa Clara, another charmingly bland suburban enclave in the South Bay, a half hour south of Palo Alto and a world away for Suzan. “It’s out of my comfort zone, but that’s OK!” she told me.

I met Suzan on the day she moved in, and the concept of being able to close a door was almost as unsettling to her as the concept of sleeping in the van had been. “I’m in this kind of survival mode,” she said, and had found a certain comfort in her van. “I’ve got this little cocoon I’m staying in, and everything is within arm’s reach.” She had a big blue mat in the back of the van, like a grown-up version of the kind kindergartners nap on, but soon she’d acquire a bed. She retrieved her old TV from her storage unit. She made a comfortable room, with chairs and a bed and a small table, and decided to eat her meals in there. She only signed a lease for three months, because it wasn’t really sustainable on her fixed income. She’d also applied for an affordable housing complex being built for seniors in Sunnyvale, one that would provide permanent housing for 60 senior citizens from among the 7,000 homeless people in the county at the time. She’d find out in April if she was selected in the lottery. All her hopes were pinned on it.

In the first few weeks after her move to Santa Clara, Suzan spent a healthy portion of her limited income on gas, driving the Explorer back and forth to Palo Alto. After all, her post office box was there, and so were her social workers. Her errands demanded a lot of face time, and in some ways, she still filled her days the way she had before she got her room, moving around trying to solve her problems. Her car was still packed, too, as if she hadn’t let go of the need to drive in it, to move forward, to keep her stuff around her within arm’s reach, as if she were still without a home base.

Two afternoons a week she went to a Palo Alto food closet. She usually made it right before it closed, in the early afternoons. When her number was called, she went up to the counter to watch the volunteer sort through what was left on the shelves, finding the most recently expired items—these were older goods grocery stores couldn’t keep past their sell-by dates. Suzan’s politeness was, as always, almost formal, from an earlier era, when being ladylike was a learned skill. The volunteer would ask her if she wanted milk, or peaches, or a serving-size Baggie of cereal, and she’d say, “Yes, very much so!” These days, she got to take raw eggs instead of the boiled ones, a treat reserved for those with kitchens. Her requests were glancing rather than direct. “Have you any lettuce?” and the answer was often no. I said it seemed like an efficient operation. Suzan said, “I really know the drill!”

Suzan needed to visit her social worker, Julia Lang, at the Downtown Streets Team office to get the form that allowed her to go to an even better food bank. She asked the receptionist whether her social worker was in. She wasn’t, and Suzan explained she was looking for the food bank vouchers. Then the receptionist asked for her address. That stopped Suzan. The receptionist explained that the pantry was for Palo Alto residents, and Suzan was considering, for the first time, whether that counted her. Suzan explained that she and her husband had gone to the pantry the year before, and said they should be in the system. We waited while the receptionist looked. Suzan waved at someone she’d seen around for years, from her car-dwelling days. Suzan told the receptionist, again, that they really should be in the system. But they weren’t. Suzan said that was OK, and she would come back. The receptionist said, “Are you sure? I just need your ID and your address.” Suzan demurred. She needed to talk to her social worker. This is what it meant to have to leave her hometown. She was leaving the city where she and James had known people, the city where James had died, the city where she’d grown up and near where she’d raised her own daughter. It was the city where she knew where to go, where she’d figured out how to be homeless. It was the city where she knew the drill.


That homelessness persists in Silicon Valley has puzzled me. It has an extremely wealthy population with liberal, altruistic values. Though it has a large homeless population relative to its size, in sheer numbers it’s not as large as New York City’s or L.A.’s. Some of the reasons could be found in the meeting on November 17, 2014, when the city finally overturned the car-camping ban. It had never been enforced because, as predicted, the Ninth Circuit had overturned L.A.’s ban. In the end, all but one person who’d voted for the ban the first time around voted to overturn it. The lone dissenter was councilman Larry Klein. “The social welfare agency in our area is the county, not the city,” he said. “To think we can solve the homeless problem just doesn’t make sense.”

This idea was repeated many times among city officials—that homelessness was too big an issue for the city to resolve. The city of Palo Alto itself has one full-time staff member devoted to homelessness, and it coordinates with county and nonprofit networks to counsel, house, and feed the homeless.
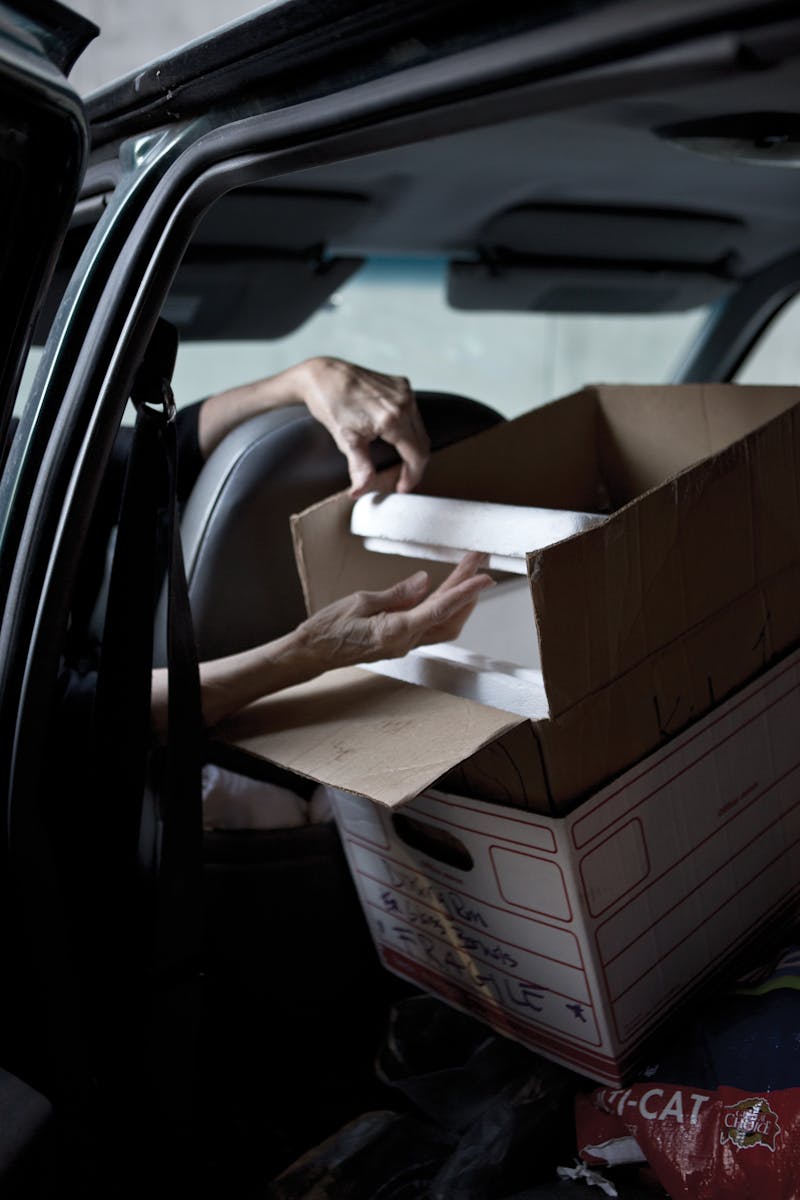
imageSuzan shows where she stored food in her car while homeless.

During the fight over the ban, the city tried to devise an alternative—a program that would allow car dwellers to park at churches—but then left the details up to the faith community to work out. Nick Selby, an attorney and member of the Palo Alto Friends Meeting House, said he and his fellow Quakers met with community resistance when they tried to accommodate three or four car dwellers on their tiny lot. Neighbors circulated a petition listing concerns like “the high prevalence of mental illness, drug abuse, and communicable diseases in the homeless population” and the risk of declining property values. But Selby said some of their concerns were fair. “People who objected were saying to the city, ‘What’s your program?’” Selby said. “And the city really had no answer to those questions.” Without a solid plan and logistical help from the city, other churches were reluctant to step forward. “The churches weren’t prepared to deal with this,” he said. After the church car-camping plan fell through, the city council said it had no choice but a ban.

Santa Clara County, too, struggles to address the problem. The county is participating in federal programs to build permanent supportive housing for the chronically homeless population, the population of long-term homeless who typically have interacting mental health and substance abuse problems. But land is expensive here, and the area is shortchanged by the federal formula that disperses funds. California, ever in budget-crisis mode, provides limited state funds. There isn’t a dedicated funding stream from the cities, which don’t necessarily pay a tax to the county for these projects, and local affordable housing developments are often rejected by residents as Palo Alto’s was. In September, the city of San Jose and the county announced a $13 million program to buy old hotels and renovate them as shelters, which will make 585 new beds available. While advocates credit the county’s efforts with cutting the estimated homeless population by 14 percent since 2013, the number of people like Suzan, who hide in their cars, is almost certainly underestimated. But most such efforts are centered in San Jose. Chris Richardson, a director of the Bay Area’s Downtown Streets Team, said what needs to happen is not a mystery: Other cities have to fund affordable housing, they have to fund more of it, and they have to do it in their own neighborhoods, without relying on San Francisco and San Jose to absorb all of the area’s poverty and problems. “You can’t just ship them down to the big, poor city,” he said.

When Palo Alto originally passed the car-camping ban, it also devoted $250,000 to the county’s homelessness program. When they voted to rescind the ban, council members asked for an update on what happened to the money. The city staff was not prepared to report on how it had been spent at that council meeting, more than a year into the funding. Members of the council again reiterated their desire to help the homeless. “Helping the homeless” was tabled, as a general idea, for another agenda at another meeting, as it always seems to be, or passed off to the county, or to someone else—and so helping the homeless is something nobody does.


Through the winter, Suzan remained ill; it was a bad flu season. She kept paying the rent on her room, on her storage units, on her P.O. box in Palo Alto, and she tried setting aside money she owed on parking tickets. Some months she’d run out of gas money to drive the 15 miles to Palo Alto and check her mail or visit her social workers. She was waiting to hear about the affordable apartment.

In May, she was denied. Suzan had bad credit, both because of the unpaid storage unit she and James had lost and because otherwise her credit history was so thin. Julia Lang, one of her social workers, told me she couldn’t even get a credit score for Suzan. Lang said people get denied on credit, or because they make too little for affordable housing that’s supposedly intended for extremely low-income people, all the time. “When you’re that destitute and have gone through so many complicated situations, what are the chances that your credit’s going to be good?” she said.

Suzan was livid and despondent, and she decided to appeal. “I wasn’t going to take that lying down,” Suzan told me. “I was proud of myself.” Catholic Charities helped her appeal. Suzan had to write a letter showing how she intended to repair her credit, and that she understood why it was bad in the first place. During the months of back and forth, Suzan bought a new Jeep, only one year newer than the Explorer, in case she needed to sleep in her car again. In July, she learned she’d won her appeal. She had two weeks to get her affairs in order, pay the first month’s rent and security deposit, and move in. Her social workers helped her with some of the move-in costs, and she signed a lease for a year.

I saw Suzan again in August, about three weeks after she’d moved in. Her hair was trimmed. She was wearing a brightly colored muumuu, blue and green with tropical flowers—“It’s a housedress but you can wear it out on the street!”—and a green sweater tied around her shoulders. She seemed relaxed and rested, and I told her so. Her bed was full of folded clothes, and her room was still in disarray. She was trying to cull her storage unit so that she could get a smaller one and cut down on rent. Most of the people in her complex had been in the same boat as Suzan, or had been worse off. She pays $810 a month, the amount determined to be affordable for her income. It had taken her more than three years, help from at least three social workers, and thousands of dollars, but she was finally stably housed. At least, for a year. 

Sunday, July 30, 2017

Norcros PLC Interim Results - ADVFN

Read article : Norcros PLC Interim Results - ADVFN
Norcros (LSE:NXR)
Historical Stock Chart 2 Years : From Oct 2015 to Oct 2017 Click Here for more Norcros Charts. TIDMNXR RNS Number : 4598F Norcros PLC 12 November 2015 12 November 2015 Norcros plc Results for the six months ended 30 September 2015 'Strong momentum within our businesses' Norcros, the market leading supplier of innovative branded showers, taps, bathroom accessories, tiles and adhesives, today announces its results for the six months ended 30 September 2015. Financial Summary 2015 2014 % change % change as reported at constant currency ----------------------- ---------- ---------- ------------- ------------- Revenue GBP118.7m GBP108.6m +9.3% +12.0% ----------------------- ---------- ---------- ------------- ------------- Underlying* operating profit GBP9.9m GBP7.4m +34% ----------------------- ---------- ---------- ------------- ------------- Underlying* profit before tax GBP9.4m GBP6.7m +40% ----------------------- ---------- ---------- ------------- ------------- Profit before tax GBP7.0m GBP6.3m +11% ----------------------- ---------- ---------- ------------- ------------- Underlying operating cash flow** GBP13.3m GBP11.6m +15% ----------------------- ---------- ---------- ------------- ------------- Diluted underlying EPS * 11.8p 8.1p +46% ----------------------- ---------- ---------- ------------- ------------- Net debt GBP29.2m GBP20.0m ----------------------- ---------- ---------- ------------- ------------- Interim dividend per share 2.2p 1.85p +19% ----------------------- ---------- ---------- ------------- ------------- * Underlying is before IAS 19R administrative expenses, acquisition related costs and exceptional operating items and, where relevant, before non-cash finance costs ** Underlying operating cash flow means cash generated from continuing operations before exceptional cash flows and pension fund deficit recovery contributions Restated for the 10:1 share consolidation completed on 29 September 2015 Highlights -- Strong first half performance -- Revenue increased by 12.0% on a constant currency basis -- Underlying operating profit increased by 34% to GBP9.9m -- Underlying profit before tax increased by 40% to GBP9.4m -- Profit before tax increased by 11% to GBP7.0m -- Continued strong underlying operating cash generation: 104% of underlying EBITDA -- Acquisition of Croydex completed on 25 June 2015 -- Diluted underlying earnings per share 46% higher at 11.8p -- Interim dividend increased by 19% to 2.2p per share Martin Towers, Chairman, commented: "I am pleased to announce a strong set of results for the six months ended 30 September 2015. Not only has the Group continued to make excellent progress in its existing businesses, but it has continued to advance towards its strategic targets with the acquisition of Croydex at the end of June 2015. With our strong brands, leading market positions and continued self-help initiatives focused on market share gain the Group is well positioned to make further progress. Given the strong first half performance and momentum within our businesses, the Board now expects the Group to achieve underlying operating profit marginally ahead of market expectations for the year to 31 March 2016." There will be a presentation today at 9.30 am for analysts at the offices of Hudson Sandler, 29 Cloth Fair, London, EC1A 7NN. The supporting slides will be available on the Norcros website at http://www.norcros.com later in the day. ENQUIRIES Norcros plc Tel: 01625 547700 Nick Kelsall, Group Chief Executive Martin Payne, Group Finance Director Hudson Sandler Tel: 0207 796 4133 Nick Lyon Charlie Jack Katie Matthews Notes to Editors -- Norcros is a leading supplier of high quality and innovative showers, taps, bathroom accessories, ceramic wall and floor tiles and adhesive products with operations primarily in the UK and South Africa. -- Based in the UK, Norcros operates under five brands: - Triton Showers - Market leader in the manufacture and marketing of showers in the UK - Vado - A leading manufacturer and supplier of taps, mixer showers, bathroom accessories and valves - Croydex - A market-leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories - Johnson Tiles - A leading manufacturer and supplier of ceramic tiles in the UK - Norcros Adhesives - Manufacturer of tile & stone adhesives, grouts and related products -- Based in South Africa, Norcros operates under three brands: - Tile Africa - Chain of retail stores focused on ceramic and porcelain tiles, and associated products such as sanitary ware, showers and adhesives - Johnson Tiles South Africa - Manufacturer of ceramic and porcelain tiles - TAL - The leading manufacturer of ceramic and building adhesives -- Norcros is headquartered in Wilmslow, Cheshire and employs around 1800 people. The Company is listed on the London Stock Exchange. For further information please visit the Company website: http://www.norcros.com/ Chairman's statement I am pleased to announce a strong set of results for the six months ended 30 September 2015. Not only has the Group continued to make excellent progress in its existing businesses, but it has continued to advance towards its strategic targets with the acquisition of Croydex at the end of June 2015. Market conditions in the UK continue to be mixed, with the trade sector continuing to perform well driven by new house build and commercial specifications, although RMI driven demand is muted and retail markets generally remain challenging. In South Africa, market conditions have been impacted by the recent slow-down in China affecting the commodity sector which is a significant part of the South African economy. However, the strong self-help culture evident in all our businesses has continued to offset these challenges and has been a key factor in delivering these strong results. Underlying operating profit rose by 34% to GBP9.9m (2014: GBP7.4m) representing an improved margin of 8.3% (2014: 6.8%). UK performance benefitted from the return to profitability of Johnson Tiles UK following its manufacturing inefficiencies in the prior year and the three month contribution from Croydex. South Africa nearly doubled its underlying operating profit despite a weaker Rand, driven by strong constant currency revenue growth and an improvement in underlying profit performance in all three businesses including a return to profitability at Johnson Tiles South Africa. Through a combination of strong underlying EBITDA and continued prudent management of working capital, underlying operating cash generation was GBP13.3m (2014: GBP11.6m), representing 104% of underlying EBITDA (2014: 112%). This performance and a cash outflow of GBP20.1m relating to the acquisition of Croydex left net debt at GBP29.2m compared to GBP14.2m at 31 March 2015 and represents leverage of 1.1 times underlying proforma EBITDA. Acquisition of Croydex As previously announced, the Group acquired 100% of the ordinary share capital of Croydex Group Limited ("Croydex"), a market leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories, on 25 June 2015. The acquisition of Croydex is an important next step in the Group's growth strategy to increase revenue to GBP420m by 2018 and follows on from the very successful integration of the Vado business which Norcros acquired in March 2013. The addition of the Croydex business to the Group's existing portfolio has increased the breadth of our product range in the bathroom segment and has enabled the Group to offer an even broader array of complementary bathroom products to our customers. Croydex will also benefit from the global distribution channels, sourcing skills and strong financial position of the enlarged Group. I am excited by the prospects for Croydex within the Norcros Group and have been impressed by the energy and enthusiasm of its management and employees. Results Revenue for the six month period to 30 September 2015 at GBP118.7m (2014: GBP108.6m) was 12.0% higher on a constant currency basis compared to the prior year, and 9.3% on a Sterling reported basis. Of this growth, 5.5% was attributable to a three month contribution from Croydex. On a like for like basis excluding Croydex, constant currency growth was 6.5% and 4.0% on a Sterling reported basis. Underlying operating profit rose by 34% to GBP9.9m (2014: GBP7.4m) reflecting improvements in both the UK and South Africa together with a three month contribution from Croydex. Underlying profit before taxation increased by 40% to GBP9.4m (2014: GBP6.7m) reflecting the higher underlying operating profit and lower interest costs driven by improved margins offset by increased borrowings due to the acquisition of Croydex in June 2015. Profit before taxation for the period was GBP7.0m (2014: GBP6.3m), reflecting increased underlying profit before taxation, higher exceptional operating income of GBP2.3m (2014: GBP0.3m) primarily as a result of settlement in the period of a contractual dispute with Morrisons relating to a previous agreement to sell them freehold land in Tunstall, Stoke on Trent, offset by higher non-underlying interest of GBP1.3m (2014: income of GBP0.6m) and higher acquisition related costs of GBP2.6m (2014: GBP0.5m) relating to the final year of the Vado earn out mechanism of GBP1.3m and the costs of acquiring Croydex of GBP0.8m. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Diluted underlying earnings per share were 46% higher at 11.8p (2014: 8.1p restated for the 10:1 share consolidation), reflecting improved underlying earnings. Financial We have continued to demonstrate strong cash conversion with underlying operating cash generated in the period at GBP13.3m (2014: GBP11.6m), representing 104% of underlying EBITDA for the period (2014: 112%). There was a working capital outflow of GBP0.2m in the period which compared to a GBP0.6m inflow in the prior period. A pension deficit recovery payment of GBP1.1m (2014: GBP1.0m) in the period (as part of the GBP2.0m plus CPI per annum contribution agreed with the Trustee in 2013) and cash inflows relating to exceptional items of GBP0.7m (2014: outflows of GBP0.7m) resulted in net cash generated from continuing operations at GBP12.9m (2014: GBP9.9m). Investment in capital expenditure in the period amounted to GBP3.2m (2014: GBP3.4m) and has remained consistent at 1.1 times depreciation. Net debt increased in the six months to 30 September 2015 by GBP15.0m to GBP29.2m principally as a result of the acquisition of Croydex, which, including costs related to the acquisition of GBP0.8m, resulted in a net cash outflow in the period of GBP20.1m. The gross deficit relating to our UK defined benefit pension scheme as calculated under IAS 19R has improved slightly from a deficit of GBP44.3m at 31 March 2015 to a deficit of GBP42.4m at 30 September 2015. The reduction in the deficit principally reflects an increase in the discount rate to 3.8% net of a lower return on scheme assets. During the previous year the plan undertook a number of liability management exercises which resulted in the recognition of a net settlement gain of GBP1.7m. A further gain of GBP0.4m has been recognised in the period as a result of these exercises which has been included within exceptional operating items. Property As highlighted in the Group's 2015 Annual Report, the contractual dispute arising from the conditional sale of part of the surplus land in Tunstall to a subsidiary of Wm Morrison Supermarkets plc was settled on 15 May 2015. The Company has recognised exceptional operating income of GBP1.9m in relation to this settlement. Dividend The Board is declaring an interim dividend of 2.20p per share reflecting the strong first half performance and its confidence in the Group's future prospects. Taking into account the 10:1 share consolidation which took place on 29 September 2015, this represents an increase of 19% over the restated interim dividend from the previous year of 1.85p per ordinary share. The dividend is payable on 7 January 2016 to shareholders on the register on 4 December 2015. The shares will be quoted as ex-dividend on 3 December 2015. Operating review UK For the six months ended 30 September 2015 total revenue in our UK businesses was 9.8% ahead of the prior period at GBP79.9m (2014: GBP72.8m). On a like for like basis excluding Croydex revenue of GBP5.8m, total revenue increased by 1.8%. Underlying operating profit at GBP8.0m was 25% higher than last year at GBP6.4m and represents an improved return on sales of 10.0% (2014: 8.8%). The trends in our UK markets seen in the prior year have continued into the first half of this year, with good growth in the trade sector, but a challenging retail sector. Triton Our market leading shower operation, Triton Showers, recorded revenue growth of 3.1% for the six month period to 30 September 2015 to GBP26.2m (2014: GBP25.4m). UK revenue for Triton was 1.9% higher than the prior year. Revenue from the UK trade sector increased by 3.3% compared to the prior year, with strong trading across major national merchants and electrical wholesale customers and a much improved performance in the specification sector, which has been a key area of focus for the business. The retail sector however remains challenging, principally due to weak consumer demand and the impact of product range changes at some of the major DIY accounts. Notwithstanding this, Triton still delivered marginally higher retail revenue compared to the previous year. Triton has continued to invest significantly in new product development and in product innovation with the recent launch of the T80ZFF thermostatic electric shower range which further strengthens our offer in the growing thermostatic shower market. Export markets account for 17% of Triton's overall revenue and have continued to grow, increasing by 10.0% compared to the prior year. The principal export market for Triton is Ireland, where a revitalised new build and RMI sector has helped drive revenue growth. Markets further afield, principally Latin America, continue to be developed. We have invested in both new product development and marketing including representation at a number of major trade fairs in the region. Triton has continued to generate strong cashflows and delivered underlying operating profits which were marginally ahead of last year. Vado Our leading manufacturer of taps, mixer showers, bathroom accessories and valves, Vado, recorded revenue of GBP15.9m for the period (2014: GBP14.8m), 7.4% higher than the prior year. UK revenue was 16.7% higher than the prior year, with growth in both the retail and trade segments. In the trade sector, we continue to make strong progress in both residential and commercial specifications, benefitting particularly from increased new private housing programmes. In retail, we are beginning to see the benefits of investing in the expansion of the sales team and were recently recognised as tap brand of the year by BKU magazine in its inaugural awards. Export revenue, which accounts for approximately 30% of Vado revenue, was 9.6% lower than the same period last year. This performance reflects a mixed picture with lower revenue outside of our major Middle East market held back by credit issues with a number of sub-Saharan customers and a number of larger projects last year not being repeated this year. However, in the Middle East we grew revenue strongly in the first half of this year reflecting more buoyant construction activity. We have recently increased our presence in this market and established a directly employed resource in the region to strengthen the Vado brand in the important specification sector. Underlying operating profits were ahead of the same period last year driven largely by revenue growth. Croydex Croydex, our market-leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories, which was acquired on 25 June 2015, recorded revenue of GBP5.8m for the three month period since acquisition to 30 September 2015, in line with our expectations. Whilst it was not under Group ownership for the full period, revenue for the six months ended 30 September 2015 was GBP10.9m, 3.7% higher than the prior year. UK sales at GBP10.3m were in line with the prior year with the challenging retail environment being offset by growth in the trade sector. Export sales of GBP0.6m were GBP0.4m higher than the prior period, reflecting the additional focus employed to target growth outside the UK, with particular success being achieved in Germany. Operationally, Croydex has been integrated into the Norcros group seamlessly, and the performance of the business since acquisition has been highly encouraging, with the business generating an underlying profit performance in line with the Board's expectations. Johnson Tiles Our UK market leading ceramic tile manufacturer and a market leader in the supply of both own manufactured and imported tiles, Johnson Tiles, recorded revenue 4.5% lower than the same period last year at GBP27.9m (2014: GBP29.2m). UK revenue was 2.7% lower than the comparative period last year. Excellent progress continues to be made in the trade segment with revenue 5.0% higher, notwithstanding that last year included the one-off benefit of the supply of ceramic poppies which formed the main part of the World War I commemorations at the Tower of London. Again, good progress has been made in the specification sector, with projects completed in the period for Holiday Inn and Total Fitness. In the retail sector, subdued demand in the DIY sector generally combined with the withdrawal from some unprofitable ranges resulted in revenues 9.6% lower than the prior year. Export revenue was also 16.7% lower than the prior year principally reflecting the combined impact of weak market conditions in France and credit issues in the Middle East. Operationally, the excellent progress made at the end of the last financial year has been sustained throughout this first half period. As a result of management actions manufacturing efficiencies have significantly improved compared to the prior period. This, together with the continued trade revenue growth, have been key factors in delivering a solid underlying operating profit performance for the period, a marked improvement over the small operating loss recorded in the prior period. Norcros Adhesives Norcros Adhesives, our manufacturer and supplier of tile and stone adhesives and ancillary products, once again demonstrated excellent growth with revenue 20.6% higher at GBP4.1m (2014: GBP3.4m). This performance principally reflects further development of our distribution channels in the trade segment, as well as some initial success in the retail DIY sector. The business continues to develop innovative new products to address the technical issues in fixing tiles to different types of substrate, for example the launch of the Ultima8 B+ range, which solves the problem of fixing tiles to bituminous surfaces. Additionally, the business has continued to invest in future growth, achieving the ISO 14001 accreditation for environmental management, commencing the construction of a new training centre and laboratory in the UK and establishing a local presence in the Middle East to better capitalise on the opportunities in the significant specification market in this region. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) This continued strong growth has delivered an underlying operating profit performance ahead of the same period last year. South Africa Once again our South African businesses reported another period of double digit constant currency growth resulting in revenue 16.9% higher than prior year on a constant currency basis. Reported Sterling revenue was 8.4% higher at GBP38.8m (2014: GBP35.8m), reflecting an 8% weaker Rand. Underlying operating profit at GBP1.9m was 90% higher than the previous period (2014: GBP1.0m) despite the weaker Rand adversely impacting reported profits by GBP0.1m. This represents a significantly improved return on sales of 4.9% (2014: 2.7%). All three businesses delivered an improvement in local currency underlying operating profit performance. Our South African operations have made further progress in the first half of the year with all three businesses growing ahead of the market as we continue to implement our strategy of growing our brands through geographic expansion and range diversification. Gross margins improved against the previous year, with the benefits in our supply chain and production efficiencies delivering tangible benefits over the period. Johnson Tiles South Africa Our tile manufacturing business, Johnson Tiles South Africa, achieved independent sector revenue of GBP5.4m (2014: GBP5.2m), 12.5% higher than prior year on a constant currency basis, and 3.8% higher on a reported Sterling basis. Following the investment in two inkjet printers over the last two years we have successfully enriched our product offer with the launch of a number of additional inkjet ranges and a new rectangular product format in response to market trends. An improved product offer and a consistent manufacturing performance have resulted in a marked improvement in performance. As reported in our last annual report, Johnson Tiles South Africa experienced some manufacturing disruption as a result of the national electricity load-shedding programme. Consequently a new standby diesel generator has been successfully installed in the period which will significantly reduce the impact of being unable to operate the manufacturing facility in the event of a power outage. Notwithstanding the disruption from load shedding prior to the generator being installed, the business delivered an underlying operating profit compared to a small underlying operating loss in the prior period. TAL Our market leading adhesive business, TAL, delivered constant currency independent sector revenue growth of 20.5% in the period, or an 11.9% increase on a Sterling reported basis to GBP9.4m (2014: GBP8.4m). This growth was achieved through market share gain in domestic markets and through continued focus on growing sub-Saharan export markets, as well as product range extensions, such as a new 2kg bag to its grout range and a new powdered bond range, both of which have received a favourable market reaction. In addition to the considerable growth in revenue, we have continued to drive profitability through further improvements in plant and procurement efficiencies. This has been reflected in a stronger underlying operating profit performance than the prior year. Tile Africa Revenue at our leading retailer of wall and floor tiles, adhesives, showers, sanitaryware and bathroom fittings, Tile Africa, increased by 16.5% on a constant currency basis compared to the prior year, and by 8.1% on a Sterling reported basis to GBP24.0m (2014: GBP22.2m). Tile Africa currently operates from 29 stores and four franchises, with a new store in Boksburg, Gauteng, expected to open by the end of this financial year. The new CX format stores that we developed to improve the overall retail customer experience, and were showcased in the last Annual Report, have continued to perform strongly, and consequently there are plans to retrofit this format into further stores. The store at Lenasia has recently been refitted as a factory outlet aimed at the emerging consumer segments following on from the positive results achieved at the existing store of this type in Silverton. The improved CX store layout, together with benefits from our increased focus on in-stock and on-display offering has been reflected in market share gain and revenue growth, and in an improved underlying operating profit compared to the prior year. Share consolidation On 29 September 2015 the Company undertook an exercise to consolidate its existing 1p ordinary shares into new 10p ordinary shares, and the new shares began to be traded on the London Stock Exchange on 30 September. The resolution permitting the Board to effect the consolidation had been passed at the Company's AGM on 22 July. The Board considered it was important to reduce the number of shares in issue to a level more appropriate for a company of Norcros's size, and to make the shares more attractive to investors, whilst having no effect on the relative holdings of individual shareholders. Full details of the share consolidation are provided on the Company's website www.norcros.com. Summary and outlook The Group has made a very pleasing start to the year, with each of our businesses delivering an improvement in underlying operating profit performance. As I have already highlighted, we took decisive management action in our tiles businesses in both the UK and South Africa to address the operational challenges of recent years and now have a much stronger base from which to develop our medium term growth plans. Whilst conditions in our UK retail and export markets remain testing, we continue to capitalise on the demand opportunities in the more positive trade sector where we continue to perform strongly. The acquisition of the Croydex business is a further step in realising our strategic target of generating revenues of GBP420m by 2018 and importantly the business has already been smoothly integrated into the Group. With our strong brands, leading market positions and continued self-help initiatives focused on market share gain the Group is well positioned to make further progress. Given the strong first half performance and momentum within our businesses, the Board now expects the Group to achieve underlying operating profit marginally ahead of market expectations for the year to 31 March 2016. M. G. Towers Chairman 12 November 2015 Condensed consolidated income statement Six months to 30 September 2015 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014* 2015* (unaudited) (unaudited) (audited) Notes GBPm GBPm GBPm ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Continuing operations Revenue 118.7 108.6 222.1 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Underlying operating profit 9.9 7.4 17.0 IAS 19R administrative expenses (0.8) (0.8) (1.7) Acquisition related costs 4 (2.6) (0.5) (2.2) Exceptional operating items 4 2.3 0.3 (2.5) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Operating profit 8.8 6.4 10.6 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Finance costs 7 (1.1) (0.8) (1.4) Exceptional finance costs 7 - (0.4) (0.4) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Total finance costs 7 (1.1) (1.2) (1.8) Finance income 7 - 1.6 3.3 IAS 19R finance cost (0.7) (0.5) (1.1) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit before taxation 7.0 6.3 11.0 Taxation 6 (1.6) (1.6) (2.9) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit for the period from continuing operations 5.4 4.7 8.1 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit for the period from discontinued operations - 0.1 0.1 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Profit for the period 5.4 4.8 8.2 (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Earnings per share attributable to the owners of the Company Basic earnings per share: From continuing operations 5 9.0p 8.0p 13.6p From discontinued operations 5 - 0.2p 0.2p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- From profit for the period 5 9.0p 8.2p 13.8p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Diluted earnings per share: From continuing operations 5 8.7p 7.7p 13.1p From discontinued operations 5 - 0.2p 0.2p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- From profit for the period 5 8.7p 7.9p 13.3p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Weighted average number of shares for basic earnings per share (millions) 5 60.1 59.0 59.2 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Non-GAAP measures Underlying profit before taxation (GBPm) 3 9.4 6.7 15.8 Underlying earnings (GBPm) 3 7.3 5.0 13.0 Basic underlying earnings per share 5 12.2p 8.4p 21.9p Diluted underlying earnings per share 5 11.8p 8.1p 21.1p ----------------------------------------------------------------------- ----- ------------ ------------ ---------- * The results of previous periods have been restated where required to reflect the revised presentation of acquisition related costs and the 10:1 share consolidation completed on 29 September 2015. Condensed consolidated statement of comprehensive income Six months to 30 September 2015 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------------------------------------------- ------------ ------------ ---------- Profit for the period 5.4 4.8 8.2 -------------------------------------------------------------------------- ------------ ------------ ---------- Other comprehensive income and expense: Items that will not subsequently be reclassified to the income statement Actuarial gains/(losses) on retirement benefit obligations 1.6 (14.8) (18.8) Items that may be subsequently reclassified to the income statement Foreign currency translation adjustments (6.0) (1.2) (0.6) -------------------------------------------------------------------------- ------------ ------------ ---------- Other comprehensive expense for the period (4.4) (16.0) (19.4) -------------------------------------------------------------------------- ------------ ------------ ---------- Total comprehensive income/(expense) for the period 1.0 (11.2) (11.2) -------------------------------------------------------------------------- ------------ ------------ ---------- Attributable to equity shareholders arising from Continuing operations 1.0 (11.4) (11.4) Discontinued operations - 0.2 0.2 -------------------------------------------------------------------------- ------------ ------------ ---------- 1.0 (11.2) (11.2) ------------------------------------------------------------------------- ------------ ------------ ---------- Items in the statement are disclosed net of tax. Condensed consolidated balance sheet At 30 September 2015 At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) Notes GBPm GBPm GBPm -------------------------------------- ----- ------------ ------------ --------- Non-current assets Goodwill 29.5 22.0 22.2 Intangible assets 12.2 4.8 4.7 Property, plant and equipment 37.5 36.8 37.6 Investment properties - 4.3 - Derivative financial instruments 15 - 0.2 - Deferred tax assets 6 11.2 14.1 13.8 -------------------------------------- ----- ------------ ------------ --------- 90.4 82.2 78.3 -------------------------------------- ----- ------------ ------------ --------- Current assets Inventories 56.3 51.0 52.2 Trade and other receivables 43.6 42.1 40.5 Derivative financial instruments 15 1.0 - 2.1 Cash and cash equivalents 7.8 4.5 5.6 108.7 97.6 100.4 -------------------------------------- ----- ------------ ------------ --------- Current liabilities Trade and other liabilities (60.5) (54.1) (54.9) Derivative financial instruments 15 (0.3) (0.8) (1.0) Current tax liabilities (1.4) (1.7) (1.3) Financial liabilities - borrowings 8 (4.5) (4.1) (1.4) (66.7) (60.7) (58.6) -------------------------------------- ----- ------------ ------------ --------- Net current assets 42.0 36.9 41.8 -------------------------------------- ----- ------------ ------------ --------- Total assets less current liabilities 132.4 119.1 120.1 -------------------------------------- ----- ------------ ------------ --------- Non-current liabilities Financial liabilities - borrowings 8 (32.5) (20.4) (18.4) Pension scheme liability 12 (42.4) (40.6) (44.3) Other non-current liabilities (2.1) (1.5) (1.4) Provisions (3.2) (3.7) (3.3) -------------------------------------- ----- ------------ ------------ --------- (80.2) (66.2) (67.4) -------------------------------------- ----- ------------ ------------ --------- Net assets 52.2 52.9 52.7 -------------------------------------- ----- ------------ ------------ --------- Financed by: Ordinary share capital 9 6.1 5.9 6.0 Share premium 1.0 0.9 1.0 Retained earnings and other reserves 45.1 46.1 45.7 -------------------------------------- ----- ------------ ------------ --------- Total equity 52.2 52.9 52.7 -------------------------------------- ----- ------------ ------------ --------- Condensed consolidated statement of cash flow (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Six months to 30 September 2015 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) Notes GBPm GBPm GBPm ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash generated from operations 10 12.9 10.0 16.2 Income taxes paid (0.6) (0.2) (0.5) Interest paid (0.5) (0.7) (1.3) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net cash generated from operating activities 11.8 9.1 14.4 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash flows from investing activities Proceeds from sale of investment property - - 6.1 Proceeds from sale of property, plant and equipment - 0.4 0.4 Purchase of investment property - - (0.9) Purchase of property, plant and equipment (3.2) (3.4) (7.0) Acquisition of subsidiary undertakings net of cash acquired (20.5) (0.3) (0.5) Disposal of subsidiary undertakings net of cash divested - 3.8 3.8 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net cash (used in)/generated from investing activities (23.7) 0.5 1.9 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash flows from financing activities Net proceeds from issue of ordinary share capital - - 0.2 Drawdown/(repayment) of borrowings 14.0 (10.1) (12.1) Costs of raising debt finance - (0.7) (0.7) Dividends paid to equity shareholders (2.2) (2.0) (3.1) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net cash generated from/(used in) financing activities 11.8 (12.8) (15.7) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Net (decrease)/increase in cash at bank and in hand and bank overdrafts (0.1) (3.2) 0.6 Cash at bank and in hand and bank overdrafts at beginning of the period 4.2 3.7 3.7 Exchange movements on cash and bank overdrafts (0.8) (0.1) (0.1) ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Cash at bank and in hand and bank overdrafts at end of the period 3.3 0.4 4.2 ------------------------------------------------------------------------------ ------------ ------------ ---------- Non-GAAP measures Underlying operating cash flow 3 13.3 11.6 22.9 ----------------------------------------------------------------------- ----- ------------ ------------ ---------- Condensed consolidated statements of changes in equity Six months to 30 September 2015 (unaudited) Ordinary Retained share Share Treasury Translation earnings/ capital premium reserve reserve (losses) Total GBPm GBPm GBPm GBPm GBPm GBPm ------------------------------------------------- -------- ------- -------- ----------- --------- ----- At 31 March 2015 6.0 1.0 (0.1) (9.1) 54.9 52.7 Comprehensive income: Profit for the period - - - - 5.4 5.4 Actuarial gain on retirement benefit obligations - - - - 1.6 1.6 Other comprehensive expense: Foreign currency translation adjustments - - - (6.0) - (6.0) Total other comprehensive (expense)/ income - - - (6.0) 7.0 1.0 ------------------------------------------------- -------- ------- -------- ----------- --------- ----- Transactions with owners: Dividends paid - - - - (2.2) (2.2) Share option schemes and warrants 0.1 - (0.1) - 0.7 0.7 ------------------------------------------------- -------- ------- -------- ----------- --------- ----- At 30 September 2015 6.1 1.0 (0.2) (15.1) 60.4 52.2 ------------------------------------------------- -------- ------- -------- ----------- --------- ----- Six months to 30 September 2014 (unaudited) Ordinary Retained share Share Treasury Translation earnings/ capital premium reserve reserve (losses) Total GBPm GBPm GBPm GBPm GBPm GBPm ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 31 March 2014 5.8 0.9 - (8.5) 67.3 65.5 Comprehensive income: Profit for the period - - - - 4.8 4.8 Other comprehensive expense: Actuarial loss on retirement benefit obligations - - - - (14.8) (14.8) Foreign currency translation adjustments - - - (1.2) - (1.2) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Total other comprehensive expense - - - (1.2) (14.8) (16.0) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Transactions with owners: Dividends paid - - - - (2.0) (2.0) Share option schemes and warrants 0.1 - (0.1) - 0.6 0.6 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 30 September 2014 5.9 0.9 (0.1) (9.7) 55.9 52.9 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Year ended 31 March 2015 (audited) Ordinary Retained share Share Treasury Translation earnings/ capital premium reserve reserve (losses) Total GBPm GBPm GBPm GBPm GBPm GBPm ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 31 March 2014 5.8 0.9 - (8.5) 67.3 65.5 Comprehensive income: Profit for the year - - - - 8.2 8.2 Other comprehensive expense: Actuarial loss on retirement benefit obligations - - - - (18.8) (18.8) Foreign currency translation adjustments - - - (0.6) - (0.6) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Total other comprehensive expense - - - (0.6) (18.8) (19.4) ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Transactions with owners: Shares issued 0.2 0.1 (0.1) - - 0.2 Dividends paid - - - - (3.1) (3.1) (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Share option schemes and warrants - - - - 1.3 1.3 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ At 31 March 2015 6.0 1.0 (0.1) (9.1) 54.9 52.7 ------------------------------------------------- -------- ------- -------- ----------- --------- ------ Notes to the accounts Six months to 30 September 2015 1. Accounting policies General information The Company is a public limited company which is listed on the London Stock Exchange and incorporated and domiciled in the UK. This condensed consolidated interim financial information was approved for issue on 12 November 2015. This condensed consolidated financial information does not comprise statutory accounts within the meaning of Section 434 of the Companies Act 2006. This condensed consolidated interim financial information has been neither audited nor reviewed. Basis of preparation This condensed consolidated interim financial information for the six months to 30 September 2015 has been prepared in accordance with the Disclosure and Transparency Rules of the Financial Conduct Authority and with IAS 34, 'Interim financial reporting', as adopted by the European Union. The Directors consider, after making appropriate enquiries at the time of approving the condensed consolidated interim financial information, that the Company and the Group have adequate resources to continue in operational existence and, accordingly, that it is appropriate to adopt the going concern basis in the preparation of the condensed consolidated interim financial information. The condensed consolidated interim financial information should be read in conjunction with the Annual Report and Accounts for the year ended 31 March 2015, which has been prepared in accordance with IFRS as adopted by the European Union. The Annual Report and Accounts was approved by the Board on 18 June 2015 and delivered to the Registrar of Companies. The report of the external auditor on the financial statements was unqualified. Accounting policies The principal accounting policies applied in the preparation of this condensed consolidated interim financial information are included in the financial report for the year ended 31 March 2015. These policies have been applied consistently to all periods presented. Taxes on income in the interim periods are accrued using the tax rate that would be applicable to the expected total annual profits or losses. New standards, amendments to standards and interpretations The following new standards, amendments to standards or interpretations are mandatory for the first time for the financial year beginning 1 April 2015. The Group has adopted the following new standards, amendments and interpretations now applicable. None of these standards and interpretations has had any material effect on the Group's results or net assets. Applicable for financial years Standard or interpretation Content beginning on or after -------------------------------------- ----------------- --------------------- Amendment to IAS 19 (revised) Employee benefits 1 April 2015 Annual improvements to IFRSs 2010-2012 Various 1 April 2015 Annual improvements to IFRSs 2011-2013 Various 1 April 2015 -------------------------------------- ----------------- --------------------- The following standards, amendments and interpretations are not yet effective and have not been adopted early by the Group: Applicable for financial years Standard or interpretation Content beginning on or after --------------------------------- ----------------------------------------------------- --------------------- Amendment to IFRS 10 Consolidated financial statements 1 April 2016 Amendment to IFRS 11 Joint arrangements 1 April 2016 Amendment to IFRS 12 Disclosure of interests in other entities 1 April 2016 IFRS 14 Regulatory deferral accounts 1 April 2016 Amendment to IAS 1 Presentation of financial statements 1 April 2016 Amendment to IAS 16 Property, plant and equipment 1 April 2016 Amendment to IAS 27 Separate financial statements 1 April 2016 Amendment to IAS 28 Investments in associates and joint ventures 1 April 2016 Amendment to IAS 38 Intangible assets 1 April 2016 Amendment to IAS 41 Agriculture 1 April 2016 Annual improvements to IFRSs 2014 Various 1 April 2016 IFRS 15 Revenue from contracts with customers 1 April 2018 IFRS 9 Financial instruments: classification and measurement 1 April 2018 --------------------------------- ----------------------------------------------------- --------------------- None of these standards or interpretations is expected to have a material impact on the Group. Risks and uncertainties The principal strategic level risks and uncertainties affecting the Group, together with the approach to their mitigation, remain as set out on pages 24 to 27 in the 2015 Annual Report, which is available on the Group's website (www.norcros.com). In summary the Group's principal risks and uncertainties are: -- key commercial relationships; -- accounting for customer rebates and other trade promotional spend; -- competition; -- reliance on production facilities; -- staff retention and recruitment; -- foreign currency exchange risk; -- interest rate risk; -- pension scheme management; -- energy price risk; -- additional capital requirements to fund ongoing operations; -- performance against banking covenants; -- changing consumer preferences; -- overseas operations; and -- acquisition risk. The Chairman's Statement in this condensed consolidated interim financial information includes comments on the outlook for the remaining six months of the financial year. Forward-looking statements This condensed consolidated interim financial information contains forward-looking statements. Although the Group believes that the expectations reflected in these forward-looking statements are reasonable, it can give no assurance that these expectations will prove to be correct. Due to the inherent uncertainties, including both economic and business risk factors underlying such forward-looking information, actual results may differ materially from those expressed or implied by these forward-looking statements. The Group undertakes no obligation to update any forward-looking statements, whether as a result of new information, future events or otherwise. Accounting estimates and judgments The preparation of condensed consolidated interim financial information requires management to make judgments, estimates and assumptions that affect the application of accounting policies and the reported amount of assets and liabilities, income and expense. Actual results may differ from these estimates. In preparing the condensed consolidated interim financial information, the significant judgments made by management in applying the Group's accounting policies and the key sources of estimation uncertainty were the same as those applied to the consolidated financial statements for the year ended 31 March 2015. 2. Segmental reporting The Group operates in two main geographical areas: the UK and South Africa. All inter-segment transactions are made on an arm's length basis. The chief operating decision maker, which is considered to be the Board, assesses performance and allocates resources based on geography as each segment has similar economic characteristics, complementary products, distribution channels and regulatory environments. Continuing operations - 6 months to 30 September 2015 (unaudited) --------------------------------------------- South UK Africa Group Notes GBPm GBPm GBPm ---------------------------------- ----- ------------- -------------- -------------- Revenue 79.9 38.8 118.7 ---------------------------------- ----- ------------- -------------- -------------- Underlying operating profit 8.0 1.9 9.9 IAS 19R administrative expenses (0.8) - (0.8) Acquisition related costs 4 (2.6) - (2.6) Exceptional operating items 4 2.3 - 2.3 ---------------------------------- ----- ------------- -------------- -------------- (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) Operating profit 6.9 1.9 8.8 ---------------------------------- ----- ------------- -------------- -------------- Finance costs (net) (1.8) ---------------------------------- ----- ------------- -------------- -------------- Profit before taxation 7.0 Taxation 6 (1.6) ---------------------------------- ----- ------------- -------------- -------------- Profit from continuing operations 5.4 ---------------------------------- ----- ------------- -------------- -------------- Net debt 10 (29.2) ---------------------------------- ----- ------------- -------------- -------------- Continuing operations - 6 months to 30 September 2014 (unaudited)* ---------------------------------------------- South UK Africa Group Notes GBPm GBPm GBPm ---------------------------------- ----- ------------- --------------- -------------- Revenue 72.8 35.8 108.6 ---------------------------------- ----- ------------- --------------- -------------- Underlying operating profit 6.4 1.0 7.4 IAS 19R administrative expenses (0.8) - (0.8) Acquisition related costs 4 (0.5) - (0.5) Exceptional operating items 4 0.3 - 0.3 ---------------------------------- ----- ------------- --------------- -------------- Operating profit 5.4 1.0 6.4 ---------------------------------- ----- ------------- --------------- -------------- Finance costs (net) (0.1) ---------------------------------- ----- ------------- --------------- -------------- Profit before taxation 6.3 Taxation 6 (1.6) ---------------------------------- ----- ------------- --------------- -------------- Profit from continuing operations 4.7 ---------------------------------- ----- ------------- --------------- -------------- Net debt 10 (20.0) ---------------------------------- ----- ------------- --------------- -------------- * The results have been restated to reflect the revised presentation of acquisition related costs. Continuing operations - Year ended 31 March 2015 (audited) --------------------------------------- South UK Africa Group Notes GBPm GBPm GBPm ------------------------------------------------ ------ ----------- ------------ ------------ Revenue 149.1 73.0 222.1 ------------------------------------------------ ------ ----------- ------------ ------------ Underlying operating profit 13.8 3.2 17.0 IAS 19R administrative expenses (1.7) - (1.7) Acquisition related costs 4 (2.2) - (2.2) Exceptional operating items 4 (2.3) (0.2) (2.5) ------------------------------------------------ ------ ----------- ------------ ------------ Operating profit 7.6 3.0 10.6 ------------------------------------------------ ------ ----------- ------------ ------------ Finance income (net) 0.4 ------------------------------------------------ ------ ----------- ------------ ------------ Profit before taxation 11.0 Taxation 6 (2.9) ------------------------------------------------ ------ ----------- ------------ ------------ Profit for the year from continuing operations 8.1 ------------------------------------------------ ------ ----------- ------------ ------------ Net debt 10 (14.2) ------------------------------------------------ ------ ----------- ------------ ------------ There are no differences from the last Annual Report in the basis of segmentation or in the basis of measurement of segment profit or loss. 3. Non-GAAP measures Condensed Consolidated Income Statement 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------------------------------- ------------ ------------ ---------- Profit before taxation from continuing operations 7.0 6.3 11.0 Adjusted for: IAS 19R administrative expenses 0.8 0.8 1.7 Acquisition related costs 2.6 0.5 2.2 Exceptional operating items (2.3) (0.3) 2.5 Amortisation of costs of raising debt finance 0.1 0.1 0.1 Amortisation of costs of raising debt finance - exceptional - 0.4 0.4 Net movement on fair value of derivative financial instruments 0.5 (1.6) (3.3) Discount on property lease provisions - - 0.1 IAS 19R finance cost 0.7 0.5 1.1 --------------------------------------------------------------- ------------ ------------ ---------- Underlying profit before taxation 9.4 6.7 15.8 Taxation attributable to underlying profit before taxation (2.1) (1.7) (2.8) --------------------------------------------------------------- ------------ ------------ ---------- Underlying earnings 7.3 5.0 13.0 --------------------------------------------------------------- ------------ ------------ ---------- The Directors believe that underlying profit before taxation and underlying earnings provide shareholders with additional useful information on the underlying performance of the Group. Underlying profit before taxation is defined as profit before taxation, IAS 19R administrative expenses, acquisition related costs, exceptional operating items, exceptional finance costs, amortisation of costs of raising finance, net movement on fair value of derivative financial instruments, discounting of property lease provisions and finance costs relating to pension schemes. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------- ------------ ------------ ---------- Operating profit from continuing operations 8.8 6.4 10.6 Adjusted for: Depreciation 2.9 3.0 6.0 IAS 19R administrative expenses 0.8 0.8 1.7 Acquisition related costs 2.6 0.5 2.2 Exceptional operating items (2.3) (0.3) 2.5 -------------------------------------------- ------------ ------------ ---------- Underlying EBITDA 12.8 10.4 23.0 -------------------------------------------- ------------ ------------ ---------- (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) EBITDA is a measure commonly used by investors and financiers to assess business performance. Underlying EBITDA has been provided which reflects EBITDA as adjusted for IAS 19R administrative expenses, acquisition related costs and exceptional operating items. The Directors consider that these measures provide shareholders with additional useful information on the performance of the Group. Condensed Consolidated Statement of Cash Flow 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------------------------------------- ------------ ------------ ---------- Cash generated from continuing operations (note 10) 12.9 9.9 16.1 Adjusted for: Cash (inflows)/outflows from exceptional items and acquisition related costs (0.7) 0.7 4.7 Pension fund deficit recovery contributions 1.1 1.0 2.1 ----------------------------------------------------------------------------- ------------ ------------ ---------- Underlying operating cash flow 13.3 11.6 22.9 ----------------------------------------------------------------------------- ------------ ------------ ---------- Underlying operating cash flow is defined as cash generated from continuing operations before cash outflows from exceptional items and pension fund deficit recovery contributions. The Directors believe that underlying operating cash flow provides shareholders with additional useful information on the underlying cash generation of the Group. 4. Acquisition related costs and exceptional operating items An analysis of acquisition related costs and exceptional operating items is shown below. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------- ------------ ------------ ---------- Acquisition related costs Deferred remuneration(1) 1.2 0.3 1.1 Intangible asset amortisation(2) 0.3 0.2 0.3 Staff costs and advisory fees(3) 1.1 - 0.8 --------------------------------- ------------ ------------ ---------- 2.6 0.5 2.2 --------------------------------- ------------ ------------ ---------- 1 Consideration payable to the former shareholders of Vado and Croydex which is required to be treated as remuneration and, accordingly, is expensed to the income statement as incurred. 2 Non-cash amortisation charges in respect of intangible assets recognised following the acquisitions of Vado and Croydex. 3 Costs of maintaining an in-house acquisitions department and professional advisory fees incurred in connection with the Group's business combination activities. In the 6 months to 30 September 2015 this included GBP0.8m in connection with the acquisition of Croydex. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------------ ------------ ------------ ---------- Exceptional operating items Legal claim(1) (1.9) 0.1 0.3 Pension scheme settlement gain(2) (0.4) - (1.7) Profit on disposal of surplus property(3) - (0.4) (0.4) Sheffield lease surrender(4) - - 2.5 Loss on disposal of property portfolio(5) - - 1.5 Restructuring costs(6) - - 0.3 (2.3) (0.3) 2.5 ------------------------------------------ ------------ ------------ ---------- 1 The legal claim relating to the land at the Highgate site in Tunstall, UK was settled in the period. Under the terms of the settlement with Wm Morrison Supermarkets plc the Group received a payment of GBP2.0m. Costs in connection with the claim of GBP0.1m were incurred in the period (2014: GBP0.1m). 2 The Group implemented a liability management exercise in the previous year in connection with its principal UK defined benefit pension scheme. This resulted in a further settlement gain of GBP0.4m being recognised in the period in addition to the GBP1.7m gain in the previous year. 3 A profit of GBP0.4m was generated in the previous year following the sale of a small parcel of land in Braintree, UK. 4 In the previous year the Group exited its onerous lease in connection with the Orgreave Drive, Sheffield property at a cost of GBP2.5m. 5 The Group's remaining surplus freehold property portfolio was sold to Clowes Developments (UK) Ltd in March 2015 for net proceeds of GBP6.1m, leading to a loss on disposal of GBP1.5m. 6 Restructuring costs related to redundancies and asset write-downs as a result of restructuring initiatives throughout the Group's business units. 5. Earnings per share Basic and diluted earnings per share Basic earnings per share (EPS) is calculated by dividing the profit attributable to shareholders by the weighted average number of ordinary shares in issue during the year, excluding those held in the Norcros Employee Benefit Trust. For diluted EPS, the weighted average number of ordinary shares in issue is adjusted to assume conversion of all potential dilutive ordinary shares. As described in note 9, on 29 September 2015 the Company consolidated its existing ordinary shares of 1p each into new ordinary shares of 10p each. In order to effect fair comparison, the comparative figures for share numbers and earnings per share have been restated to reflect the impact of the share consolidation. The calculation of EPS is based on the following profits and numbers of shares: 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------------------- ------------ ------------ ---------- Profit for the period from continuing operations 5.4 4.7 8.1 Profit for the period from discontinued operations - 0.1 0.1 --------------------------------------------------- ------------ ------------ ---------- Profit for the period 5.4 4.8 8.2 --------------------------------------------------- ------------ ------------ ---------- 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) Number Number Number (restated) (restated) ----------------------------------------------------------------- ------------ ------------ ----------- Weighted average number of shares for basic earnings per share 60,126,284 58,959,370 59,223,135 Share options and warrants 1,902,048 2,159,547 2,303,299 Weighted average number of shares for diluted earnings per share 62,028,332 61,118,917 61,526,434 ----------------------------------------------------------------- ------------ ------------ ----------- 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (audited) (unaudited) (restated) (restated) ----------------------------- ------------ ------------ ----------- Basic earnings per share: From continuing operations 9.0p 8.0p 13.6p From discontinued operations - 0.2p 0.2p ----------------------------- ------------ ------------ ----------- From profit for the period 9.0p 8.2p 13.8p (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) ----------------------------- ------------ ------------ ----------- Diluted earnings per share: From continuing operations 8.7p 7.7p 13.1p From discontinued operations - 0.2p 0.2p ----------------------------- ------------ ------------ ----------- From profit for the period 8.7p 7.9p 13.3p ----------------------------- ------------ ------------ ----------- Basic and diluted underlying earnings per share Basic and diluted underlying earnings per share have also been provided which reflect underlying earnings from continuing operations divided by the weighted average number of shares set out above. 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------- ------------ ------------ ---------- Underlying earnings for the period (note 3) 7.3 5.0 13.0 -------------------------------------------- ------------ ------------ ---------- 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) -------------------------------------- ------------ ------------ ---------- Basic underlying earnings per share 12.2p 8.4p 21.9p Diluted underlying earnings per share 11.8p 8.1p 21.1p -------------------------------------- ------------ ------------ ---------- 6. Taxation Taxation comprises: 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------------- ------------ ------------ ---------- Current UK taxation 0.5 0.5 0.4 Deferred Origination and reversal of temporary differences 1.1 1.1 2.5 -------------------------------------------------- ------------ ------------ ---------- Taxation 1.6 1.6 2.9 -------------------------------------------------- ------------ ------------ ---------- Current tax expense is recognised based on management's estimate of the weighted average annual income tax rate expected for the full financial year. Deferred tax assets and liabilities are offset when there is a legally enforceable right to offset current tax assets against current tax liabilities and when the deferred income taxes relate to the same fiscal authority. Deferred tax is calculated in full on temporary differences under the liability method. The movement on the deferred tax account is as shown below: 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------------------------------------- ------------ ------------ ---------- Deferred tax asset at the beginning of the period 13.8 11.6 11.6 Charged to the income statement (1.1) (1.1) (2.5) (Charged)/credited to statement of comprehensive income (0.4) 3.7 4.7 Acquisitions (see note 13) (0.8) - - Exchange movement (0.3) (0.1) - -------------------------------------------------------- ------------ ------------ ---------- Deferred tax asset at the end of the period 11.2 14.1 13.8 -------------------------------------------------------- ------------ ------------ ---------- At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------- ------------ ------------ --------- Accelerated capital allowances 2.6 2.9 2.7 Tax losses 2.5 3.8 3.3 Other timing differences (2.4) (0.7) (1.1) Deferred tax asset relating to pension deficit 8.5 8.1 8.9 ----------------------------------------------- ------------ ------------ --------- 11.2 14.1 13.8 ----------------------------------------------- ------------ ------------ --------- 7. Finance income and costs 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------------------- ------------ ------------ ---------- Finance costs Interest payable on bank borrowings 0.5 0.7 1.2 Amortisation of costs of raising debt finance 0.1 0.1 0.1 Movement on fair value of derivative financial instruments 0.5 - - Unwind of discount on property lease provisions - - 0.1 ----------------------------------------------------------- ------------ ------------ ---------- Finance costs 1.1 0.8 1.4 ----------------------------------------------------------- ------------ ------------ ---------- Exceptional finance costs(1) - 0.4 0.4 ----------------------------------------------------------- ------------ ------------ ---------- Total finance costs 1.1 1.2 1.8 ----------------------------------------------------------- ------------ ------------ ---------- Finance income Movement on fair value of derivative financial instruments - (1.6) (3.3) ----------------------------------------------------------- ------------ ------------ ---------- Total finance income - (1.6) (3.3) ----------------------------------------------------------- ------------ ------------ ---------- 1 Following the refinancing of the Group's banking facilities in July 2014, the unamortised costs relating to the previous facility were written off in full. 8. Borrowings At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------- ------------ ------------ --------- Non-current Bank borrowings (unsecured): - bank loans 33.0 21.0 19.0 - less: costs of raising finance (0.5) (0.6) (0.6) --------------------------------- ------------ ------------ --------- Total non-current 32.5 20.4 18.4 --------------------------------- ------------ ------------ --------- Current Bank borrowings (unsecured): - bank overdrafts 4.5 4.1 1.4 --------------------------------- ------------ ------------ --------- Total borrowings 37.0 24.5 19.8 --------------------------------- ------------ ------------ --------- The fair value of bank loans equals their carrying amount as they bear interest at floating rates. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) The repayment terms of borrowings are as follows: At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ----------------------------------------------------- ------------ ------------ --------- Not later than one year 4.5 4.1 1.4 ----------------------------------------------------- ------------ ------------ --------- After more than one year: - between one and two years - - - - later than two years and not later than five years 33.0 21.0 19.0 - costs of raising finance (0.5) (0.6) (0.6) ----------------------------------------------------- ------------ ------------ --------- 32.5 20.4 18.4 ----------------------------------------------------- ------------ ------------ --------- Total borrowings 37.0 24.5 19.8 ----------------------------------------------------- ------------ ------------ --------- In July 2014 the Group agreed an unsecured GBP70m revolving credit facility with a GBP30m accordion facility with Lloyds Bank plc, Barclays Bank plc and HSBC Bank plc. The banking facility is in force for five years to July 2019. Net debt The Group's net debt is calculated as follows: At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm -------------------------- ------------ ------------ --------- Cash and cash equivalents (7.8) (4.5) (5.6) Total borrowings 37.0 24.5 19.8 -------------------------- ------------ ------------ --------- Net debt 29.2 20.0 14.2 -------------------------- ------------ ------------ --------- 9. Called up share capital At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------- ------------ ------------ --------- Issued and fully paid 60,995,930 ordinary shares of 10p each 6.1 - - 594,917,377 ordinary shares of 1p each - 5.9 6.0 --------------------------------------- ------------ ------------ --------- Total 6.1 5.9 6.0 --------------------------------------- ------------ ------------ --------- Following the approval by shareholders of the consolidation of 1p ordinary shares into ordinary shares of 10p at the Annual General Meeting of the Company held on 22 July 2015, the Company duly completed the share capital consolidation with a record date of 29 September 2015. As a result of the consolidation, the ordinary shares of 1p each were amended to new ordinary shares of 10p each. The share consolidation had no impact on the value of the Company's issued and fully paid share capital. 10. Consolidated Cash Flow Statements (a) Cash generated from continuing operations 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------------------------------------------------ ------------ ------------ ---------- Profit before taxation 7.0 6.3 11.0 Adjustments for: - IAS 19R administrative expenses included in the above 0.8 0.8 1.7 - acquisition related costs included in the above 2.6 0.5 2.2 - exceptional operating items included in the above (2.3) (0.3) 2.5 - cash inflows/(outflows) from exceptional items and acquisition related costs 0.7 (0.7) (4.7) - depreciation 2.9 3.0 6.0 - pension fund deficit recovery plan contributions (1.1) (1.0) (2.1) - loss on disposal of property, plant and equipment - - 0.1 - total finance costs 1.1 1.2 1.8 - finance income - (1.6) (3.3) - IAS 19R finance cost 0.7 0.5 1.1 - share-based payments 0.7 0.6 1.3 ------------------------------------------------------------------------------ ------------ ------------ ---------- Operating cash flows before movements in working capital 13.1 9.3 17.6 Changes in working capital: - increase in inventories (4.4) (1.4) (2.0) - increase in trade and other receivables (1.0) (0.8) (1.4) - increase in payables 5.2 2.8 1.9 ------------------------------------------------------------------------------ ------------ ------------ ---------- Cash generated from continuing operations 12.9 9.9 16.1 ------------------------------------------------------------------------------ ------------ ------------ ---------- Cash flows from exceptional items includes expenditure charged to exceptional provisions relating to onerous lease costs, acquisition related costs (excluding deferred remuneration) and other business rationalisation and restructuring costs. (b) Cash generated from discontinued operations 6 months to 6 months to Year ended 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm --------------------------------------------------------- ------------ ------------ ---------- Profit before taxation - - - Adjustments for: - depreciation - - - --------------------------------------------------------- ------------ ------------ ---------- Operating cash flows before movements in working capital - - - Changes in working capital: - decrease in inventories - 0.4 0.4 - increase in trade and other receivables - (0.1) (0.1) - decrease in payables - (0.2) (0.2) --------------------------------------------------------- ------------ ------------ ---------- Cash generated from discontinued operations - 0.1 0.1 --------------------------------------------------------- ------------ ------------ ---------- Cash generated from operations 12.9 10.0 16.2 --------------------------------------------------------- ------------ ------------ ---------- (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT) (c) Analysis of net debt Cash included within Cash and assets held-for-sale overdrafts Debt Total GBPm GBPm GBPm GBPm ------------------------- -------------------- ---------- ------ ------ At 1 April 2014 0.5 3.2 (30.6) (26.9) Cash flow (0.5) 1.1 12.1 12.7 Other non-cash movements - - 0.1 0.1 Exchange movement - (0.1) - (0.1) ------------------------- -------------------- ---------- ------ ------ At 31 March 2015 - 4.2 (18.4) (14.2) ------------------------- -------------------- ---------- ------ ------ At 1 April 2014 0.5 3.2 (30.6) (26.9) Cash flow (0.5) (2.7) 10.1 6.9 Other non-cash movements - - 0.1 0.1 Exchange movement - (0.1) - (0.1) ------------------------- -------------------- ---------- ------ ------ At 30 September 2014 - 0.4 (20.4) (20.0) ------------------------- -------------------- ---------- ------ ------ At 1 April 2015 - 4.2 (18.4) (14.2) Cash flow - (0.1) (14.0) (14.1) Other non-cash movements - - (0.1) (0.1) Exchange movement - (0.8) - (0.8) ------------------------- -------------------- ---------- ------ ------ At 30 September 2015 - 3.3 (32.5) (29.2) ------------------------- -------------------- ---------- ------ ------ 11. Dividends A final dividend in respect of the year ended 31 March 2015 of GBP2.2m (0.375p per 1p ordinary share) was paid on 29 July 2015. On 12 November 2015 the Board declared an interim dividend in respect of the year ended 31 March 2016 of GBP1.3m (2.2p per 10p ordinary share). This dividend will be paid on 7 January 2016 and is not reflected in this condensed consolidated interim financial information. 12. Retirement benefit obligations (a) Pension costs Norcros Security Plan The Norcros Security Plan (the "Plan"), the principal UK pension scheme of Norcros plc subsidiaries, is funded by a separate trust fund which operates under UK trust law and is a separate legal entity from the Company. The Plan is governed by a Trustee board which is required by law to act in the best interests of the Plan members and is responsible for setting policies together with the Company. It is predominantly a defined benefit scheme with a modest element of defined contribution benefits. The valuation used for IAS 19R disclosures has been produced by KPMG, a firm of qualified actuaries, to take account of the requirements of IAS 19R in order to assess the liabilities of the scheme at 30 September 2015. Scheme assets are stated at their market value at 30 September 2015. (b) IAS 19R, 'Retirement benefit obligations' The principal assumptions used to calculate the scheme liabilities of the Norcros Security Plan under IAS 19R are: At At At 30 September 30 September 31 March 2015 2014 2015 --------------------- ------------ ------------ -------- Discount rate 3.80% 3.90% 3.30% Inflation rate (RPI) 3.00% 3.05% 2.90% Inflation (CPI) 2.00% 2.05% 1.90% Salary increases 2.25% 3.30% 2.15% --------------------- ------------ ------------ -------- The amounts recognised in the Condensed Consolidated Balance Sheet are determined as follows: At At At 30 September 30 September 31 March 2015 2014 2015 (unaudited) (unaudited) (audited) GBPm GBPm GBPm ------------------------------------ ------------ ------------ --------- Total market value of scheme assets 367.8 385.0 397.0 Present value of scheme liabilities (410.2) (425.6) (441.3) ------------------------------------ ------------ ------------ --------- Pension deficit (42.4) (40.6) (44.3) ------------------------------------ ------------ ------------ --------- 13. Business combinations On 25 June 2015, the Group acquired 100% of the ordinary share capital of Croydex Group Limited ("Croydex"), a market leading, innovative designer, manufacturer and distributor of high quality bathroom furnishings and accessories. The acquisition of Croydex is an important next step in the Group's growth strategy to increase revenue to GBP420m by 2018 and follows on from the very successful integration of the Vado business, which Norcros acquired in March 2013. Adding the Croydex business to the Group's existing portfolio will increase the breadth of our product range in the bathroom segment and enable the Group to offer an even broader range of complementary bathroom products to our customers. Croydex will also benefit from the global distribution channels, sourcing skills and strong financial position of the enlarged Group. Croydex is incorporated in England and is based in Andover, Hampshire. The following table summarises the consideration paid for Croydex and the provisional fair value of the assets acquired and the liabilities assumed: GBPm ------------------------- ----- Consideration Cash 20.8 Deferred consideration 1.1 ------------------------- ----- 21.9 ------------------------ ----- GBPm --------------------------------------------------- --------- Recognised amounts of identifiable assets and liabilities Intangible assets 7.9 Property, plant and equipment 1.6 Inventories 2.8 Trade and other receivables 5.0 Cash 3.5 Trade and other payables (5.7) Current tax liabilities (0.2) Deferred tax liability (0.8) Total identifiable net assets 14.1 --------------------------------------------------- --------- Goodwill 7.8 Total 21.9 --------------------------------------------------- --------- Due to the proximity of the acquisition date to the date of this interim statement it has not been possible for the Group to finalise the fair values of Croydex's assets and liabilities. The provisional fair value adjustments reflect the preliminary assessment of the value of acquired intangible assets of GBP7.9m, the revaluation of the leasehold property of GBP0.9m, and a deferred tax liability of GBP1.0m mainly arising from the recognition of acquired intangible assets. A full review of the fair values of the identifiable assets and liabilities will take place over the coming months with the expectation that a revised position will be presented in the Group's Annual Report for the year ended 31 March 2016. In most business combinations there is an element of cost which cannot be allocated against the individual assets and liabilities acquired. This residual amount is recognised as goodwill and is supported by a number of factors which do not meet the criteria required for them to be treated as intangible assets. In this case the most significant elements relate to Croydex's unique product portfolio and its knowledgeable workforce. It is not expected at this stage that any of the goodwill will be deductible for tax purposes. The fair value of trade and other receivables is GBP5.0m, which includes trade receivables with a fair value of GBP4.6m. The gross contractual amount for trade receivables due is GBP4.8m, of which GBP0.2m is expected to be uncollectible. Costs relating to the transaction of GBP0.8m have been expensed to the Consolidated Income Statement and included within acquisition related costs. The deferred consideration of GBP1.1m is unconditional and will be paid in the year ended 31 March 2019. As part of the transaction, a long-term incentive scheme has been put in place for the Croydex Managing Director which is dependent on the financial performance of Croydex over the next three years. The maximum amount and current expectation is that GBP0.9m will be payable under this scheme which will be treated as deferred remuneration and included within acquisition related costs in the Consolidated Income Statement. The revenue included in the Condensed Consolidated Statement of Comprehensive Income since 25 June 2015 contributed by Croydex was GBP5.8m. Over the same period, Croydex contributed profit after tax of GBP0.6m. Had Croydex been consolidated from the beginning of the period, the Condensed Consolidated Statement of Income would have shown pro-forma revenue of GBP123.7m and pro-forma profit after tax of GBP5.6m. (MORE TO FOLLOW) Dow Jones Newswires November 12, 2015 02:01 ET (07:01 GMT)